Americans Average Net Worth By Age

Let’s be honest: the phrase “average net worth” sounds about as fun as doing your taxes after a root canal. But stick with me here, because this number is basically your finan...

Let’s be honest: the phrase “average net worth” sounds about as fun as doing your taxes after a root canal. But stick with me here, because this number is basically your financial report card—and it’s more relatable than you think. Your net worth is simply what you own minus what you owe: your savings, your house, your car, your student loans, your credit card balance. It’s the big-picture score of your money life, not just how much you have in your checking account right now.
Why Should You Care? (Spoiler: It’s Not Just for Fancy People)
Imagine you’re at a potluck dinner, and you discover that everyone else brought a homemade pie while you showed up with a bag of chips. That’s kind of how net worth numbers feel—they let you peek at what’s in the financial kitchen of people your age. Knowing the average for your age group helps you see if you’re on track, without the pressure of comparing yourself to your millionaire uncle or that friend who just bought a yacht. It’s a gentle reality check, not a competition.
Plus, tracking your net worth over time is like watching your garden grow—it’s slow, sometimes weedy, but ultimately satisfying when you see the progress. You don’t have to be perfect; you just have to be moving forward.
Must Read
The Numbers: A Simple Breakdown That Won’t Make You Snore
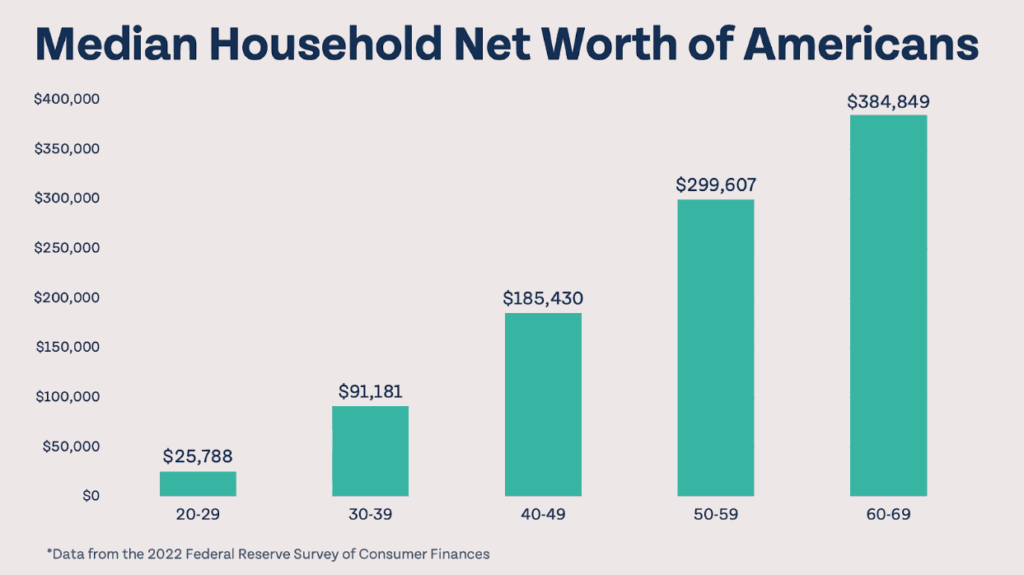
Let’s look at the median net worth by age, because the “average” can get skewed by billionaires who make the rest of us look like we’re collecting pocket change. The following are based on recent Federal Reserve data. For those under 35, the median net worth is around $30,000 to $40,000. If you’re in your twenties or early thirties and you have some savings, a 401(k) that’s not empty, and maybe a little equity in a car, you’re actually doing okay—even if your rent eats half your paycheck.
For the 35–44 crowd, that number climbs to about $60,000 to $90,000. That’s the age when you might finally pay off your grad school debt, buy a starter home, or start actually saving for retirement instead of just hoping it works out. Don’t panic if your number is lower—many people in this age range have kids, car payments, and a mortgage that makes their net worth look like a roller coaster.
 Top 10 Richest People in America (2026 List) – Net Worth, Companies
What About Later? (Spoiler: It Gets Better)
Between 45 and 54, median net worth jumps to roughly $100,000 to $200,000—the sweet spot where panic starts to fade and wisdom kicks in. This is the decade when you might finally stop buying furniture that requires a hex key to assemble. By 55–64, it’s around $200,000 to $400,000, and for those 65 and up, it often hits $300,000 to $500,000. That’s the payoff of decades of small, boring decisions like not buying a third latte every day and actually investing that money instead of letting it rot in a zero-interest checking account.
Here’s the thing: these numbers are just guidelines, not a strict report card that gets sent to your mom. If you’re 40 and your net worth is $5,000, you’re not a failure—you just might need to tweak your habits and start small. Many people have huge net worth swings because of home ownership, inheritance, or just getting lucky with a side hustle. Your personal number is what matters most.
 Average Net Worth By Age Chart
How to Use This Without Making Yourself Miserable
First, calculate your own net worth in about ten minutes. List all your assets: cash, investments, retirement accounts, home equity (what your house is worth minus what you owe), and your car’s value. Then subtract all debts: mortgage, student loans, credit cards, car loans. That’s your number. If it’s negative, don’t panic—it just means you have more debt than assets, which is common for young people. Most millionaires started with a negative net worth and worked their way up.
Second, compare your number to the range for your age group, but don’t obsess. If you’re behind, ask yourself: “What’s one thing I can do this month to nudge it up?” Maybe it’s skipping one takeout meal and putting that $20 into savings. Maybe it’s refinancing a high-interest loan. Small steps compound like magic over time. And yes, the power of compound interest is real—your money can actually grow while you sleep, which is the closest thing to a financial superpower.
 Income Levels America Chart U.S. Incomes Stabilize For First Time
A Little Story to Make You Smile
Meet Jenna, a 38-year-old teacher who thought her net worth was “embarrassing” because she had $12,000 in credit card debt and only $5,000 in savings. She finally calculated it: negative $7,000. But here’s the twist—she also had a 401(k) from her previous job worth $28,000 that she forgot about. Her actual net worth? Positive $21,000. She literally cried from relief. The lesson? You probably have assets you’re ignoring, like that old IRA or that paid-off car. Don’t guess—calculate.
The bottom line: your net worth isn’t a measure of your worth as a human being. It’s just a tool—a flashlight in the dark financial woods. It shows you where you are, not who you are. Use it to make one small, kind adjustment today, and then go buy yourself a treat (maybe even a slice of that homemade pie). You’re doing better than you think.
