Asset Allocation By Age And Net Worth

My friend Dave once called me in a panic. He’d just turned forty, looked at his 401(k), and realized it was somehow more invested in Bitcoin dog coins than in bonds. “I’m too...

My friend Dave once called me in a panic. He’d just turned forty, looked at his 401(k), and realized it was somehow more invested in Bitcoin dog coins than in bonds. “I’m too old for this rollercoaster,” he whispered, as if the crypto gods might hear. I told him his asset allocation had a bigger identity crisis than a teenager in a Hot Topic.
That conversation is why we need to talk about asset allocation by age and net worth. Not the boring textbook version. The real one, where you figure out if you’re building a fortress or a lemonade stand with your money.
The Age Game: Why Your 30s Shouldn’t Look Like Your 60s
Here’s the thing about age: it’s a terrible liar. When you’re twenty-five, your biggest risk isn’t losing money—it’s not making enough. You have decades to recover from a market crash. So, your portfolio should be mostly stocks, like 90% or even 100%. Go ahead, be aggressive. You’re basically a financial adrenaline junkie with a long runway.
Must Read
But when you’re fifty-five? Different story. You don’t have thirty years to wait for that tech stock to bounce back. You have a mortgage, maybe a kid in college, and a retirement party you can practically smell. That’s when you shift to bonds, cash, and stability. Think of it as swapping your sports car for a Volvo—less exciting, but you’ll actually survive the ride.
A classic rule of thumb? Subtract your age from 110 or 120. That’s the percentage of your portfolio that should be in stocks. At forty, that’s 70-80% in stocks. At sixty, it’s 50-60%. (Side note: if you’re seventy and still subtracting from 120, you’re either a masochist or you really love volatility.)
 13.3: Asset Allocation by Age and Timeline - Business LibreTexts
Net Worth: The Plot Twist Nobody Talks About
Now, here’s where it gets juicy. Age is a guide, but net worth is the boss. A thirty-year-old with a $50,000 net worth should invest completely differently than a thirty-year-old who just inherited $2 million. The first person needs growth to build wealth. The second person needs preservation to not blow it.
If you have a small net worth—say, under $100,000 early on—your priority is simple: go all-in on stocks. Low-cost index funds, global ETFs, maybe a smidge of real estate exposure. Don’t mess with bonds. Bonds at that level are like wearing a raincoat in a desert. You’re protecting nothing while missing the sun.
But once your net worth crosses that first big milestone—$500,000 or $1 million—the game changes. You start adding diversification for safety. Real estate, bonds, maybe a dash of cash. Why? Because losing 40% of a million-dollar portfolio hurts way more than losing 40% of a $50,000 portfolio. Psychologically and financially. You feel that one in your bones.
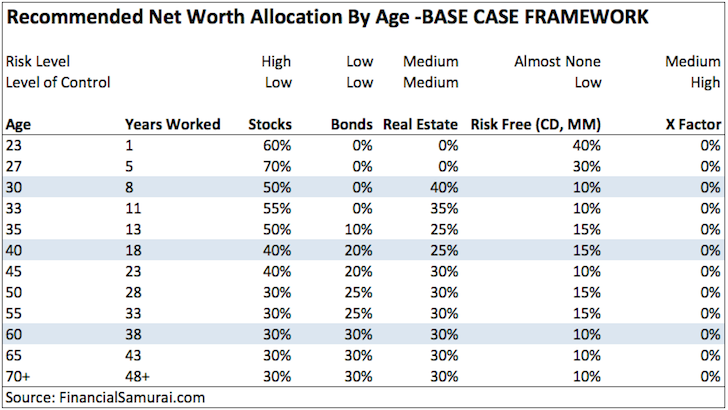 Recommended Net Worth Allocation By Age And Work Experience
The Sweet Spot: When Age and Net Worth Clash
What happens when you’re sixty-five but have a net worth of $10 million? You can actually afford to be more aggressive than the age rule suggests. You’ve already won the game. So put 60% in stocks if you want—you have a huge cushion. Conversely, if you’re thirty with a $5 million net worth from a business sale? Protect your cash, kid. You don’t need to gamble to become a millionaire. You already are one.
I have a cousin who’s forty-two with a net worth of $300,000. He’s 100% in a total stock market fund. Smart. His neighbor is fifty-eight with $3 million—and she’s 50% in bonds and T-bills. Also smart. The allocation isn’t about a magic number; it’s about how close you are to financial independence.
Practical Steps (Without the Sales Pitch)
Here’s your cheat sheet. Under forty and net worth under $500K? Be a stock junkie. Use index funds. Contribute every month. Don’t look at the balance. Over forty and net worth under $1M? Keep 70-80% in stocks, but start adding bonds slowly. Like, 10-15% of your portfolio. Just to test the water.
 Recommended Net Worth Allocation By Age And Work Experience
If your net worth crosses $1M, regardless of age, start building a ladder of safety. That’s bonds, cash equivalents, maybe a rental property. The goal shifts from “get rich” to “stay rich.” And if you’re over sixty with a high net worth? You get a free pass. Do whatever keeps you sleeping at night. Seriously. I’m not being ironic.
One last thing: don’t overthink this. Too many people try to be perfect. They wait for the “right” moment to rebalance. They read twenty articles like this one and then freeze. Just pick a rough split—say, 80/20 stocks to bonds for age forty—and adjust it by 1% each year. That’s it. Consistency beats optimization every single time.
So, go check your portfolio. If it’s filled with memes and anxiety? Dave and I both approve of a rebalance. Your future self—the one who’s sipping coffee on a beach instead of staring at a red ticker—will thank you.
