Asset Allocation For High Net Worth Individuals

Let’s be real for a second: when you think of a “high net worth individual” (HNWI), you probably picture someone in a cashmere hoodie on a private jet, checking their portfoli...

Let’s be real for a second: when you think of a “high net worth individual” (HNWI), you probably picture someone in a cashmere hoodie on a private jet, checking their portfolio between sips of matcha. And while that image isn’t entirely wrong, the real secret sauce isn’t flashy crypto bets or a single, massive real estate gamble. It’s something far less sexy but infinitely more powerful: asset allocation.
Think of it as the architectural blueprint for your financial mansion. You wouldn’t build a house with only a kitchen, right? You’d mix bedrooms, bathrooms, and a home cinema. Similarly, your wealth needs rooms—buckets of assets—that behave differently so your whole financial life doesn’t collapse when one market hiccups.
For most people, allocation is a simple “stocks vs. bonds” equation. For HNWIs? It’s a symphony of complexity—and a lot more fun. We're talking about private equity, venture capital, art, timberland, and even a dash of that “digital gold” we call Bitcoin.
Must Read
The Shifting Goalposts of “Rich”
Here’s a fun fact: to be in the top 1% of global wealth today, you need a net worth of roughly $1.3 million, but that number varies wildly by city. In Monaco? You’re practically a pauper. In Mumbai? You’re a king. The point is, your allocation must match your geography and lifestyle, not a random spreadsheet from a 1990s finance textbook.
Your primary residence, for example, might be a stunning five-bedroom in London or a penthouse in Manhattan. That’s not an “investment” in the traditional sense—it’s a consumption asset. Treating it like a pure growth stock is a rookie mistake. Your home is the stage, not the play.
The modern HNWI portfolio typically uses a core-satellite structure. Think of the core as the boring, steady base—global blue-chip stocks, government bonds, and maybe some high-grade private credit. The satellites are where you can get your thrills: early-stage startups, a vintage car collection, or a contemporary art fund.
Practical Tip: The “2% Rule” for Risk
Want to gamble on that meme-stock revival or a friend’s dog-grooming app? Fine. But cap that “fun money” at 2% of your total liquid net worth. This keeps the lights on if it fails, and makes the win feel like a ludicrous victory instead of a necessity.
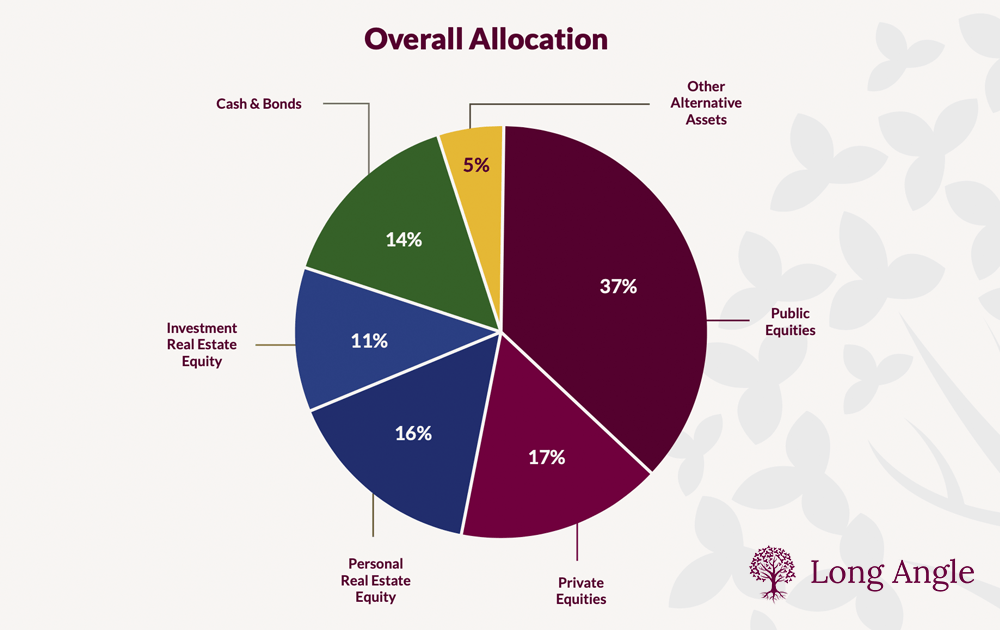 Is Private Equity A Wolf In Sheep’s Clothing?
Cultural reference alert: Remember in Billions, when Bobby Axelrod buys a whole rare whiskey collection? That’s an alternative asset. But he didn’t bet the hedge fund on it. He used it to diversify his sensory pleasures. Snap.
Taxes: The Uninvited Guest at Every Party
Let’s talk about the elephant in the room—or rather, the taxman in the Bentley. For HNWIs, asset location is just as important as allocation. A municipal bond held in a taxable account is tax-free. The same bond in a retirement account? You’re paying Uncle Sam on the way out. That’s just poor choreography.
A savvy move is to park your high-growth, high-taxed assets (like hedge funds or active trading) inside tax-advantaged shelters like a Roth IRA or a trust. Meanwhile, your low-turnover assets—like a buy-and-hold ETF—can live in your regular brokerage accounts. It’s like organizing your closet: sweaters on one side, t-shirts on the other, but with a tax lawyer whispering in your ear.
Fun fact: The U.S. taxes capital gains at a maximum of 20% for high earners, but some states like California add up to 13.3% on top. That’s like ordering a $20 steak and getting a $27 bill. Move to a tax-friendly state? That’s a rebalancing act in itself.
The “Barbell Strategy” for Volatile Times
When inflation is sticky and interest rates are high, top advisors recommend the barbell: pile your cash into super-safe assets (short-term Treasuries, T-bills) on one end, and aggressive growth (private equity, tech stocks) on the other. The middle—long-term bonds or mid-cap stocks—gets crushed. It’s not about balance; it’s about extremes that protect you.
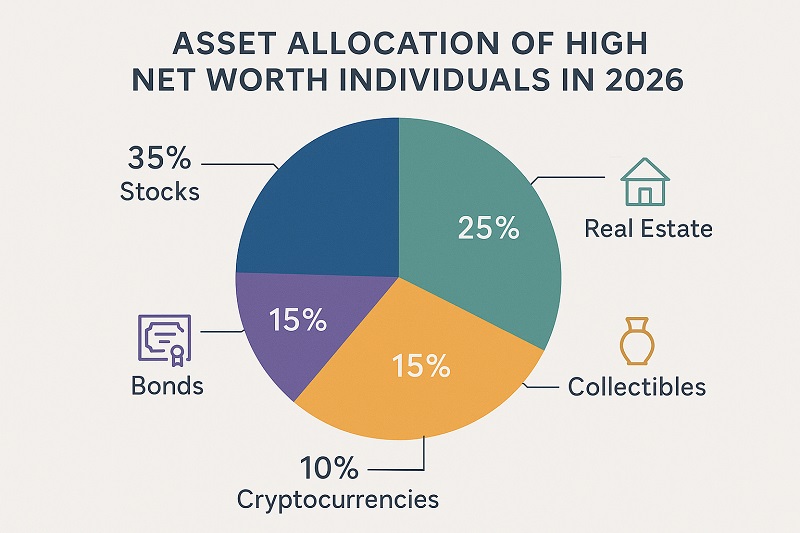 Ultra High Net Worth Asset Allocation: 9 Smart Moves 2026
Example: Your “safe” end might yield 5% in T-bills right now (not bad!). Your “aggressive” end could be a venture capital fund targeting 15-20% returns. The middle? Ouch. Avoid it.
Lifestyle Assets: The Porsche Problem
Here’s where it gets human. You bought a Ferrari. You love it. But it depreciates the moment you drive it off the lot. A classic Porsche 911 from the 1980s? That might appreciate. See the difference? Collectibles can be a legitimate asset class—but only if you buy the right thing at the right price.
Wine, watches, handbags, even Pokémon cards (yes, really) have outperformed the S&P 500 over certain periods. But they come with storage costs, insurance, and illiquidity. Your allocation to these should be like your love life: passionate, but only a small part of your whole story.
Pro tip: If you buy a multi-million-dollar painting, don’t hang it over a fireplace. The heat and smoke will destroy its value. Instead, insulate it in a climate-controlled vault—and buy a high-quality print for your living room. Your guests will never know.
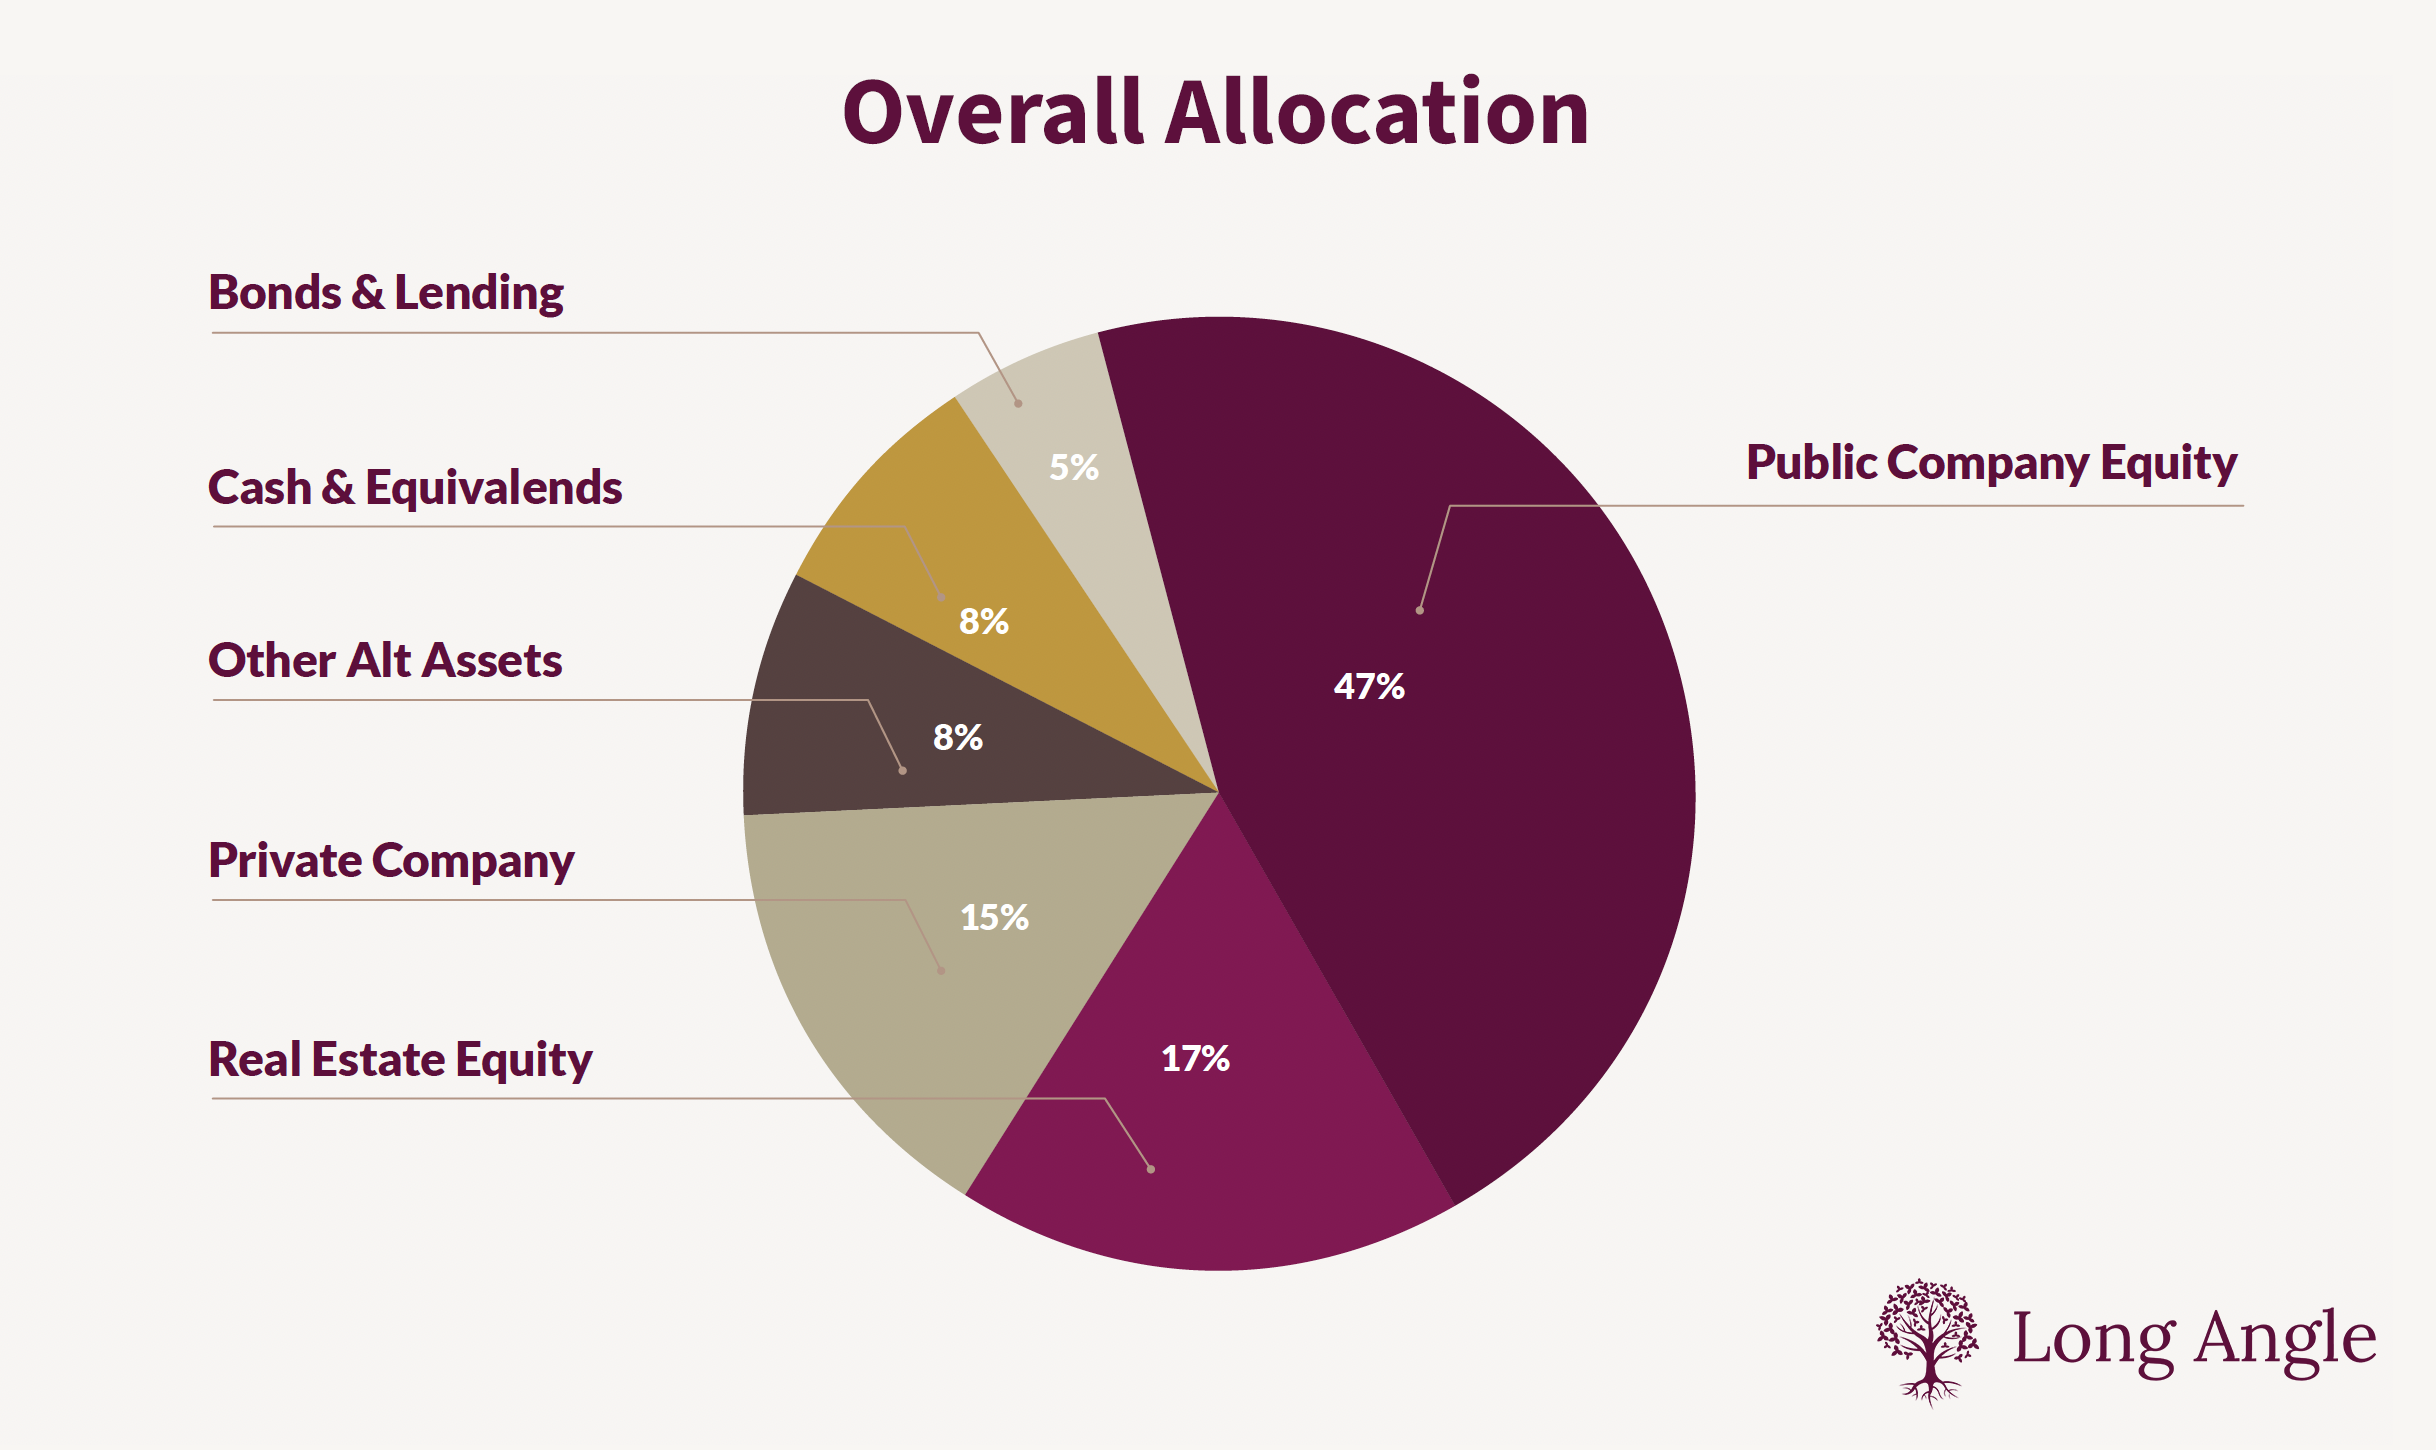 High-Net-Worth Asset Allocation Study - Long Angle
The Final Two Tools: Time and Rebalancing
Most HNWIs rebalance quarterly, not annually. When stocks surge, you sell a little. When bonds drop, you buy. It’s boring, but it works. Think of it as weeding your garden before the weeds take over. A good rule: if an asset grows more than 5% over your target allocation, trim it.
Also, time is your most underrated asset. A 25-year-old with $5 million can take wild risks. A 65-year-old with $50 million needs to preserve capital for three decades of travel, healthcare, and grandkids. Your allocation is a function of your timeline, not your ego.
Fun fact from behavioral finance: The typical HNWI overestimates their risk tolerance by about 20%. We all think we’re cool-headed until the market drops 30% in a week. The solution? Set your allocation when the market is calm, and stick to it with the discipline of a monk.
Connecting to Daily Life
So, what does this mean for your Tuesday morning? It means you don’t panic when your tech heavyweights take a hit. It means your private equity is a long, slow burn, not a sprint. And it means you can enjoy that avocado toast without guilt, because your allocation is doing the heavy lifting.
Asset allocation isn’t about being perfect. It’s about being appropriate—for your wealth, your dreams, and your very human desire for a good night’s sleep. After all, the best portfolio is the one that lets you leave your phone in another room and actually watch the sunset. Now that’s a return on investment.
