Average American Net Worth At Retirement

Let’s be honest—most of us don’t wake up thinking about net worth. We think about coffee, traffic, and whether we remembered to pay the electric bill. But every now and then,...
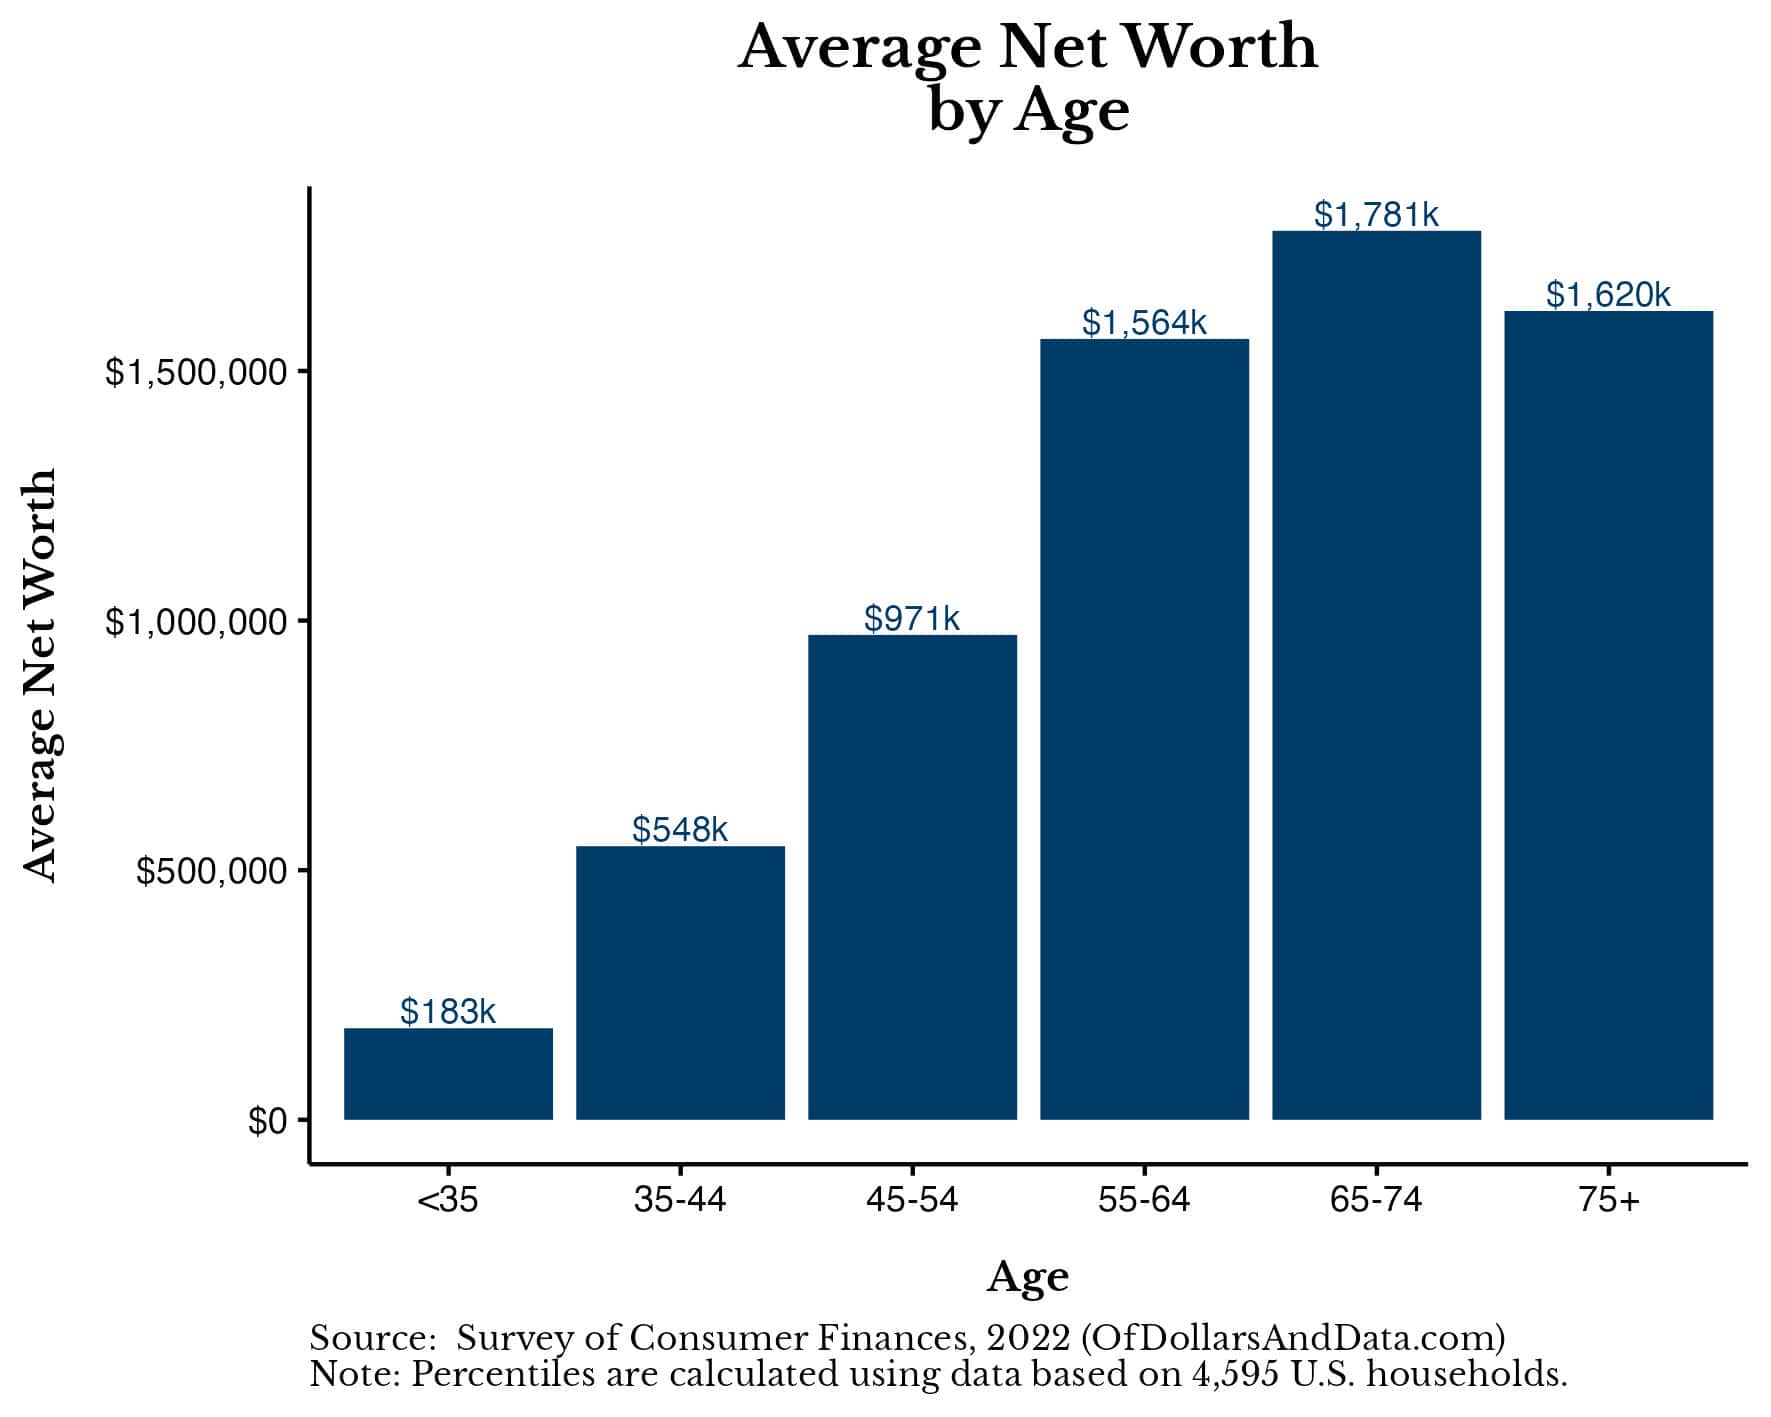
Let’s be honest—most of us don’t wake up thinking about net worth. We think about coffee, traffic, and whether we remembered to pay the electric bill. But every now and then, a number pops up online that makes you pause mid-sip: the average net worth of a retiree. And suddenly, you’re wondering if your 401(k) is a joke or a lifeline.
Here’s the first secret: the average number can be really scary—or really misleading. According to recent data, the average American household nearing retirement (ages 65-74) has a net worth around $1.2 million. If you just gulped, you’re not alone. But hold on—that’s the average, not the normal.
The median net worth for that same age group is closer to $200,000. That’s the number most of us actually live with. Think of it like this: if Jeff Bezos walks into a bar, the average net worth of everyone inside suddenly looks fabulous—but you’re still just you, sipping a soda and wondering how to pay for new tires.
Must Read
Why should you care?
Because retirement isn’t a destination you stumble into—it’s a math problem you solve one paycheck at a time. Caring about net worth early is like checking your gas gauge before a long road trip. You don’t want to be that person coasting on fumes, praying for a downhill stretch.
Picture your neighbor, Karen. She retired at 65, sold her house, and now spends six months a year in an RV. She’s not a millionaire—she just planned okay. Meanwhile, your uncle Bob worked until 72 because his idea of retirement savings was a coffee can full of quarters. Bob’s not having a great time.
The difference between Karen and Bob? Not luck. It’s knowing that retirement net worth is about cash flow, not a magic number. You don’t need a yacht. You need enough to cover your hot water, your Netflix, and maybe a cheap vacation every two years.
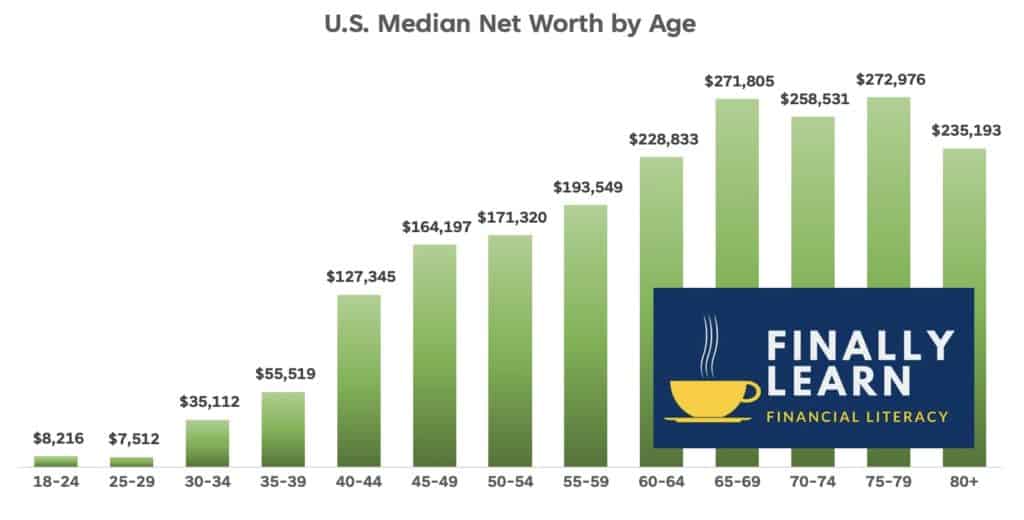 Average Net Worth by Age 50 - Finally Learn
The real numbers (without the panic)
Let’s get practical. The typical retiree spends about $50,000 a year (including healthcare). If you have Social Security kicking in around $20,000 annually, you need to make up the other $30,000 from your savings. That means you want a nest egg that can safely spin off $30,000 a year—roughly $750,000, if you use the traditional 4% rule.
But here’s the thing: most people don’t hit that number. And they’re still fine. They downsize. They move to cheaper towns. They pick up a part-time job at a bookstore because they like talking to people. The key is knowing what your number is, not the average person’s.
Think of it like ordering pizza. The average pizza might have pepperoni and extra cheese, but you might just want plain cheese with pineapple. Your retirement net worth is your own pizza. Don’t compare your slice to someone else’s table.
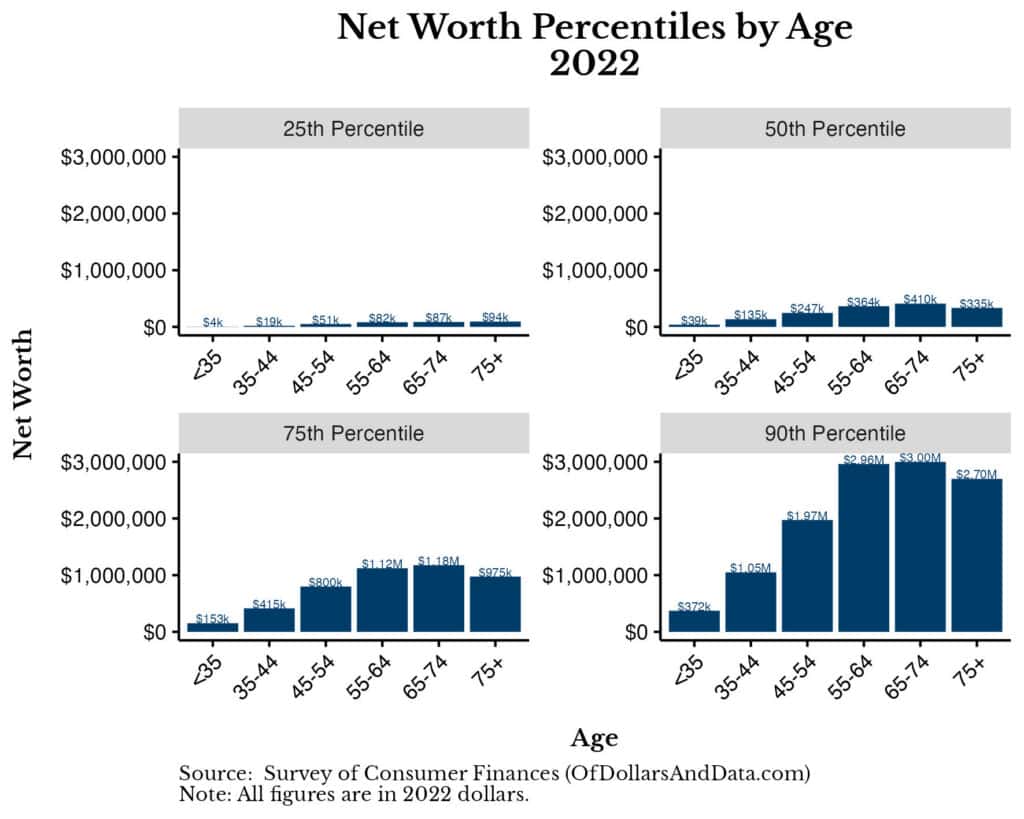 What is the Average Net Worth by Age?
Small steps that make you smile later
You don’t need to become a finance guru. You just need a few habits. Start with this: every time you get a raise, put half of it into your retirement account. Not all of it—go buy a nice dinner. But half? That’s future you doing a happy dance.
Another trick: when you pay off a car loan, keep paying that monthly amount—but into savings. It feels weird at first, like brushing your teeth with your non-dominant hand. But after five years, you’ll have a fat little cushion that whispers “thank you” every time you look at it.
Don’t forget your home equity. Most retirees’ net worth is tied up in their house. That’s fine—it’s like having a secret savings account under your floorboards. If you don’t plan to move, it’s just a safety net. If you do downsize, it’s a windfall for travel or grandkid spoiling.
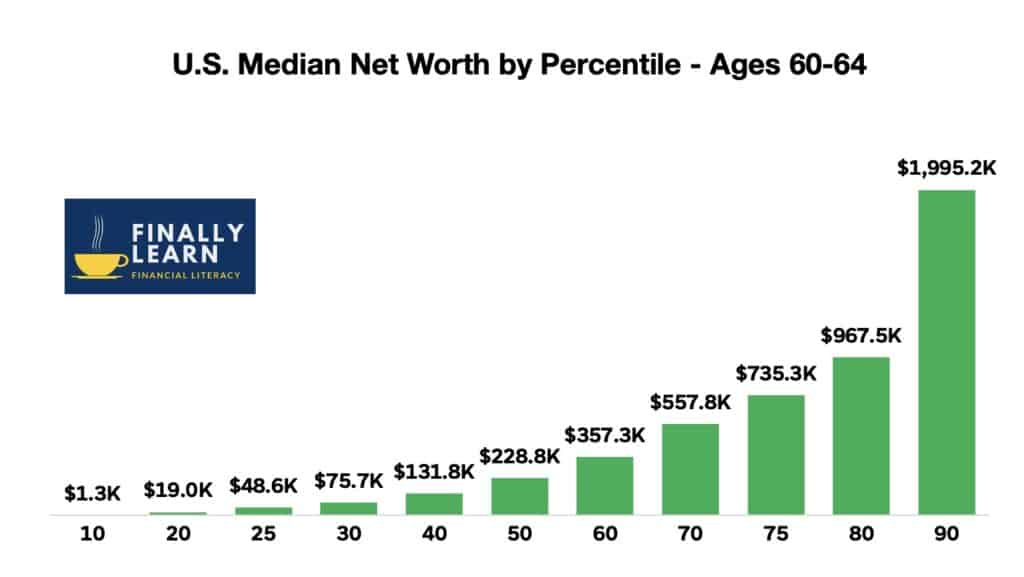 Median Net Worth By Age 2025 – Net Worth To Be Richer – EMXVRB
The smiling truth
The average American retiree’s net worth is not a report card. It’s a snapshot of choices, luck, and a lot of small decisions. Some people retire with millions—and still feel broke because they compare themselves to richer friends. Others retire with $200,000 and a paid-off house, and they’re the happiest folks at the senior center.
Here’s a little story. My aunt Diane retired with exactly $180,000 in the bank. She moved to a small town, bought a used Prius, and now spends her days gardening and hosting book club. She says, “I’m richer than most of my friends—because I don’t owe anyone a dime.” She’s not lying. Net worth is just a number. Freedom is the real asset.
So what’s the takeaway? Don’t stare at the average number like it’s a monster under your bed. Look at your own life. If you’re saving something—anything—and you’re not drowning in debt, you’re already ahead of the average American who never thinks about it at all.
Start small. Set a goal. And next time someone brings up “average net worth at retirement,” just smile and say, “I’m working on my own average.” Because your retirement story is the only one that matters. And with a little planning, it can be a really good one.
