Average Household Net Worth United States

So, last week at a backyard barbecue, my neighbor Dave—the one with the Tesla and the perfectly manicured lawn—casually mentioned he was “house poor” after finally buying his...
So, last week at a backyard barbecue, my neighbor Dave—the one with the Tesla and the perfectly manicured lawn—casually mentioned he was “house poor” after finally buying his dream home. I nodded sympathetically while secretly wondering if his actual net worth was enough to cover my emergency dental fund. (Spoiler: it definitely was.) That little chat got me thinking: what does the average household net worth in the United States actually look like? Turns out, the numbers are wildly different from what you’d guess from scrolling through Instagram.
Let’s start with the headline figure. According to the Federal Reserve’s most recent data (2023), the average U.S. household net worth sits at a dizzying $1,059,470. Yes, you read that right—over a million bucks. But before you start comparing yourself to Dave or your cousin with the crypto portfolio, take a breath. Averages are the liars of statistics, especially when it comes to wealth.
The median household net worth tells a far more relatable story: just $192,900. That’s the sweet spot where half of households are above, half below. Why the gap? Because billionaires like Elon Musk and Warren Buffett really skew the average. The top 1% holds roughly 30% of all U.S. household wealth—so when you hear “average millionaire,” remember, that average is being pulled up by people who could buy a small island.
Must Read
What’s Actually in That Net Worth?
When we talk net worth, we mean assets minus liabilities. Your home equity, retirement accounts, cash, and even that Beanie Baby collection (if it ever becomes valuable) count. But the biggest driver for most families? Homeownership. The median net worth of homeowners is a staggering $396,200, compared to just $10,400 for renters. That’s not a typo—renters’ median net worth is 38 times smaller.
Think about that for a second. If you’re renting, even a well-paying job might still leave you with a net worth that feels like pocket change. On the flip side, if you bought a house in 2020 with a 3% mortgage, congratulations—you’re probably sitting on a goldmine of equity, at least on paper. (But hey, it’s not liquid, right? Tell that to your bank when you try to buy groceries with your home’s Zestimate.)
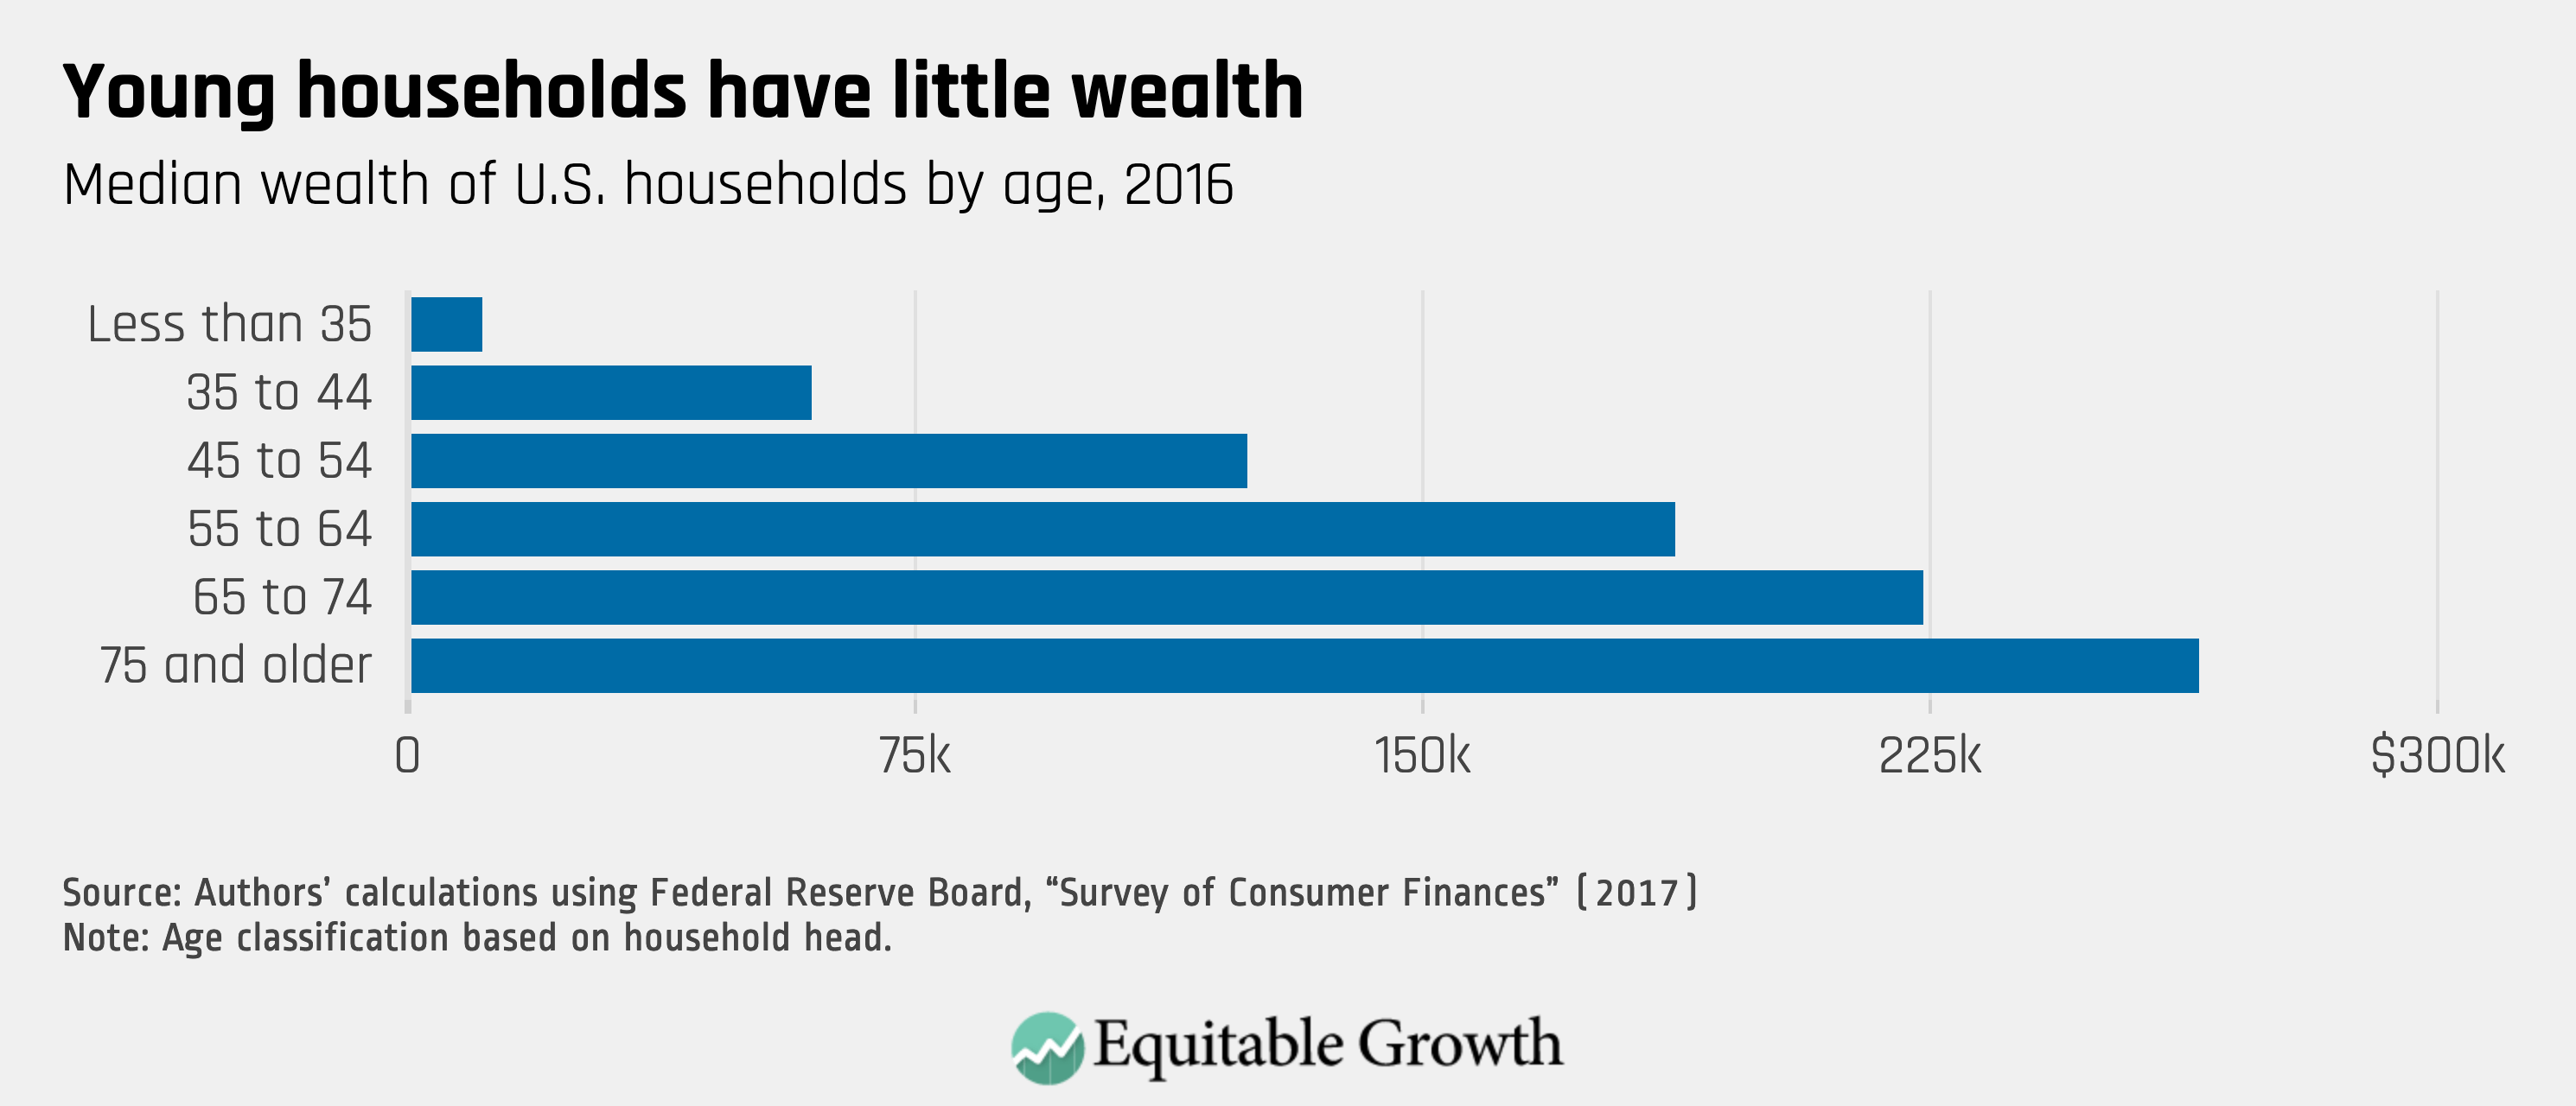 The distribution of wealth in the United States and implications for a
The Age Factor (AKA, Time Is Money)
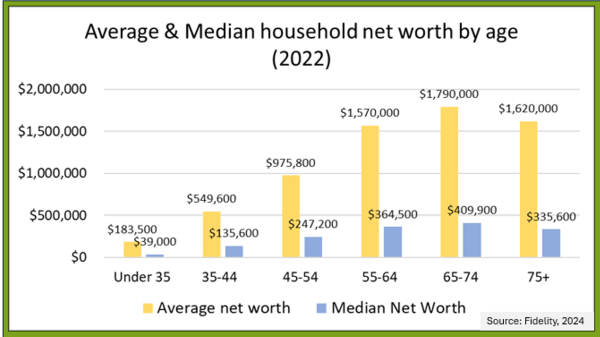
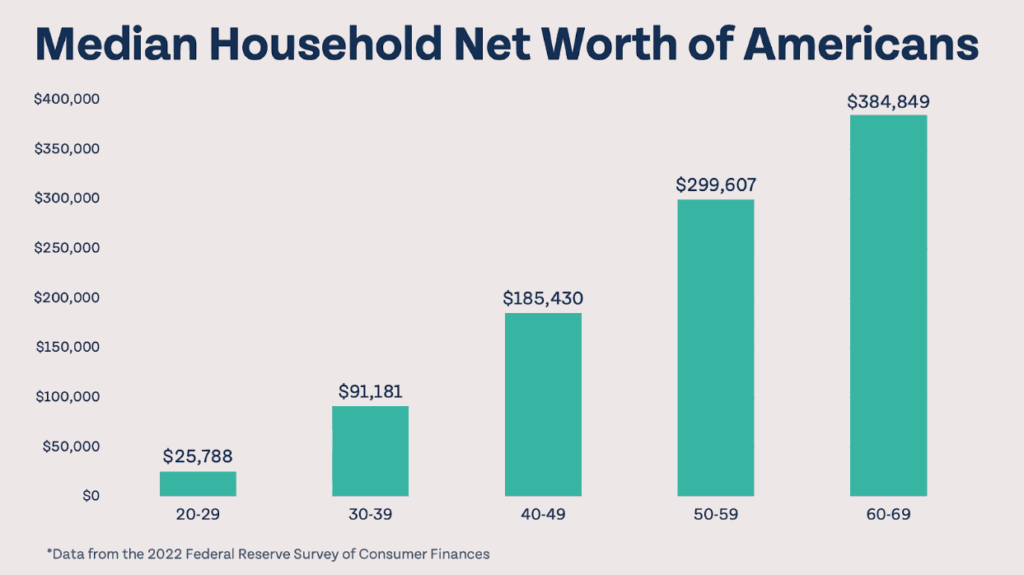
Here’s where the irony really kicks in. Your net worth isn’t just about how much you earn—it’s about how long you’ve been alive. Households headed by someone under 35 have a median net worth of about $39,000. That’s basically a used car and a decent emergency fund. But by the time you hit ages 65–74, that median jumps to $410,000.
Why? Compounding returns, paid-off homes, and decades of saving. So, if you’re in your twenties and feel like a financial failure, remember: you’re supposed to be broke. The system wants you to feel impatient, but the real game is waiting. (Unless you’re a tech founder—then ignore all of this and go buy a jet.)
 What is the Average Net Worth by Age?
The Sneaky Divide: Education and Race
Let’s get a little uncomfortable for a second. Net worth isn’t a level playing field—it’s a class and race story. A family with a college degree has a median net worth of $472,000, compared to just $79,000 for a high school diploma. That gap is partly about earning power, but also about inheritance and financial safety nets.
The racial wealth gap is even starker. White households have a median net worth of $285,000, while Black households sit at $44,900 and Hispanic households at $61,600. These numbers aren’t just about individual effort; they’re the echo of centuries of policies—redlining, unequal access to education, and wealth-building opportunities that were systematically denied. (And no, a single “work harder” meme isn’t going to fix that.)
 Income Levels America Chart U.S. Incomes Stabilize For First Time
So, What’s the Takeaway?
First, don’t freak out if your net worth looks puny compared to the “average.” You’re probably not a millionaire, and that’s fine—most millionaires are older, white, and homeowners. The real story is that household net worth in the U.S. is deeply uneven and tied to factors you can’t always control, like where you were born or whether you got a down payment from your parents.
Second, don’t believe the hype. The “American Dream” of universal wealth is more of a mirage for many. But here’s the ironic upside: if you can focus on saving consistently, avoiding debt, and maybe buying a home when you’re ready (not when Instagram tells you to), you’ll likely end up in the upper half. And honestly, the median is $192,900—which, while not yacht money, is a solid foundation for peace of mind.
So, what about Dave from the barbecue? Turns out, after paying his mortgage, his net worth is around $300,000—mostly tied up in that house. He’s proud but anxious. Me? I’m over here with my $45,000 in retirement savings and a Honda Civic. We’re both average in our own ways. And you? Well, now you know the numbers—so go check your bank account, grab a coffee, and maybe ignore your neighbor’s Tesla. The real wealth might just be knowing where you stand.
