Average Net Worth American By Age

Let’s be honest: checking your bank balance after a night out feels like opening a mystery box. You hope for treasure, but you often find a few sad receipts and a vague sense...
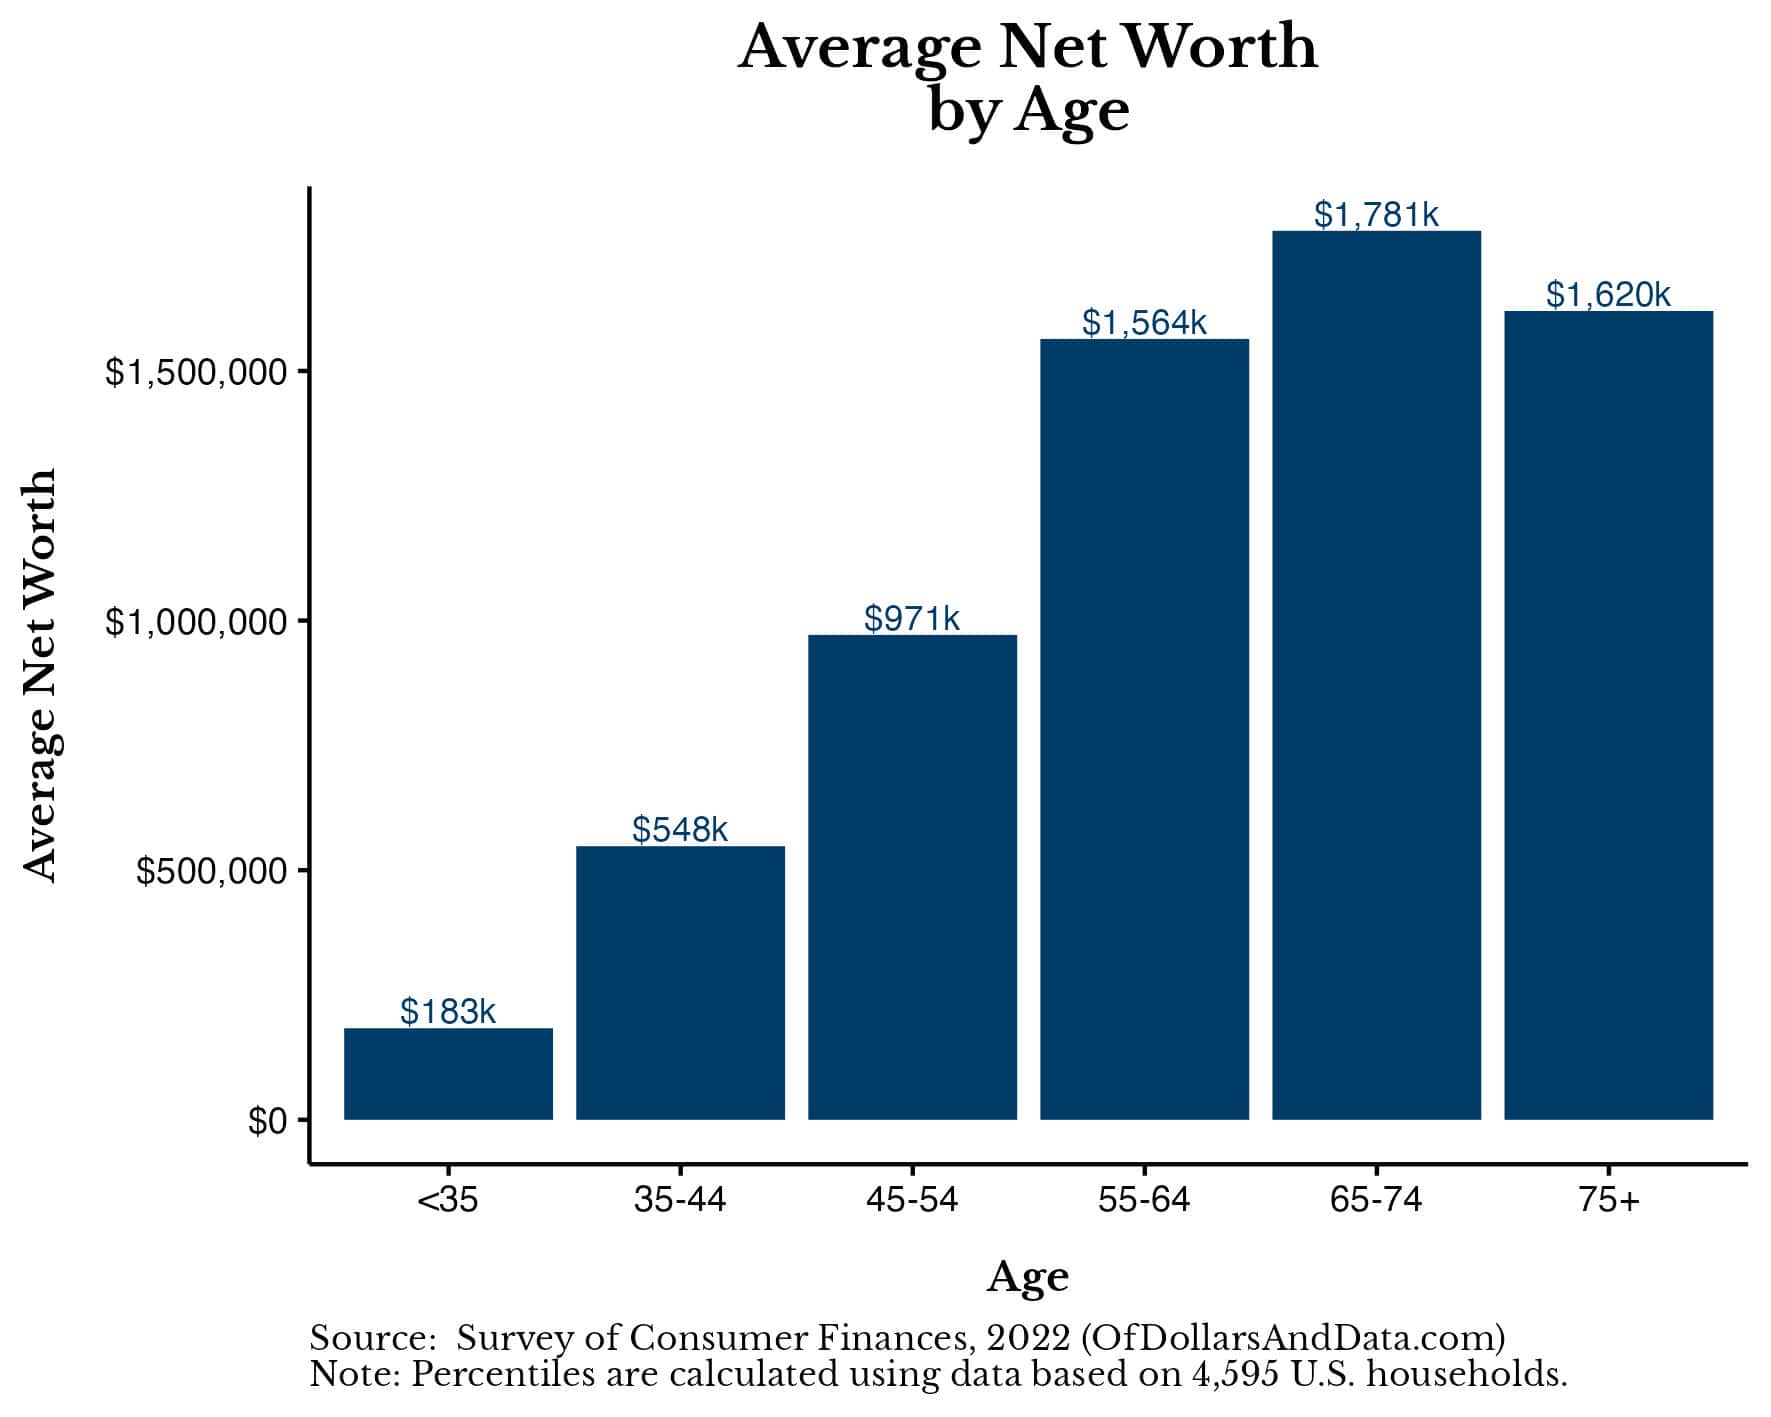
Let’s be honest: checking your bank balance after a night out feels like opening a mystery box. You hope for treasure, but you often find a few sad receipts and a vague sense of regret. The same anxiety creeps in when we talk about net worth—that scary number that measures everything you own minus everything you owe. But what does a “normal” American actually have at 25, 40, or 65? Let’s rip the band-aid off and look at the data with a cocktail in hand.
The Federal Reserve’s latest Survey of Consumer Finances gives us the receipts. Spoiler: the numbers are jarring, but they also tell a story of patience, luck, and a little bit of hustle. The median net worth for an American under 35 hovers around $14,000. Yes, that’s not a down payment on a mansion; it’s a used Honda Civic plus a 401(k) with $500 in it. For the 35-44 crowd, the median jumps to $91,300—mostly home equity and a growing retirement account.
Meanwhile, the 45-54 age group sees a leap to $168,600, often fueled by peak earning years and a paid-off car note. And the 55-64 bracket? That’s where the magic happens, with a median of $225,000. But here’s the fun fact: the average net worth in that same group is over $1.5 million. That gap? It’s the wealth gap in action—some people are toting yachts while others are just happy to have a paid-off roof.
Must Read
The Context of Chaos
Before you spiral, remember this: these numbers are national medians. They don’t account for your San Francisco rent or your cousin’s trust fund. The average net worth is dragged up by the top 10%, who hold 70% of all wealth. So if you’re eating ramen while your neighbor buys a Tesla, don’t panic—you’re likely just normal.
A cultural reference for the road: remember that scene in The Big Short where everyone ignores the housing bubble? Your net worth can feel like that—a fragile bubble of student loans and a 401(k) that’s seen better days. But unlike a mortgage-backed security, you can rebuild. The key is knowing that age isn’t a race; it’s a slow, boring marathon.
Practical Tips for the Grind
Let’s get tactical. If you’re under 35, your superpower is time. Even $50 a month into an index fund at 25 will turn into $50,000 by 65, thanks to compound interest—Einstein’s eighth wonder. Automate that savings, and pretend it doesn’t exist. It’s like hiding a snack from your future self.
 Average American Net Worth: How Does Yours Compare? - Plan to Rise Above®
For the 35-44 crowd, focus on debt killing and home equity. That credit card balance at 18% interest is an emergency. Pay it down before you invest more. And don’t ignore your 401(k) match—that’s free money. It’s like finding a twenty in your winter coat, but bigger.
In your 45s and 50s, the name of the game is protection. Get an emergency fund of six months’ expenses. Diversify your investments—don’t put all your cash in crypto just because your nephew said it’s mooning. A healthy mix of stocks, bonds, and maybe a rental property can cushion a market crash.
Fun Facts to Lighten the Load
Did you know that the median net worth for a 65+ American is $266,000? But the average is $1.8 million. That’s because some grandpas own beach houses while others are couponing at Dollar General. Also, a 2023 study found that 1 in 5 Americans have negative net worth—meaning they owe more than they own. You’re not alone if you’re in the red; it’s just a starting line.
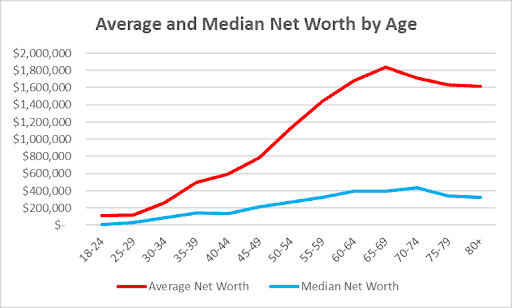 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
Fun fact: Gen Z is actually saving at a higher rate than millennials did at their age. Blame TikTok financial influencers or just a healthy fear of inflation. Meanwhile, boomers hold 53% of all U.S. wealth—a reminder that time, not genius, builds a nest egg.
The Modern Reality Check
Let’s address the elephant in the room: student loans. For many 30-somethings, that debt load crushes net worth. The median student debt is around $30,000, and it’s a silent anchor. If you’re working an income-driven repayment plan, you’re playing the long game—and that’s okay. The key is to keep investing even a small amount, because the market eventually grows.
What about the “fun” costs? A 2024 survey found that Americans spend an average of $2,000 a year on streaming services, takeout, and impulse Amazon buys. Cutting that in half and putting it into a Roth IRA could add $100,000 to your net worth by retirement. That’s a lot of avocados you can still buy.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
And for the love of all that is holy, don’t compare your net worth to your Instagram feed. Your friend’s “bought a house at 28” story might come with a massive parent down payment. The only person you’re racing is your past self, and even then, it’s a gentle jog.
A Short Reflection for Your Daily Run
Here’s the thing: net worth is a snapshot, not a life sentence. It changes with every paycheck, every market dip, and every time you choose to cook at home instead of ordering sushi. The average American at 40 has $100,000, but that number is a mix of luck, sacrifice, and a little bit of credit card churning.
So, next time you’re scrolling your banking app after a long Tuesday, remember: the goal isn’t to be a millionaire by 30. It’s to build a life where you can sleep soundly, buy the occasional good coffee, and maybe—just maybe—retire before your knees give out. Your net worth is just a number. Your worth is the story you’re writing every day.
And if nothing else, at least you’re not in negative net worth on Love Is Blind. That’s a win.
