Average Net Worth At Retirement Usa

Have you ever caught yourself wondering, “How am I doing compared to everyone else?” When it comes to retirement savings, that question pops up constantly. It’s totally normal...
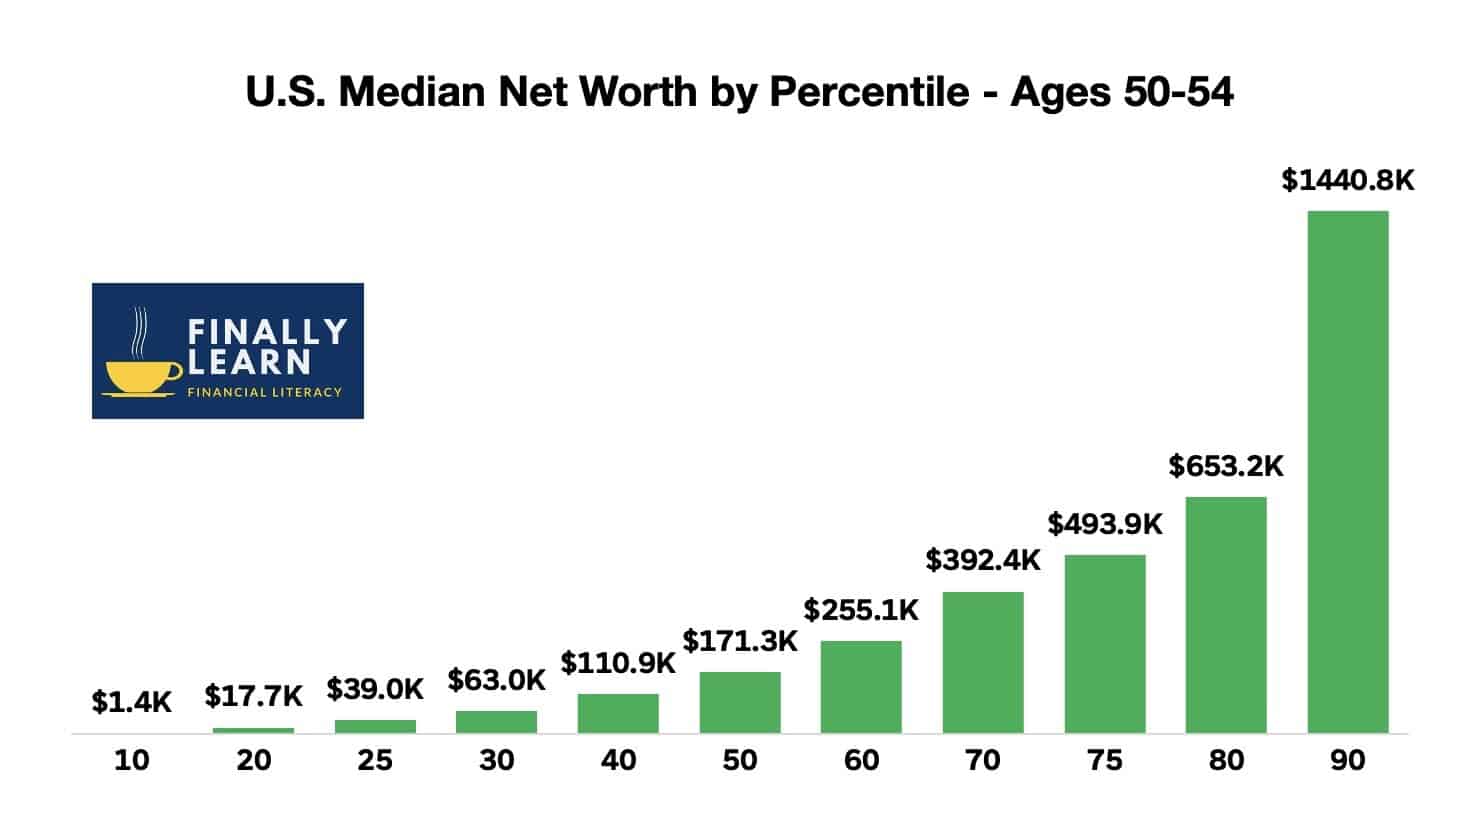
Have you ever caught yourself wondering, “How am I doing compared to everyone else?” When it comes to retirement savings, that question pops up constantly. It’s totally normal to peek over the fence and see what the “average” American has stashed away. Let’s dive into the numbers, but don’t worry—we’ll keep it chill.
The Big Number: What’s the Average Net Worth?
For Americans between 65 and 74, the average net worth at retirement is about $1.2 million. Whoa, right? That sounds like a lot of cash. But hold up—the median net worth for that same age group is way lower, around $410,000.
Why the huge gap? It’s all about extremes. A small group of super-high earners pulls that average way up. So, most retirees are actually sitting closer to that median number. Think of it like a party where one friend brings caviar and the rest bring pizza rolls.
Must Read
What Does “Net Worth” Even Mean, Anyway?
Let’s break it down simply: net worth is everything you own minus everything you owe. Your house, your car, your 401(k), and your savings count for you. Your mortgage, credit card debt, and student loans count against you.
So if your house is worth $300,000 but you still owe $200,000 on the mortgage, that’s only $100,000 toward your net worth. It’s not just about how much you’ve saved; it’s about how much you’ve cleared from debt. Pretty interesting, right?
A Fun Comparison: Retirees vs. Everything Else
Let’s make this relatable. The median net worth of a retiree ($410,000) is about the same as the cost of 32 brand-new Honda Civics. Imagine parking all those cars in your driveway—that’s your retirement stash!
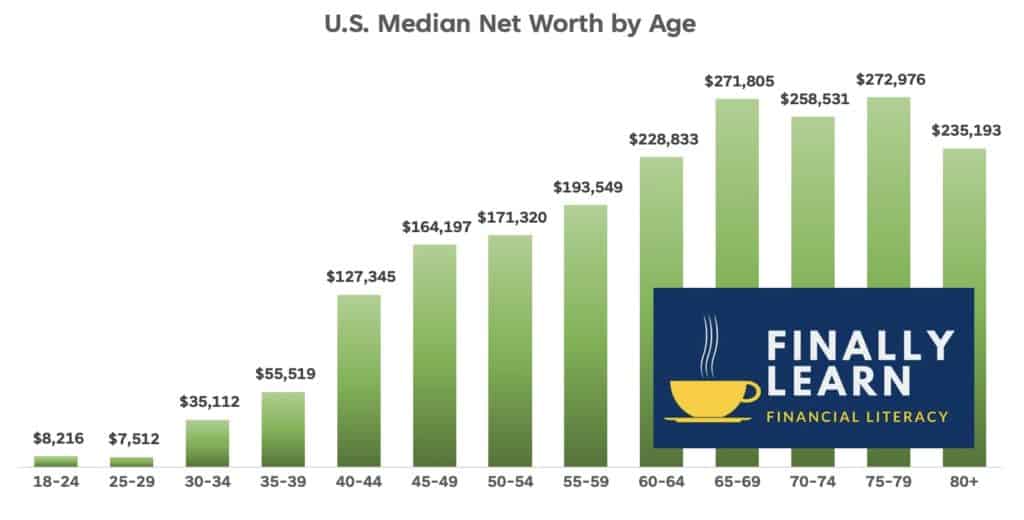 Average Net Worth by Age 50 - Finally Learn
Or picture this: that average net worth of $1.2 million could buy you 24,000 all-you-can-eat sushi dinners. That’s enough tuna rolls to last you a lifetime—literally. It’s wild how numbers translate into real-world stuff.
The Elephant in the Room: Debt
Here’s the buzzkill part: retirement debt is rising. In 2022, about 30% of households headed by someone 65 or older still had mortgage debt. That’s up from just 22% in 2000. Student loans are also creeping into retirement.
Why does this matter? Because debt eats into your net worth like a hungry raccoon at a campsite. The less you owe, the more your savings can actually work for you. It’s a simple math game, but it’s a tough one to win.
 What is the Average Net Worth by Age?
So, Are You Behind or Ahead?
Here’s the honest truth: comparing yourself to averages is a trap. If you have $250,000 saved at age 65, you might feel behind compared to that $410,000 median. But if you own your home outright and have zero debt, you’re in a fantastic spot.
Think about it—retirement isn’t just a pile of cash. It’s about lifestyle. Do you want to travel the world or just relax in a garden? Your number changes based on your dreams. The average is just a statistic, not your personal finish line.
A Little Perspective: Your Savings vs. a Cup of Coffee
Let’s get really chill for a second. If you saved just $5 a day from age 25 to 65, you’d have roughly $365,000 (assuming a 7% return). That’s almost the median net worth for retirees! All from skipping one latte or burrito each day.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
Meanwhile, that $1.2 million average? It’s like saving $16 a day over 40 years. Feels doable if you think about it, but life has a funny way of throwing curveballs. The point is: consistent small actions add up to big things.
The Coolest Part: You Have Options
Here’s the fun twist: retirement isn’t a one-size-fits-all event. Some people work part-time because they love it. Others downsize to a tiny house and live on $30,000 a year. Your net worth is just one number in a bigger story.
So, whether you’re at $100,000 or $1 million, the real question is: Can you live the life you want? If yes, then you’re rich in the ways that count. And if not? Well, you’ve got time to tweak the plan. The average is just a curiosity, not a command.
So go ahead, check your numbers—but don’t stress. You’re doing better than you think, and the best part of retirement is still unwritten. Now, go enjoy that sushi dinner.
