Average Net Worth By Age In America

Let’s be honest: talking about money can feel like trying to explain TikTok to your dad—awkward, confusing, and a little bit cringe. But here’s the thing: knowing where you st...
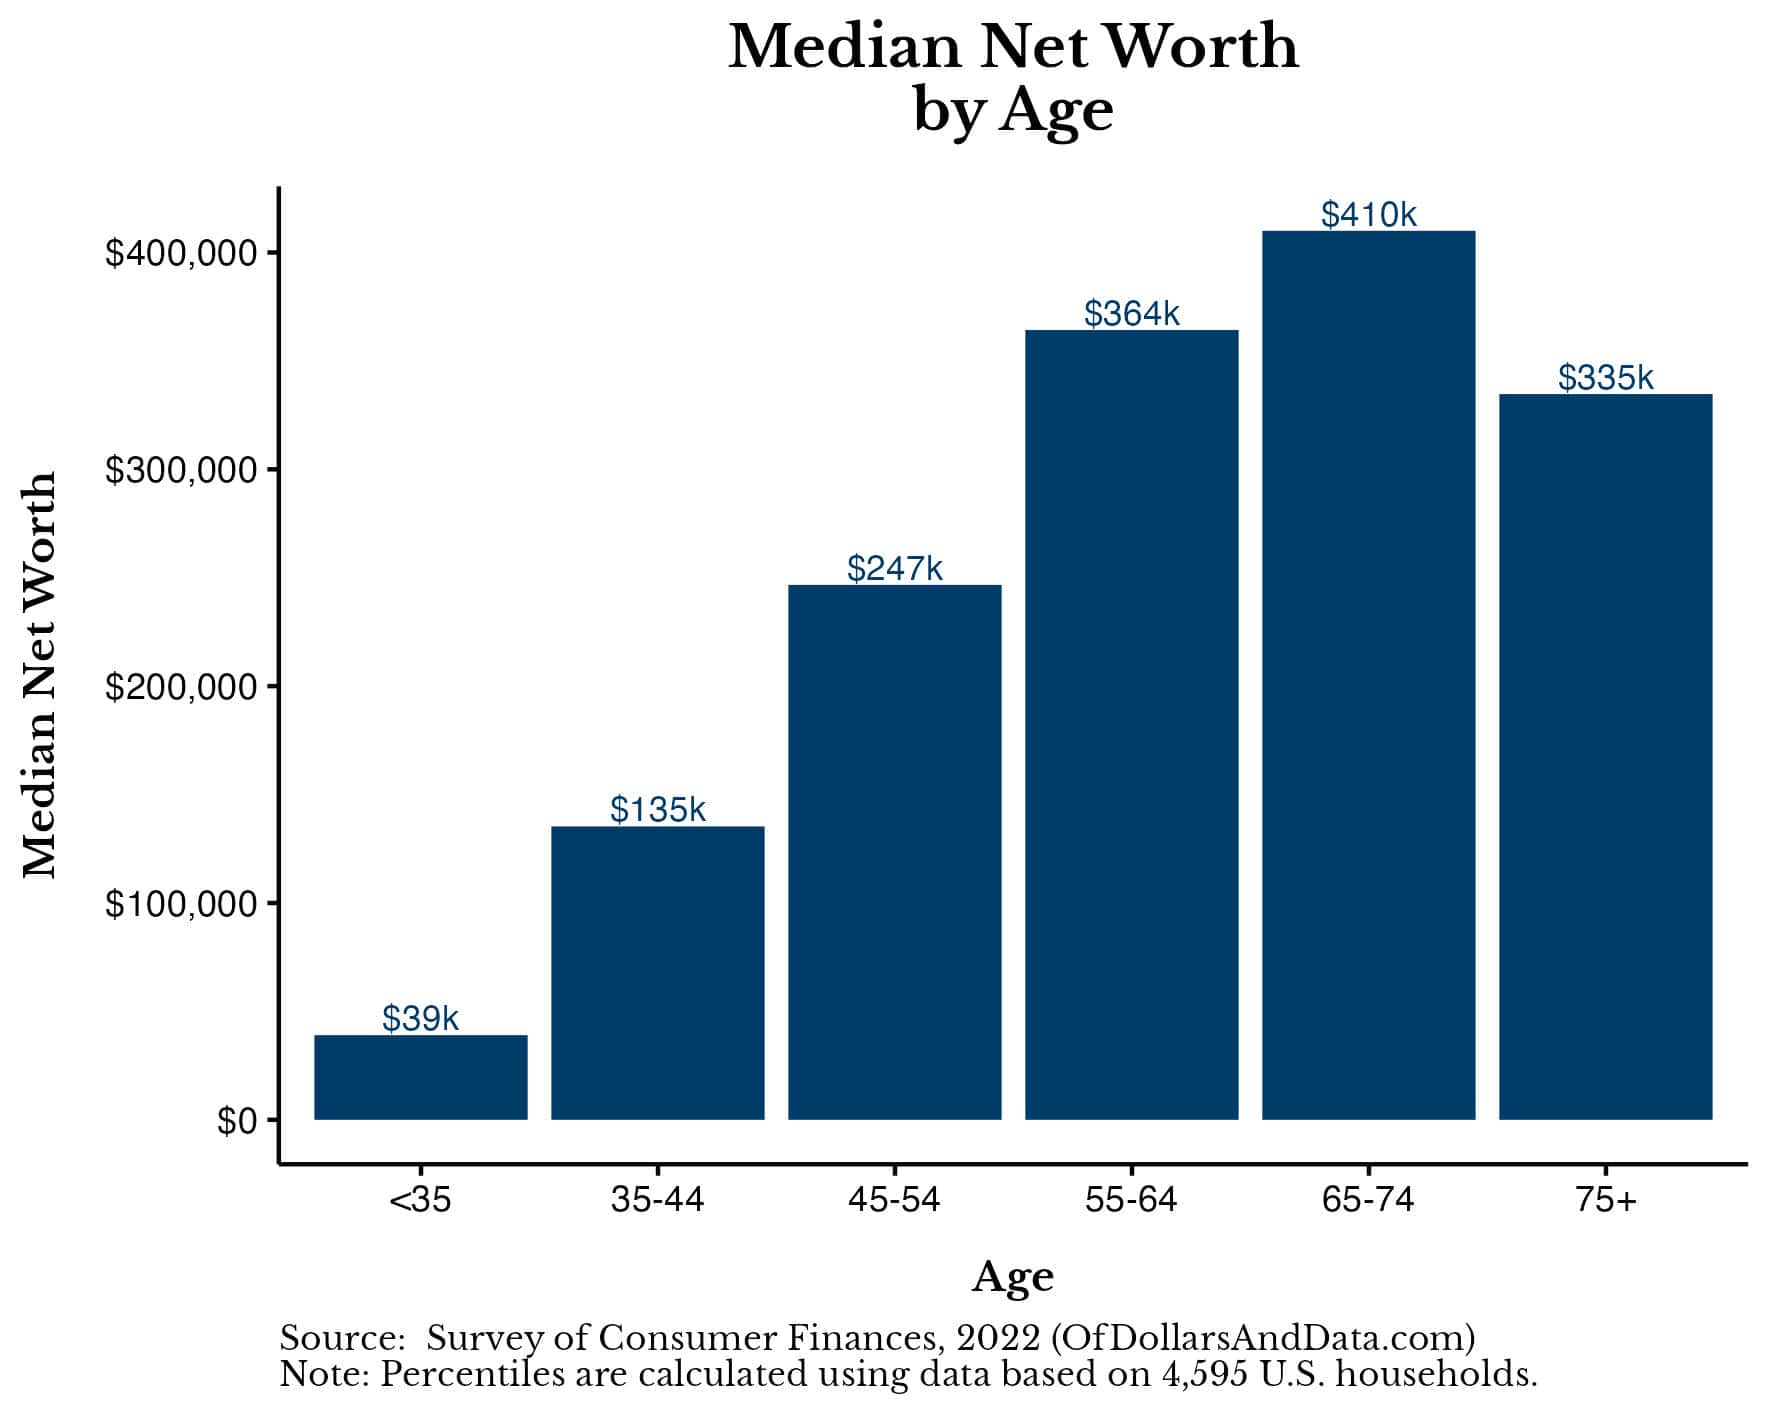
Let’s be honest: talking about money can feel like trying to explain TikTok to your dad—awkward, confusing, and a little bit cringe. But here’s the thing: knowing where you stand financially is the first step to actually feeling good about your wallet. So grab your iced coffee, put down the doomscroll, and let’s unpack the average net worth by age in America—no judgment, just facts and a little bit of swagger.
First, a quick reality check. Your net worth is simply what you own minus what you owe—your house, your savings, your student loans, and that vintage guitar you swear is an investment. The Federal Reserve tracks this data, and it’s surprisingly revealing. Spoiler: most people are not living like a Silicon Valley founder, and that’s totally fine.
For those under 35, the average net worth hovers around $76,000, but the median is a much humbler $14,000. Why the gap? Because a handful of tech bros and trust-fund babies skew the numbers. If you’re in your twenties or early thirties and your savings account looks more like a “rent fund” than a retirement plan, you are normal.
Must Read
The 35-to-44 Sweet Spot
By the time you hit your late thirties, the average net worth jumps to about $436,000—but again, the median is only $91,000. This is the decade where home equity starts to work its quiet magic. You’ve probably traded late-night tacos for a mortgage, and that’s not a bad trade-off.
Here’s the cultural kicker: this is also the age where your friends start casually dropping phrases like “my 401(k) is crushing it” while you’re still figuring out if you should invest in that new gaming console. Don’t panic. Compound interest is a slow dancer, not a sprinter.
Fun fact: the average American’s net worth peaks between ages 65 and 74, reaching a median of $200,000. That’s a lot of retirement cruises and golf fees. But the journey there is less about hitting a magic number and more about steady habits—like actually checking your bank app without holding your breath.
 Average Net Worth By Age Chart
Practical Tips to Level Up Your Numbers
First, automate your savings like you automate your Netflix subscription. Set up a direct deposit into a high-yield savings account or a Roth IRA, and pretend that money doesn’t exist. Out of sight, out of mind is a real financial hack.
Second, embrace the power of lifestyle inflation—but in reverse. When you get a raise, don’t immediately upgrade your apartment or buy a new car. Instead, funnel that extra cash into investments. It’s not sexy, but it works.
Third, stop comparing yourself to that influencer flying private. The average net worth data is a mirror, not a spotlight. You’re not supposed to have five rental properties by age thirty. You’re supposed to be trying, and that’s what counts.
 What is the Average Net Worth by Age?
Where the Money Lives (and Dies)
Here’s a wild truth: nearly 30% of Americans have less than $1,000 in savings. That’s not a dig—it’s a wake-up call. The biggest wealth builders are homeownership and consistent investing, but those are privileges, not birthrights. If you’re renting and paying off debt, you’re still building a foundation.
Fun fact: the most successful investors are often the boring ones. Think index funds, not crypto memes. Warren Buffett himself says the best strategy is to “buy a low-cost index fund and work a regular job.” He also eats a lot of McDonald’s, so take that as you will.
Another fun fact: Generation Z is actually starting to save earlier than millennials did, thanks to apps like Acorns and the sheer terror of retirement. They’re averaging about $7,000 in net worth by age 25—which, for a generation raised on economic chaos, is honestly impressive.
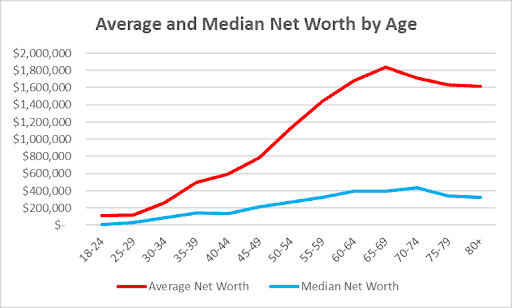 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
The Reflection That Sticks
At the end of the day, net worth is a number on a spreadsheet, not a measurement of your worth as a human. You don’t need to be a millionaire to be happy—but you also don’t need to be broke to be in denial. The game is simple: spend less, save more, repeat.
So tonight, when you’re scrolling your phone and see a friend’s vacation photo from Bali, remember: that trip might have been on credit. And your quiet 401(k) is still growing, even while you sleep. Slow and steady is the real American dream—it just doesn’t sell as many ads.
Now go check your banking app. Not because you have to, but because you can. And maybe, just maybe, give yourself a little credit for showing up. Your future self will thank you—and they’ll probably have better coffee.
