Average Net Worth Of Retirees In Us

So, you’re wondering about the average net worth of retirees in the US, huh? Maybe you’re dreaming of early retirement, or maybe you’re just trying to figure out if your 401(k...

So, you’re wondering about the average net worth of retirees in the US, huh? Maybe you’re dreaming of early retirement, or maybe you’re just trying to figure out if your 401(k) is secretly a sarcophagus for your hopes and dreams. Either way, grab a coffee—or a glass of wine, no judgment—and let’s dive into some numbers that probably won’t make you cry. Probably.
The Big, Scary Number (Don’t Panic Yet)
According to the latest data from the Federal Reserve’s Survey of Consumer Finances, the average net worth for retirees aged 65 to 74 is roughly $1.2 million. Whoa, right? That sounds like a lot, until you remember that “average” includes the one person who owns three yachts and a small island in the Caribbean.
Let’s add some spice: the median net worth for that same group is about $410,000. Yeah, the median—the true middle-of-the-road number—is way lower. That’s because a few super-rich retirees pull the average up like they’re hoisting a giant, golden balloon.
Must Read
So, if you’re sitting on $410,000, you’re right in the middle of the pack. Congrats! You’re the median turtle in a race full of hares and a few snails with jetpacks.
Breaking It Down: What’s Actually in That Nest Egg?
Your net worth isn’t just cash under the mattress—though that’s a valid strategy if you’re a raccoon. It includes home equity, investment accounts, pensions, and Social Security (the last one being the government’s way of saying, “We still love you, but please don’t ask for more”).
For the typical retiree, home equity makes up a huge chunk—often 30% to 50% of their net worth. That means a lot of retirees are “house rich, cash poor.” They own a lovely paid-off home, but they’re eating ramen and clipping coupons for dental floss.
And here’s a fun twist: Social Security is the backbone for many. It replaces about 40% of pre-retirement income for the average worker. Meanwhile, pensions are becoming as rare as a unicorn riding a Segway—only about 15% of private-sector workers have one now.
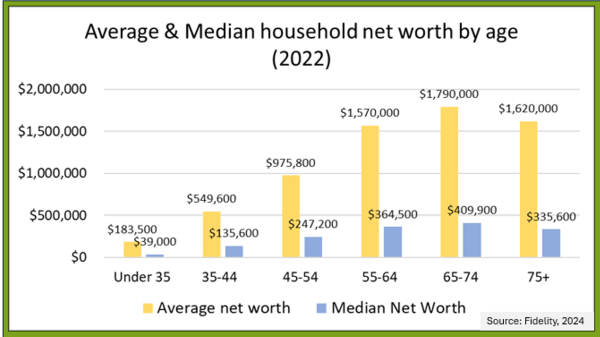 Chart and Comment: Average and Median Household Net Worth by Age — HOME
The “Uh-Oh” Factor: How Much Do You Actually Need?
Financial gurus love to throw around the “4% rule”—the idea that you can safely withdraw 4% of your savings each year without running out of money for 30 years. If your net worth is $410,000, that’s $16,400 a year in withdrawals. That’s not exactly lavish.
Add in Social Security (average benefit: about $1,900 a month in 2025), and you’re living on roughly $39,000 a year. That’s doable if you live in a tiny house in Alabama and knit your own sweaters. But a trip to Paris? You might need to sell a kidney. (Kidding! Your kidneys are not a retirement fund—probably.)
So, what’s the magic number for a comfortable retirement? Most experts say you need to replace 70% to 80% of your pre-retirement income. If you earned $100,000 a year, you need $70,000–$80,000 annually. That means a nest egg of $1.75 to $2 million, if you’re following the 4% rule. Yikes.
But Wait—There’s Good News (Seriously)
Remember, these numbers are just averages—they don’t account for your lifestyle. If you live in a low-cost area, have no mortgage, and enjoy birdwatching more than Broadway shows, you might only need half of that. Financial independence isn’t about a number; it’s about control.
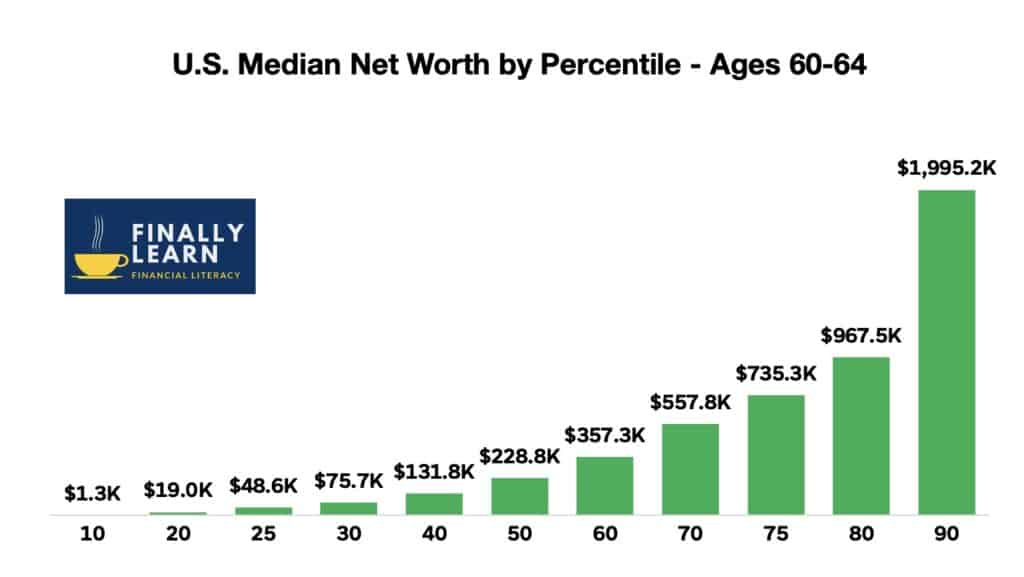 Net Worth Percentiles By Age – Fidelity Net Worth By Age – RLBGMS
Also, the average net worth includes people who save zero dollars. Yes, there are retirees with negative net worth (they owe more than they own). If you’re reading this and you have a positive number, you’re already ahead of some people. That’s like winning a race where half the runners forgot their shoes.
Another fun fact: the average net worth for retirees under 65 is actually lower—around $600,000—because many early retirees are still climbing the ladder or just starting to accumulate. So if you’re 55 and your net worth is $300,000, you’re actually doing fine. Fine is a perfectly respectable word. Fine is the new “fabulous.”
How to Boost Your Own “Retirement Roster”
If your net worth feels more like a “net worry,” here are three playful twists to lighten the load. First, invest in index funds—they’re like a buffet where you don’t have to choose a dish, and the prices are low. Second, downsize your home before you’re forced to. Sell the mansion, buy a cozy condo, and use the extra cash to buy a lifetime supply of Netflix and pizza.
Third, delay Social Security if you can. Waiting until age 70 boosts your monthly check by 8% per year after 67. That’s like getting a raise for napping. Who doesn’t love that?
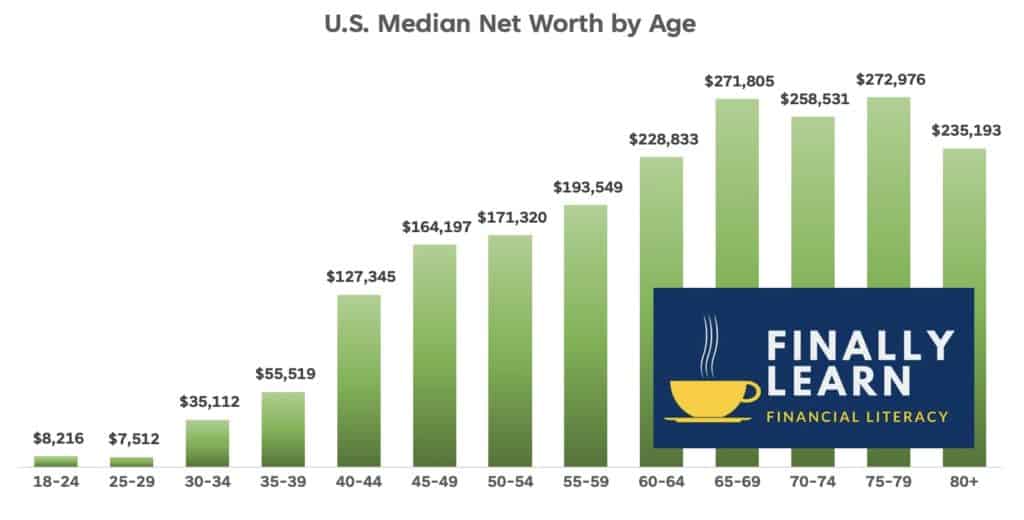 Average Net Worth by Age 50 - Finally Learn
Lastly, embrace the side hustle, even in retirement. Sell your old hobbies—like those macrame plant holders you made in 1998—or teach piano to neighborhood kids. A little extra cash can turn a “I can’t afford coffee” day into a “Let’s go to a fancy brunch” day.
The Uplifting Conclusion (You Knew It Was Coming)
Here’s the truth, friend: The average net worth of retirees is just a snapshot of a moment. It doesn’t measure your joy, your health, or the fact that you can still do a cartwheel (even if it hurts for a week after). Retirement isn’t about the size of your bank account; it’s about the size of your smile.
Whether you have $100,000 or $1 million, you can still enjoy sunsets, good books, and the occasional slice of cake. The real wealth is in your relationships, your memories, and your ability to laugh at the absurdity of it all. So, go ahead—check your net worth, then go for a walk. Eat a cookie. Call an old friend. You’re richer than you think, in all the ways that matter.
After all, the best retirement plan is one that lets you say, “I did it my way,” and then promptly take a nap. You’ve got this. And if you don’t? Well, there’s always ramen. But with extra hot sauce, please.
