Best Credit Card For High Net Worth

Last year, my buddy Mark—a guy who owns three vintage cars and a sailboat—handed me his “everyday” credit card to grab us coffee. I nearly dropped the latte when the barista a...
Last year, my buddy Mark—a guy who owns three vintage cars and a sailboat—handed me his “everyday” credit card to grab us coffee. I nearly dropped the latte when the barista asked for a signature on a receipt that looked like a wedding invitation. It was black, ceramic, and weighed more than my phone. “Dude,” I whispered, “is this made of vibranium?” He just smirked. That’s when I realized: for high-net-worth individuals, the credit card isn’t just plastic—it’s a status symbol wrapped in benefits most of us can’t even pronounce. And if you’re reading this, you’re probably wondering which one actually deserves that spot in your Hermès wallet. (Or, you know, your favorite cargo shorts.)
The “Money-is-No-Object” Card vs. The “Money-is-Everything” Card
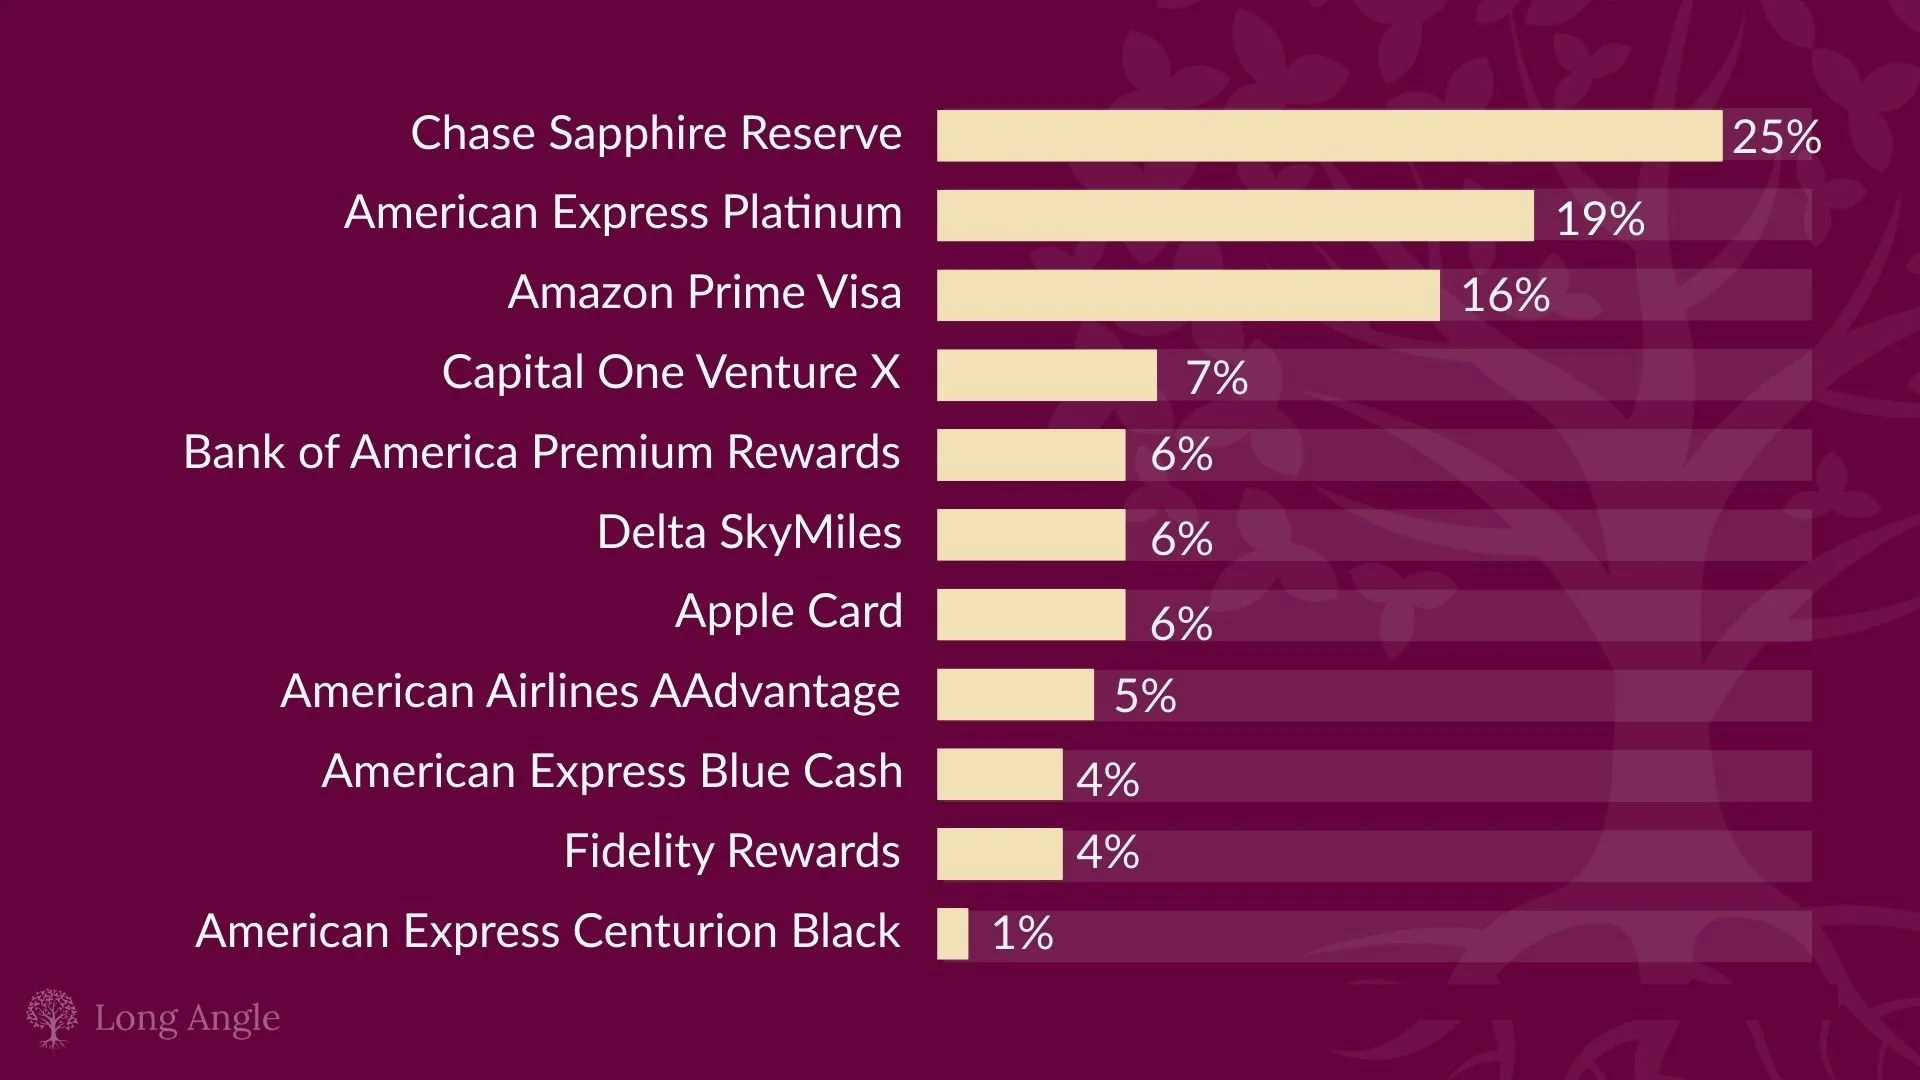
Let’s cut the confusion: there are two camps here. First, the ultra-exclusive cards like the Centurion® Card from American Express—the famous “Black Card” that you can’t even apply for. You get an invite. It’s like winning the lottery, except you already had to be a millionaire. Second, you’ve got the premium-but-accessible heavyweights: the Chase Sapphire Reserve, the Capital One Venture X, or the Citi Prestige. These won’t get you a private butler, but they’ll get you a first-class lounge and a free flight to Bali with a wink. So, which one fits your vibe? It depends on how you want the world to see you—and how much you actually need a concierge at 3 AM to find you a truffle pizza in Tokyo.
The Black Card: More Myth Than Plastic
I’m not gonna lie—the Centurion Card is the holy grail. Annual fee? Around $5,000, plus a one-time initiation fee of $10,000. But wait, it gets worse: you need to spend hundreds of thousands annually just to stay worthy. What do you get? A personal concierge who’ll book you a table at a Michelin-star restaurant on New Year’s Eve when everyone else is eating leftover pizza. Oh, and you get unlimited access to the Centurion Lounges, which are basically spa-level airports with free champagne. But here’s the irony: most people who flash this card never actually use the benefits—they just like the weight of it in their pocket. It’s a flex, pure and simple. And if you’re okay paying $15k a year for a conversation starter, go for it.
Must Read
The Chase Sapphire Reserve: The Overachiever’s Best Friend
Now, let’s talk about the card that made travel hacking a rich-person sport. The Chase Sapphire Reserve has a $550 annual fee (ouch), but it gives you a $300 travel credit that feels like a refund. You also get Priority Pass lounge access, Global Entry/TSA PreCheck fee coverage, and points that transfer to airlines like United and Hyatt at a 1:1 ratio. The real magic? The points are worth 50% more when you redeem them for travel through Chase. So, if you’re flying private for business but driving economy for fun—wait, that’s not a thing—this card makes your splurges feel like savings. I once saw a guy use his points to book a $10,000 flight to Dubai for $3,000. He literally laughed at the gate agent. That’s the power of a smart annual fee.
Capital One Venture X: The New Kid with a Big Ego
Capital One dropped this bomb in 2021, and it’s been giving the big boys a run for their money. The $395 annual fee sounds steep, but you get a $300 travel credit and 10,000 bonus miles every account anniversary—which effectively makes it free after the first year. You also get unlimited Priority Pass access for you and two guests, plus a $100 credit for Global Entry. The catch? The travel credit works through Capital One Travel, so you can’t just use it at a random hotel. But here’s the kicker: the points are worth a flat 1 cent each, so no complex math. It’s the lazy millionaire’s dream—simple, generous, and oddly satisfying. If you’re the type who hates reading fine print, this is your card.
 Best Credit Cards For High Net Worth Individuals - Flik Eco
What About the American Express Platinum?
Ah, the Platinum Card. It’s the gold standard for perks—literally, it’s made of metal. The $695 annual fee stings, but you get $200 in Uber credits, $200 in airline fee credits, $240 in digital entertainment credits (think Hulu, NYT), and access to over 1,400 airport lounges worldwide. Plus, you get complimentary Marriott Bonvoy Gold and Hilton Honors Gold status, which means free room upgrades and late checkouts. The downside? You’ll spend all day managing your credits like a part-time job. I’ve seen friends download spreadsheets just to track which free “breakfast” they haven’t used yet. If you love the game and have a personal assistant to manage it, go Platinum. Otherwise, you’ll feel like you’re working for the card, not the other way around.
The Verdict: Pick Your Poison
So here’s the truth: there is no “best” card for high net worth—there’s only the card that matches your lifestyle theater. Do you want people to gasp when you pay at dinner? Get the Centurion. Do you want to travel like a king without micromanaging points? Grab the Venture X. Do you want to optimize every dollar like a spreadsheet ninja? The Sapphire Reserve or Amex Platinum are your babies. My friend Mark? He uses the Centurion for show and a Costco Visa for everything else. Because at the end of the day, wealth isn’t about what you flash—it’s about what you keep. And a little irony goes a long way.