Best High Net Worth Bank Accounts

So, picture this: my friend Dave, who sold his startup for a frankly obscene amount of money, walks into a gleaming marble bank lobby. He’s expecting champagne flutes and a we...

So, picture this: my friend Dave, who sold his startup for a frankly obscene amount of money, walks into a gleaming marble bank lobby. He’s expecting champagne flutes and a welcome mat rolled out by a butler. Instead, a teller points him to the same roped-off line as everyone else, and offers him a free toaster. He called me, fuming. “I have seven figures,” he hissed, “and they gave me a toaster.” That, my friend, is the difference between a regular bank account and a high net worth one.
Welcome to the world where “free checking” is replaced with “your private jet concierge.” We’re talking about accounts for people who don’t blink at a monthly maintenance fee—because for them, that fee is like a latte. The banks call them “private banking” or “wealth management” accounts. You and I? We just call them the real VIP section.
The Real Perks (Not the Toaster)
First off, let’s trash the idea that these accounts are just higher interest rates. Nope. Interest is for peasants. For high net worth individuals, the magic is in relationships. You get a dedicated banker—someone who answers their phone at 10 p.m. on a Sunday because you’re buying a vineyard in Tuscany. (Yes, that’s a real call.)
Must Read
What about fees? They vanish like my willpower at a dessert buffet. Wire transfers? Free. ATM fees worldwide? Reimbursed instantly. Overdraft? Honey, you don’t overdraft—your banker pre-approves a credit line that makes your head spin. It’s like having a financial bodyguard who also handles your dry cleaning.
Who Even Qualifies? (Hint: It’s Not You Yet)
Here’s where it gets ironic. Most banks require a minimum balance of $250,000 to $1 million just to open the door. Ouch. But wait—some are more relaxed. Digital-first players like Merrill Edge or JP Morgan Private Bank start around $500k, but Morgan Stanley and UBS want a cool $1 million+. The fun part? They compete for you. If you bring a $2 million portfolio, they’ll practically fight each other to waive fees and offer you a customized credit card with no spending limit.
Side note: Do not walk into a Chase branch and ask for a “high net worth account” if you have $50,000. They will politely direct you to the free checking line. (I learned this the hard way.)
 What is the Best Bank for High Net Worth Clients? 9 Options
The Secret Sauce: Unlisted Benefits
The listed perks are boring: travel insurance, low loan rates, estate planning. The real perks are unspoken. Need a last-minute ticket to the Super Bowl? Your banker has a hook-up. Want to offer your kids a summer internship at Goldman Sachs? Your banker knows a guy. It’s access over cash. One client I read about had his banker overnight a rare watch from Switzerland just because he mentioned it in conversation. That’s service.
And let’s talk about security. These accounts often come with fraud protection that borders on paranoia. Every transaction over $10,000 gets a courtesy call from a human. Lost your debit card in Bali? A replacement is hand-delivered by courier within 4 hours. Try that with your local credit union.
The Catch (Because There’s Always a Catch)
Here’s the ironic truth: these accounts are not for everyone. If you’re the kind of person who checks their balance daily and worries about ATM surcharges, this world will feel suffocating. High net worth banking is built on trust—you hand over your financial life, and they give you a golden key. But if you hate being called by your banker every quarter to “review your portfolio,” you might prefer a simpler option. (I’m looking at you, Charles Schwab.)
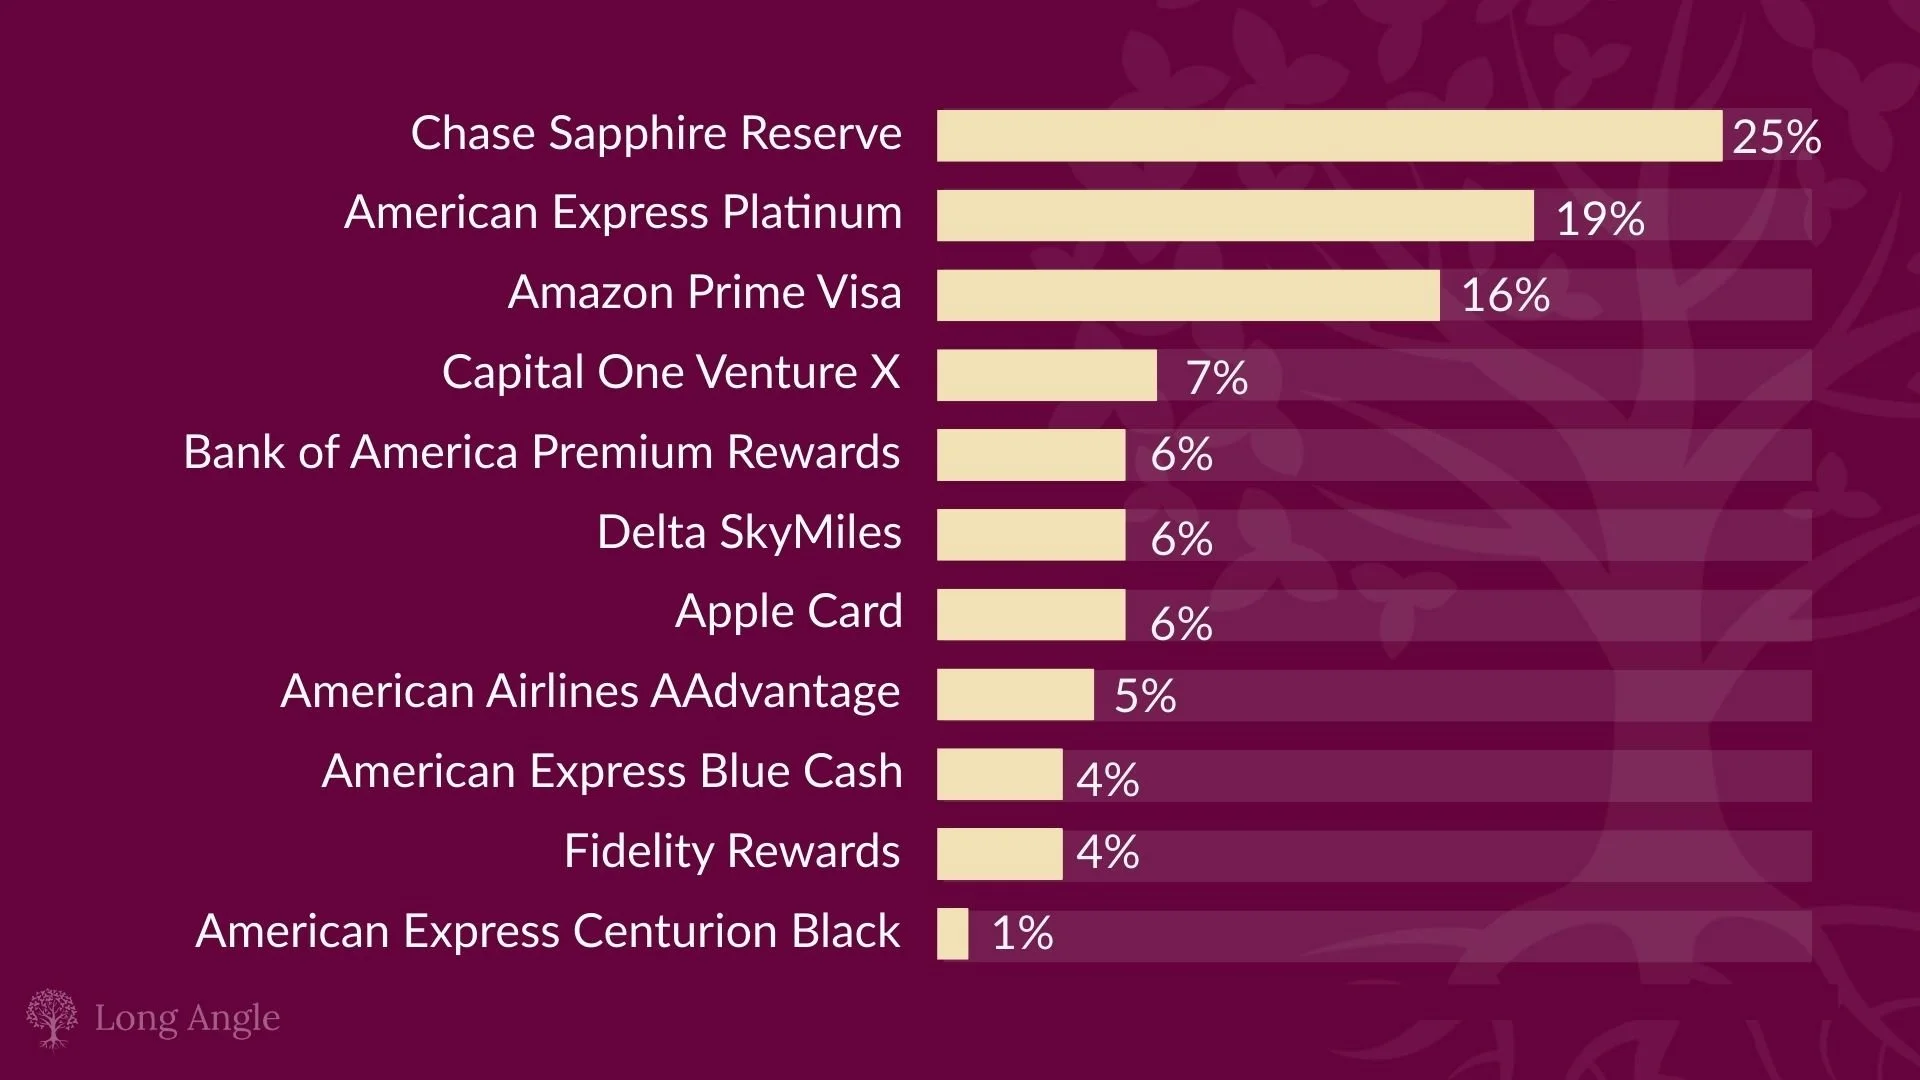 The Best Credit Cards for High-Net-Worth Individuals
Also, beware of minimum balance penalties. Dip below that $1 million for a single day? You’ll get a letter with a fee that’ll make you choke on your avocado toast. It’s the price of admission to the club.
Top Picks for the Wealthy Wanderer
After digging through forums and talking to actual millionaires (not the LinkedIn kind), here’s the shortlist:
JP Morgan Private Bank – Old money, but they treat you like royalty. Their travel perks are insane: free business class upgrades, access to airport lounges that are basically art museums. Minimum: $1 million.
 Richest Bank in the world | Top 100 Most Successful Banks - YouTube
UBS – Best for international clients. Want to move money between your Swiss chalet and your London flat? They have a button for that. Minimum: $2 million.
Merrill Edge – A softer entry point at $250k. Ideal if you’re “emerging affluent” and not quite Oprah-level. Their concierge service is solid, but you won’t get the watch courier treatment.
First Republic – Known for insanely low mortgage rates for wealthy clients. Their checking accounts have zero fees if you keep $100k+, which is basically free for them to maintain.
Final Thought: It’s a Mindset
Dave eventually switched to JP Morgan. His first call? The banker helped him finance a collection of vintage guitars. No toaster. Just a guy who now gets personalized birthday gifts from his bank—like a bottle of single malt with his name engraved. That’s the real difference. High net worth banking isn’t about money; it’s about being treated like money should be treated. (Until you accidentally overdraft by a dollar. Then it’s all, “Sir, please review our fee schedule.”) Choose wisely.
