Cfpb Net Worth Assets Minus Liabilities

Let’s talk about something that sounds like a snooze fest but is actually a wild ride: the CFPB’s definition of net worth. Yep, the Consumer Financial Protection Bureau. They’...

Let’s talk about something that sounds like a snooze fest but is actually a wild ride: the CFPB’s definition of net worth. Yep, the Consumer Financial Protection Bureau. They’re the folks who make sure banks don’t pull a fast one on you. And they have a quirky little formula for figuring out your net worth.
It’s assets minus liabilities. Simple, right? But here’s where it gets fun. The CFPB uses this math to decide if you’re a “covered person” under their rules. That’s right—your net worth might make you officially weird in the eyes of the law.
What’s an Asset? (More Than Just Your Sock Collection)
Assets are anything you own that’s worth money. Think cash, stocks, and that dusty guitar you swear you’ll learn to play. Even your pet hamster is an asset… if he’s a champion breeder.
Must Read
The CFPB counts real assets like houses and cars. But they also count intangibles, like patents for a self-deleting meme. Weird, right? Your grandma’s vintage Beanie Baby collection could be a liability if it’s taking up closet space.
Liabilities: The Party Poopers
Liabilities are the debts you owe. Think mortgage, student loans, and that money you borrowed for pizza last week. The CFPB cares about big numbers—like if your net worth exceeds a certain threshold.
Fun fact: If your liabilities are higher than your assets, you have a negative net worth. That’s just a fancy way of saying you’re broke. But hey, even Jeff Bezos was broke once (probably).
Why the CFPB Cares About This Math
The CFPB uses net worth to enforce consumer protection laws. If your net worth is over $5 million, you might be exempt from some rules. Wait—that sounds backwards, right? It’s like saying, “You’re too rich for us to protect you.”
Actually, it’s about small businesses. The CFPB wants to go after giant corporations that mess with your paycheck. If you’re a local bakery with a net worth under $5M, you get a pass. If you’re a mega-bank, you’re in the bullseye.
 Net Worth Assets and Liabilities - Personal Financial Literacy | 7th
The Quirky Threshold Game
Here’s a weird detail: The CFPB adjusts that $5 million number every year for inflation. So your net worth might be exactly $5.1 million one year—and then $4.9 million next year. That’s like a magic line that moves with the cost of avocado toast.
Imagine being a company just barely over the limit. You’d be sweating like a pig in a sauna. “Oh no, our net worth grew by $2.58! Now we have to follow all the rules!”
How to Calculate Your Own Net Worth (Without Crying)
Grab a napkin and a pen. List everything you own: cash in your wallet, your car’s value (check Kelley Blue Book, not your dreams), and that weird NFT you bought on a whim. Add it up. That’s your assets.
Now list what you owe: credit card debt, the rest of your car loan, and that IOUs from your roommate who owes you for three months of Netflix. Subtract that from assets. Boom—your net worth.
If it’s negative, don’t panic. The average American’s net worth is about negative $10 until they’re 40. You’re in good company.
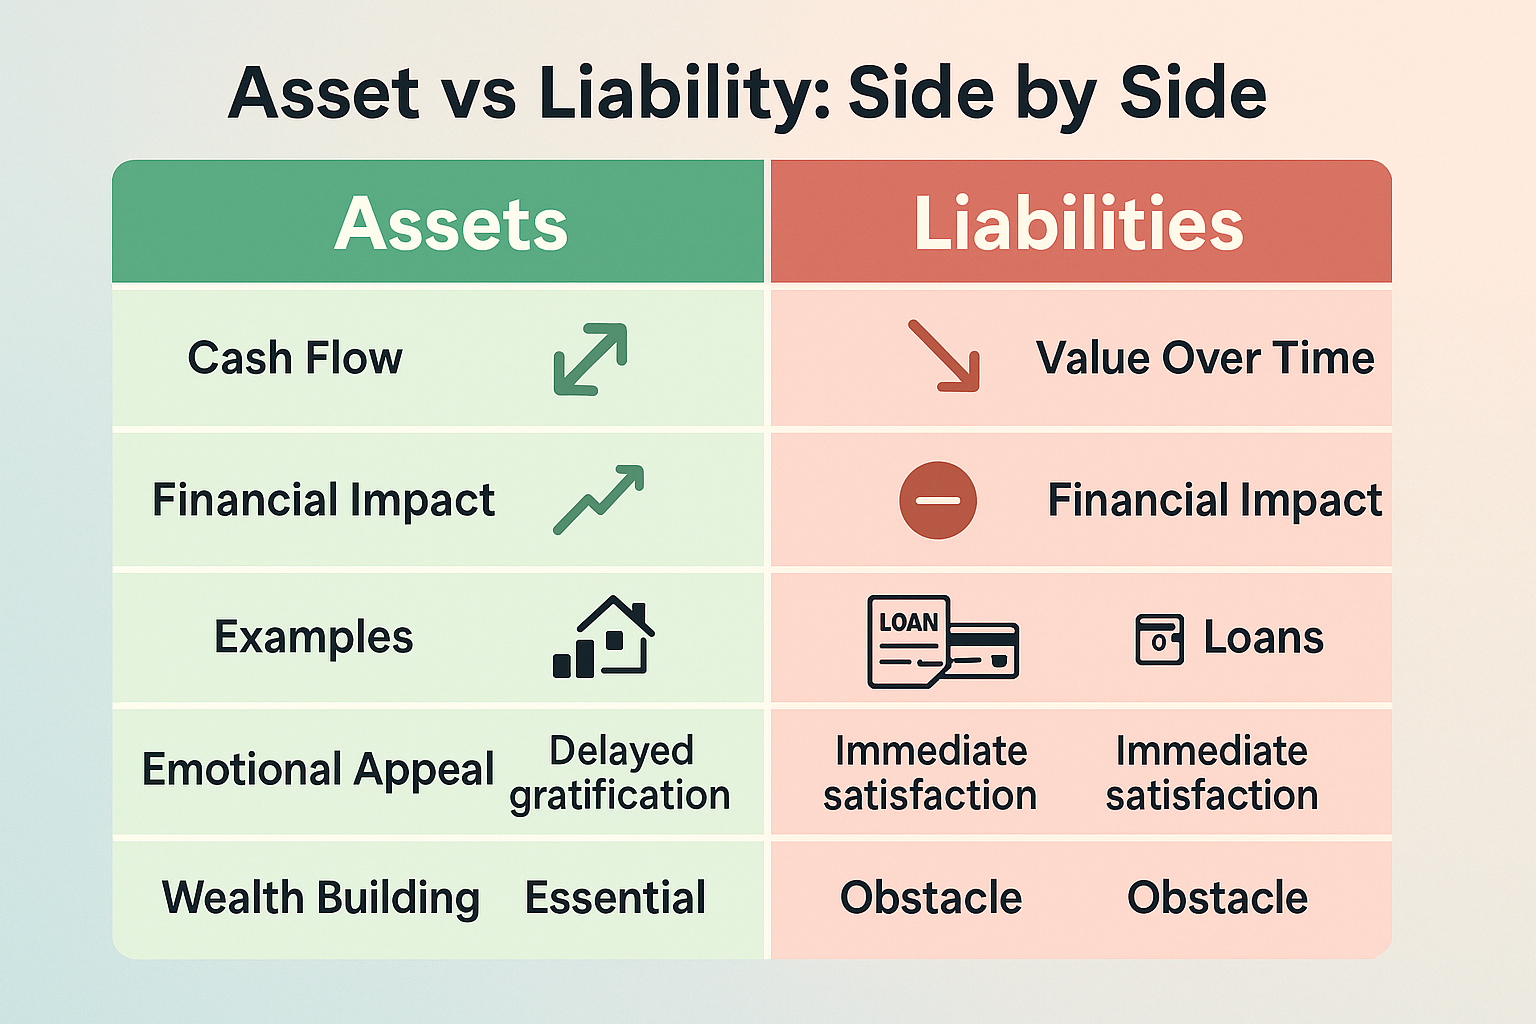 Assets vs Liabilities: What You Own vs What You Owe - The Rich Guy Math
Why This Topic Is Actually Fun
Because it’s math with drama. The CFPB turns a boring subtraction problem into a spy thriller. Are you a “covered person”? Is your net worth hiding something? Does your pet iguana’s value count as a liability if it eats your furniture?
Plus, it’s a great party trick. At your next dinner party, casually drop: “Did you know the CFPB uses assets minus liabilities to determine if you’re a small business?” Watch people’s eyes glaze over—then wake up when you mention the $5 million limit.
Talk about a conversation starter. Or killer.
The Dark Side: When Net Worth Gets Weird
The CFPB has a rule for “small creditors” if your net worth is under $2.1 million. That means your neighbor with a vintage car collection might be a big creditor without knowing it. That’s like discovering your dog is secretly a licensed therapist.
And here’s a funny catch: Retirement accounts don’t always count. Your 401(k) might be huge, but the CFPB says, “Nah, that’s not real money until you’re 65.” So you could be a paper millionaire and still be treated like a broke college student.
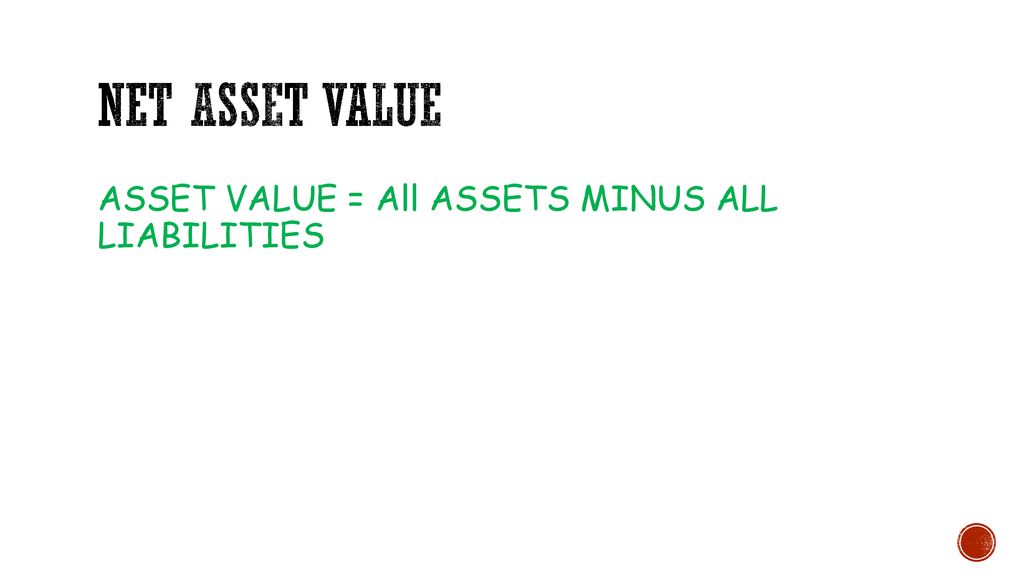 What is the business worth? - ppt download
Cha-ching! Confusion abounds.
What If You Lie About Your Net Worth?
Don’t. The CFPB has enforcement powers. They can audit your assets faster than you can say “bankruptcy.” One guy tried to hide a Lamborghini as a “work vehicle.” The CFPB found out, and now he’s got a fancy new car—and a fancy new lawsuit.
Fun fact: The CFPB has recovered over $19 billion for consumers since 2011. That’s a lot of refunded overdraft fees and forgiven debts. So if you tell the truth about your net worth, you might get a check in the mail.
The Bottom Line (Get It?)
Net worth is assets minus liabilities. The CFPB uses it to draw a line in the sand—or a line in your bank account. It’s a number that decides if you’re a David or a Goliath in the consumer protection world.
So next time you balance your checkbook, remember: The CFPB is watching. Not in a creepy way. In a “we’ve got your back” way. And if your net worth is negative, hey—you’re just leveraging your debt like a pro.
Now go impress your friends with your knowledge of obscure federal regulations. They’ll either think you’re a genius, or they’ll slowly back away. Either way, you’re winning.
