Current Net Worth Of Investments Fafsa

So, you’re staring at the FAFSA form, and it asks for your “current net worth of investments.” Your brain immediately flashes to a scene from Billions, right? You picture hedg...
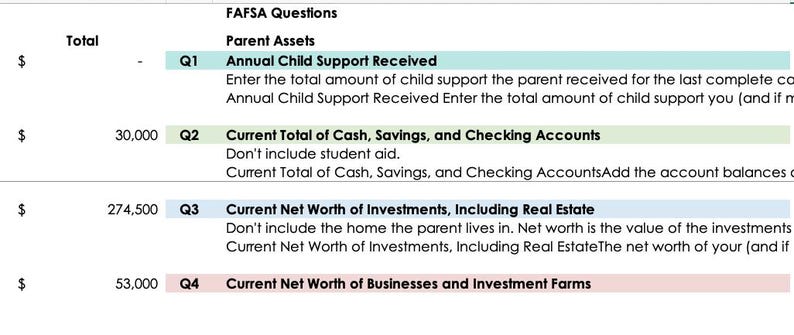
So, you’re staring at the FAFSA form, and it asks for your “current net worth of investments.” Your brain immediately flashes to a scene from Billions, right? You picture hedge fund managers in slick suits, yelling about derivatives over glasses of scotch. Meanwhile, you’re sitting there in sweatpants, trying to remember if that one share of GameStop you bought as a joke still exists.
Let’s be real: for most of us, “investments” means the $47.32 in your Robinhood account, or maybe that dusty 401(k) from a job you quit three years ago. The form wants you to declare your net worth, but your actual net worth fluctuates based on whether you skipped the morning latte. It’s like asking a cat to report its liquid assets—highly unpredictable and mostly imaginary.
The Great Wallet Reality Check
When FAFSA asks about investments, it’s not sniffing around for your secret gold bullion stash. They mean stocks, bonds, mutual funds, and that mysterious crypto wallet you forgot the password to. Your car doesn’t count. Your vintage Pokémon card collection? Nope, not even a Charizard. They only want the stuff that makes you look slightly wealthier on paper than you actually are in real life.
Must Read
I remember filling out the form for my first semester of college. I had a single, sad index fund that was worth exactly $253.78. I typed it in with the solemnity of a Wall Street tycoon, as if that amount would sway the financial aid gods. Spoiler: it did not. They just sent me an email saying “expected family contribution,” which I’m pretty sure is code for “good luck with those ramen noodles.”
When “Investments” Means Your Spare Change Jar
The funny thing is, FAFSA’s definition of “current net worth” is hilariously out of touch with everyday life. They want the number as of today, but your account balance could drop by $50 while you’re typing. You refresh the page, and suddenly you’re $50 poorer. It’s like the form is mocking your financial decisions in real time.
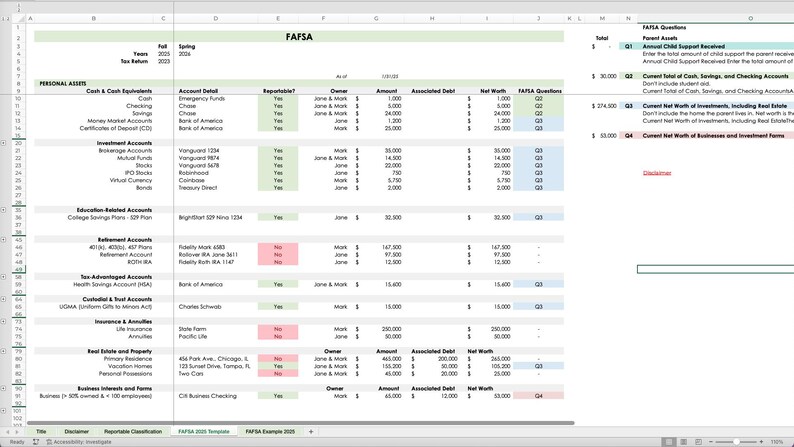 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
And let’s talk about the ultimate nightmare: the rental property question. The form asks if you own real estate other than your primary home. If you have a duplex you’re renting out, they want to know its net worth. That property doesn’t feel like an “investment”—it feels like a headache with a mortgage and a tenant whose cat somehow broke the furnace. You google “how to value a property you inherited from your grandpa” and end up on a forum where someone says, “Just lie, they’ll never check.” Don’t lie. The government will check, and they have lasers.
Most of us are stuck in the middle ground, what I call the “Sweatpants Portfolio.” You have a 401(k) worth about two months of rent, a savings account that’s mostly for “emergencies” (which you’re pretty sure includes ordering pizza), and maybe a small inheritance from Aunt Carol. FAFSA wants you to add that up, and your finger hovers over the keyboard. You realize your net worth is basically a round trip bus ticket to the next town.
 Do we really need to disclose true net worth ? : r/FAFSA
There’s a secret club of FAFSA fillers who have mastered the art of creative subtraction. You know the move: you subtract your student loan debt from the investment value, right? Wrong. FAFSA doesn’t let you do that. They want the gross number, before debt, which feels like asking you to report your height while standing on a scale. It’s bafflingly unfair.
I once had a friend who swore his “investment net worth” was zero because he only owned a single, very sad share of a penny stock. He typed “0” with the confidence of a man who had just won an argument with a spreadsheet. The form accepted it. That is the energy you need. Be the zero. Own the zero.
 FAFSA Basics: Parent Assets — How to Pay for College
Here’s the real kicker: if your investment net worth is under $10,000, the Department of Education basically shrugs. They treat it like you told them you found a dime on the sidewalk. Their algorithm is calibrated for people with real portfolios, not for the rest of us who treat our savings account like a rainy-day pot for unexpected parking tickets.
So take a deep breath. Be honest, but be practical. If your only “investment” is an old savings bond from your 12th birthday, just type that in. The government doesn’t care about your sentimental value. And if the number makes you laugh out loud? Write it down anyway. That laugh is worth more than any stock market gain. It’s the sound of a person who knows that real wealth is not having to explain your finances to a robot. Carry that feeling to the submit button. You’ve survived the worst part of the day. Now go eat something that isn’t instant soup.
