Current Net Worth Of Investments Including Real Estate Fafsa

So, you’re filling out the FAFSA, and suddenly you hit that weird question: “What’s your net worth of investments, including real estate?” It feels like the government is aski...

So, you’re filling out the FAFSA, and suddenly you hit that weird question: “What’s your net worth of investments, including real estate?” It feels like the government is asking for your dinner plans, right? Let's dig into this strange little puzzle without the usual stress. We’ll keep it chill, like we’re chatting over coffee.
First, What Even Counts?
Think of this as a snapshot of your financial “toy box.” It’s not your checking account or the cash in your sock drawer. We’re talking about stuff that’s meant to grow in value, like stocks, bonds, mutual funds, and—yep—real estate that isn’t your primary home.
If you own a rental condo or a piece of land you plan to sell, that’s an investment. Your own house where you sleep and eat breakfast? The FAFSA usually ignores it completely. Why? Because they assume you need a roof over your head, not a piggy bank for tuition.
Must Read
It’s a bit like the difference between your everyday wallet and your “emergency chocolate stash.” One is for immediate use, the other is a secret treasure.
Why Does FAFSA Care About This Stuff?
Here’s the kicker: the government wants to know if you have a secret pile of cash that could help pay for school. They’re not snooping for fun—it’s about fairness. The formula assumes that investments and real estate are “extra” resources that you can tap into for college, unlike your salary, which you actually need to live on.
Think of it as the financial aid version of “don’t bring a sandwich to a buffet.” If you have assets, they expect you to use a little of them before asking for free money. It’s a bit annoying, but it’s how the system tries to level the playing field.
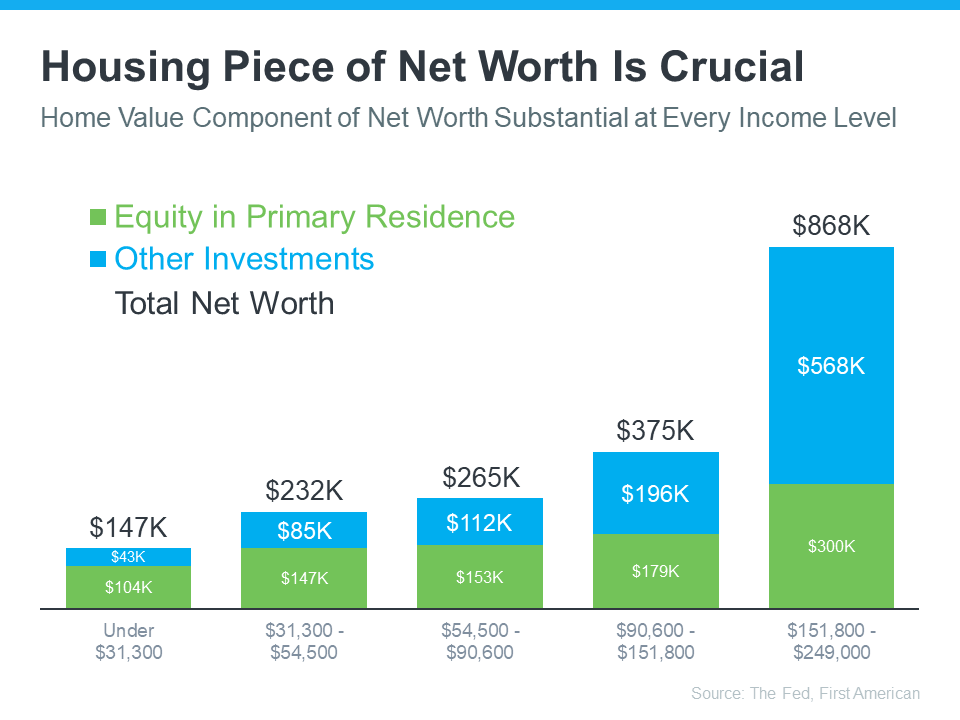 The Dramatic Impact of Homeownership on Net Worth - HomeTeam605.com
But Wait—What If My “Net Worth” Is Negative or Tiny?
No worries! If you own a rental property with a huge mortgage, that negative equity counts as a $0 for FAFSA. You’re not penalized for being in debt. It’s like having a fancy car that doesn’t run—it looks impressive, but it won’t get you anywhere.
The system is surprisingly forgiving for small stuff. A few hundred bucks in stocks? They barely blink. It’s when you have a small mansion’s worth of investments that the aid office starts raising an eyebrow.
The Fun Comparison: Nerf Guns vs. FAFSA
Imagine you’re at a birthday party, and the host asks who needs a free slice of cake. The rule is: “Only kids who didn’t bring their own dessert.” Your investments and real estate are your cool, fancy dessert you brought from home. FAFSA is the host checking your picnic basket before handing out cake slices. It’s not personal—it’s just the rules of the party.
If you’ve got a small rental property or a few shares of Apple stock, you’re basically the kid with a single cookie. The host might still give you a slice because the cookie is tiny. But if you own three rental homes and a mutual fund? You’re bringing a whole gourmet cake, so you’re expected to share your own treat first.
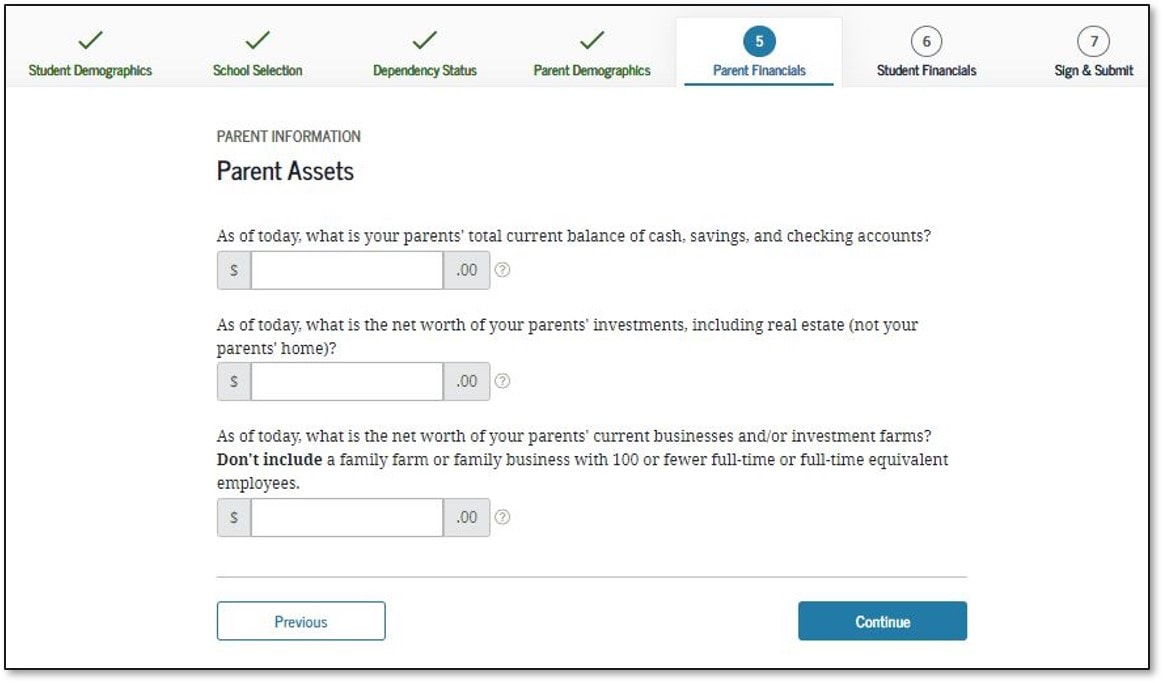 Filling Out The 2023-2024 FAFSA | Financial Design Studio
How Do You Even Calculate It?
It’s simpler than you’d think. Add up the current market value of your investments (what you could sell them for today) and subtract any debts directly tied to them. For real estate, that’s the property value minus the mortgage balance. For stocks, it’s just the cash value.
Don’t count retirement accounts like a 401(k) or IRA—those are magically protected from FAFSA. Also skip your family car, your grandpa’s coin collection, or the value of your Beanie Baby stash. Unless they’re worth a fortune, they don’t matter.
A Real-World Example (No Math Anxiety)
Say you own a small apartment building worth $200,000, but you owe $150,000 on the loan. That’s a $50,000 net worth for FAFSA. If you also have $10,000 in stocks, your grand total is $60,000. FAFSA only counts a portion of that for student aid, usually around 20% for students and 5.6% for parents. So, $60,000 might only shave a few thousand off your aid eligibility—not a total disaster.
 Net Worth Of Real Estate Fafsa at Madison Calder blog
It’s like bringing a flask of soda to a movie theater: a little is fine, but a keg will get you kicked out of the free popcorn line.
Why Is This Interesting, Really?
It’s cool because it forces you to think about your net worth as a story, not just a number. Your real estate investments aren’t just assets—they’re future opportunities, security, or even a side hustle. The FAFSA is just a strange mirror reflecting how much financial padding you have.
Plus, it’s a reality check: most people overestimate their “wealth” until they subtract debt. You might feel broke, but then realize a rental property actually gives you a hidden superpower in the financial aid game. Or you might learn that your small investments are basically a drop in the ocean for FAFSA, so relax.
So next time you see that question, take a breath. You’re not being grilled—you’re just telling a boring, data-driven story about your piggy bank. And remember, the government mostly cares about the big desserts you’re hiding in your backpack. Your little cookie stash? It’ll be fine.
