Current Net Worth Of Investments Including Real Estate Fafsa Meaning

Let’s talk money, real estate, and a weird acronym: FAFSA. You’ve probably seen it on college forms. It sounds like a sneeze, right? But it’s actually a financial superhero fo...

Let’s talk money, real estate, and a weird acronym: FAFSA. You’ve probably seen it on college forms. It sounds like a sneeze, right? But it’s actually a financial superhero for students.
Here’s the fun part. Your net worth—the total of your investments, cash, and that fixer-upper you bought—is secretly the villain in FAFSA’s story. Why? Because FAFSA hates rich parents.
What Even Is FAFSA?
FAFSA stands for Free Application for Federal Student Aid. It’s a form that decides how much college money you get. Think of it as a nosy neighbor who wants to see your bank account.
Must Read
It asks: “How much cash do you have? Got a house? Any stocks?” Then it uses your net worth to figure out if you’re “poor enough” for grants. Spoiler alert: It’s not a fan of your rental property.
The government assumes you’ll sell your investments to pay for tuition. Yes, even that vintage Beanie Baby collection. Especially the Beanie Babies.
Your Net Worth: The Puppet Master
Let’s break down your net worth. It’s simple: assets (cash, stocks, house) minus debts (mortgage, student loans, that pizza you owe your roommate). If you own a house worth $300,000 but owe $200,000, your net worth from real estate is $100,000.
Funny thing: FAFSA counts your primary home as a protected asset. It doesn’t punish you for owning a roof over your head. But your second vacation cabin? That’s fair game. FAFSA will sniff it out like a truffle pig.
So, if you’ve invested in a beach condo and a stock portfolio, your net worth is enormous to FAFSA. You might get zero aid. Congratulations?
 How to Create a Real Estate Investment Model in Excel - Financial Edge
Quirky Fact: The “FAFSA Penalty”
Here’s a wild detail. FAFSA takes up to 5.64% of your parents’ assets (excluding retirement and home) as the “expected contribution.” But if you’re a student with your own money? FAFSA takes 20%. Yes, twenty percent. Your side hustle flipping sneakers is brutal for aid.
Imagine telling your teen: “Sorry, honey, your Yeezy collection just cost you $5,000 in college grants.” Oops.
And real estate? If you own rental property outright, that net worth is fully visible. No hiding in the attic.
The Fun of Playing Dumb(er)
The best strategy? Keep your net worth low on paper. Not by losing money—but by being smart. Max out retirement accounts, pay off high-interest debt, and don’t hoard cash in a savings account.
Retirement funds (like a 401k) are invisible to FAFSA. So are your life insurance policies. Poof—gone from the calculation. Meanwhile, your neighbor who bought a sports car with cash looks wealthy on FAFSA. Ha.
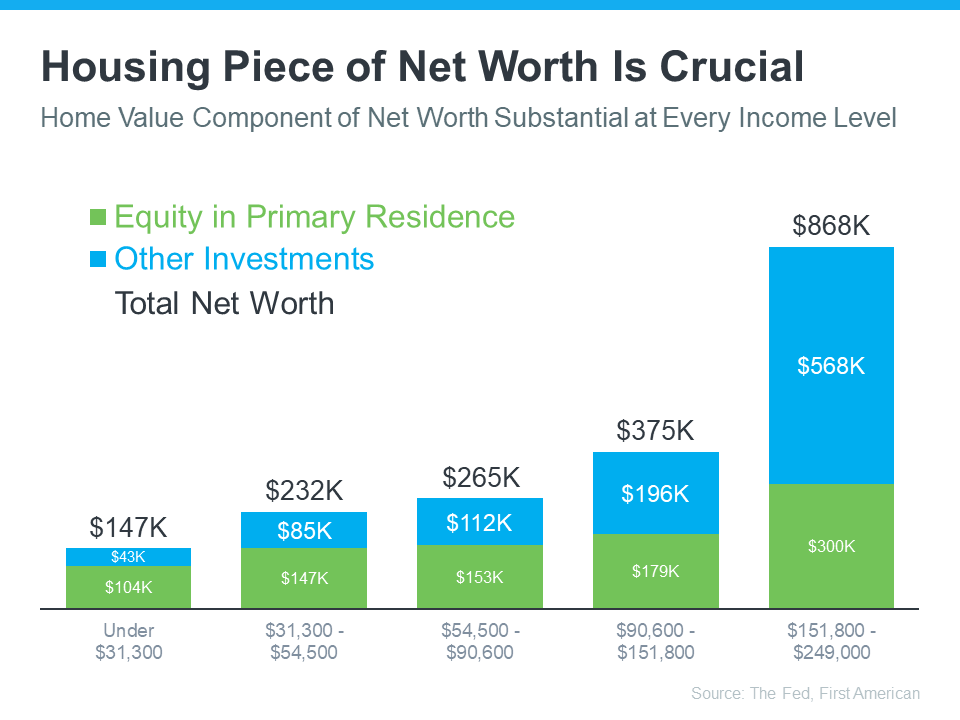 The Dramatic Impact of Homeownership on Net Worth
Also, if you own a small business with fewer than 100 employees, its net worth is ignored. That’s right—your Etsy shop for llama-shaped candles? FAFSA doesn’t care. Burn those candles and hide your money.
Why This Topic Rocks
This is fun because it’s a secret game of hide-and-seek. You’re pitting your net worth against a government algorithm. And the rules are bizarre. For example, if you buy a bigger house next year, your net worth in real estate goes up—but FAFSA doesn’t punish you for it. Your home is safe.
But if you sell that house and put the cash in a brokerage account? Boom—you’re “rich” now. FAFSA sees every dollar. So keep your investments in bricks, not bank accounts.
Quirky fact: The median net worth for a U.S. family is about $192,000. If you’re above that, you’re in the top 50%. Yet FAFSA might still give you aid if your income is low. It’s not just about wealth—it’s about how you hold it.
The Punchline: You’re Not Poor, You’re Clever
So, your net worth including real estate tells a story. FAFSA reads it like a spy novel. If you have a rental duplex and $50,000 in stocks, the government thinks you can pay for college. Surprise: you cannot.
 Net Worth Of Real Estate Fafsa at Madison Calder blog
But you can laugh about it. Because FAFSA doesn’t know you spent that $50k on a llama farm. (Okay, it does, if you filed taxes. But imagine it didn’t.)
Here’s the takeaway: Don’t take FAFSA personally. It’s a blunt tool. It treats your net worth like a number on a fridge. And if you play your cards right—keeping money in real estate, retirement, or a tiny business—you might just get a free ride.
Final Thought: Be the Hero
Your net worth is your superpower. FAFSA is just the anti-hero who wants to see your cape. Make your assets invisible when possible. And remember: your primary home is a fortress. Nobody touches it.
Now go check your portfolio. Laugh a little. Buy a llama candle. Then fill out that FAFSA form with a wink.
After all, it’s just numbers… and a few pretty quirky rules.
