Debt To Tangible Net Worth Ratio

Hey, have you ever felt like you're drowning in debt? I mean, who hasn't, right? It's like, you're trying to stay afloat, but those credit card bills just keep piling up, and...
Hey, have you ever felt like you're drowning in debt? I mean, who hasn't, right? It's like, you're trying to stay afloat, but those credit card bills just keep piling up, and you're like, how did I even get here?
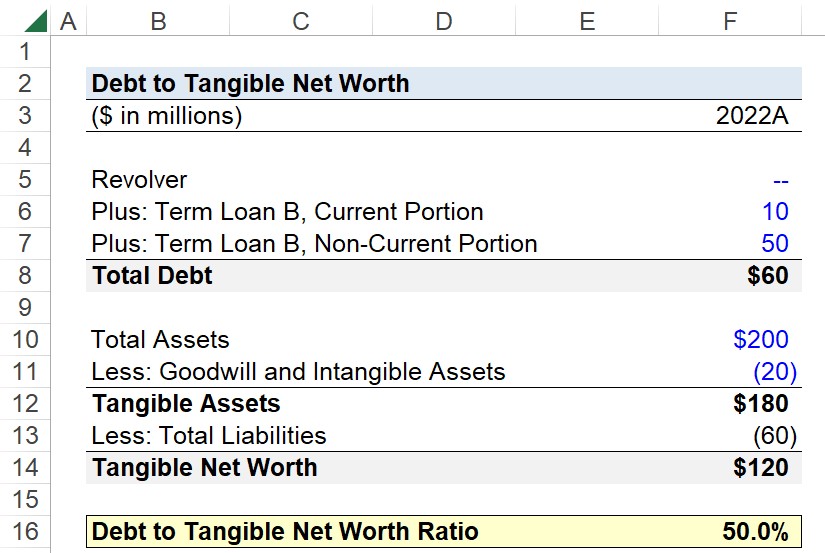
So, let's talk about this fancy thing called the Debt To Tangible Net Worth Ratio. Sounds super complicated, but trust me, it's not that bad. Essentially, it's like a report card for your finances, showing you how much debt you have compared to your actual, tangible assets.
What's The Big Deal About This Ratio?
The thing is, this ratio can give you a pretty good idea of your overall financial health. I mean, think about it, if you've got a lot of debt and not a lot of assets, that's like, a big red flag, right? It's like, you're living beyond your means, and that's not sustainable in the long run.
Must Read
Now, what exactly is tangible net worth? Well, it's basically the value of all your physical assets, like your house, car, and even that fancy watch you just had to have. And then, you subtract your debt, like your mortgage, car loan, and credit card balances. Simple, right?
Calculating The Ratio
To calculate this ratio, you just need to divide your total debt by your tangible net worth. Easy peasy, lemon squeezy. For example, let's say you've got $10,000 in debt and your tangible net worth is $20,000. Your ratio would be 0.5, or 50%, which isn't too terrible, but still, it's like, you've got some work to do.
Now, here's the thing, what's a good ratio? Well, that depends on who you ask, but generally, you want to aim for a ratio of 36% or less. That means, for every dollar you've got in debt, you've got about two dollars in tangible assets. Not bad, right?
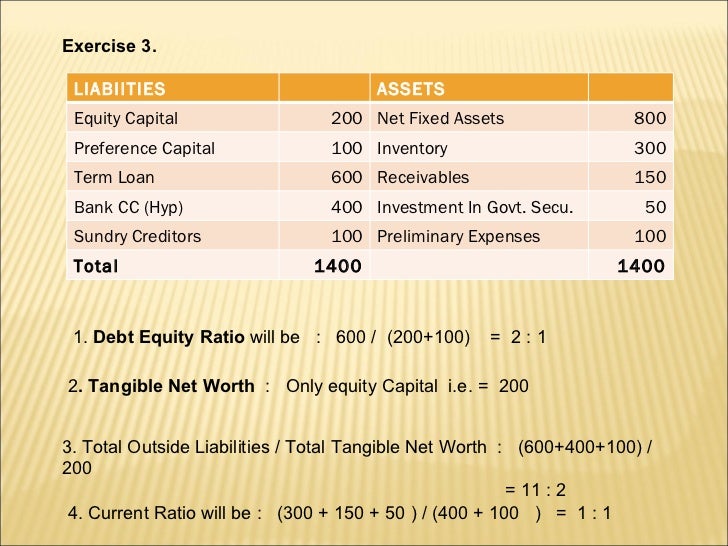 Debt To Effective Tangible Net Worth Ratio – DKCICX
But, let's be real, who actually has no debt? I mean, most of us have some kind of debt, whether it's a mortgage, student loans, or even just a credit card balance. So, it's like, don't freak out if your ratio isn't perfect, just, you know, work on it.
Why This Ratio Matters
So, why is this ratio even important? Well, for one, it can affect your credit score, and we all know how important that is. I mean, you don't want to be stuck with a bad credit score, that's like, financial kryptonite.
Plus, this ratio can also impact your ability to get loans or credit in the future. Like, if you've got a high ratio, it's like, you're a higher risk for lenders, and they might be all, no thanks. Not ideal, right?
 Tangible Net Worth - Definition, Formula, How to Calculate?
And, let's not forget, it's all about perspective. I mean, if you've got a high ratio, it's not the end of the world. You can always work on paying off your debt and building up your assets. It's like, you've got this, you just need to, you know, get to it.
Getting Your Ratio Under Control
So, how do you actually improve this ratio? Well, it's pretty simple, really. You just need to, pay off your debt, and build up your assets. Easy, right? Okay, maybe not, but, you know, baby steps.
One thing you can do is, like, make a budget, and stick to it. That way, you can see where your money is going, and make sure you're not overspending. And, you can also, you know, cut back on expenses, and boost your income. Simple, yet effective, right?
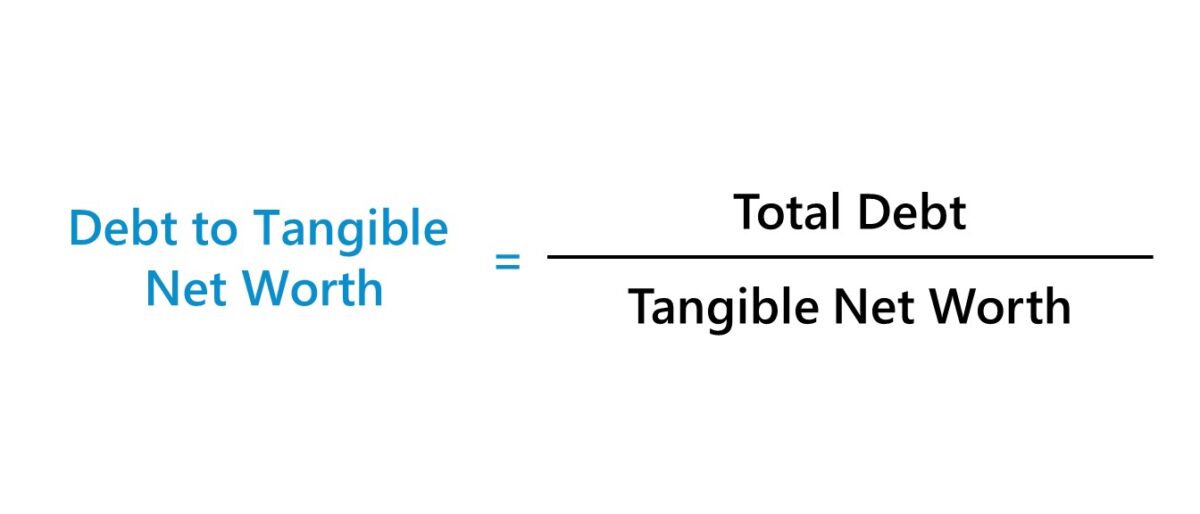 Debt to Tangible Net Worth | Formula + Calculator
And, don't forget, it's all about the little things. Like, if you can just, you know, save a little extra each month, that can add up over time. It's like, you're building a snowball, and eventually, it'll be rolling down a hill, gaining momentum, and, you know, crushing your debt.
So, there you have it, the Debt To Tangible Net Worth Ratio in all its glory. It's not, like, the most exciting thing in the world, but, you know, it's important. And, if you can just, you know, get a handle on it, you'll be, like, golden. Okay, maybe not golden, but, you know, you'll be in a better place financially, and that's, like, pretty great.
Now, go forth, and, you know, conquer your debt. Or, at the very least, make a plan to conquer your debt. Baby steps, right? And, remember, it's all about the journey, not the destination. Unless, of course, the destination is, like, being debt-free, then, you know, that's a pretty great destination.
