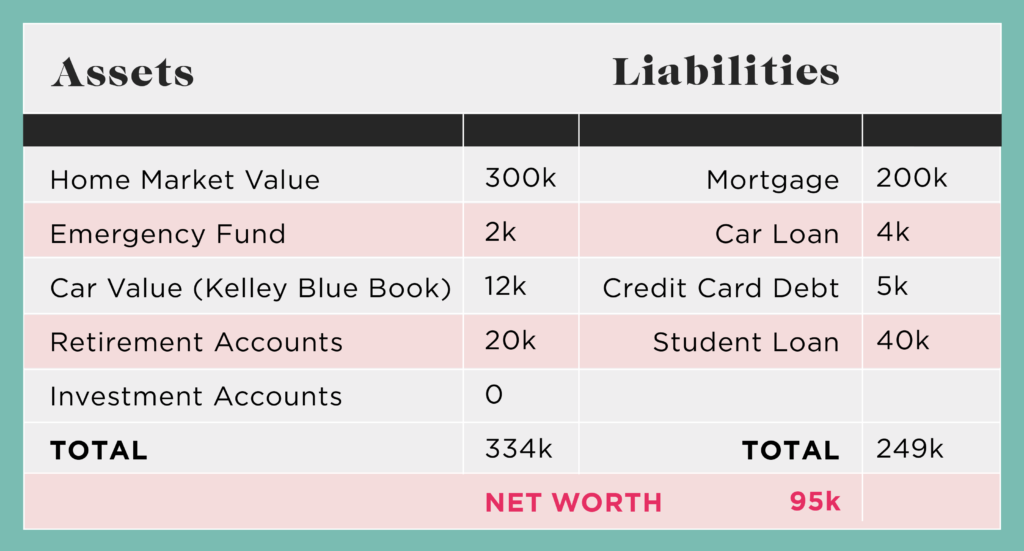
Definition Net Worth Assets Minus Liabilities

Let’s talk about your financial life without the panic attack, okay? You’ve probably heard the term net worth tossed around like a hot potato at a rich-person party. Spoiler a...
Let’s talk about your financial life without the panic attack, okay? You’ve probably heard the term net worth tossed around like a hot potato at a rich-person party. Spoiler alert: it’s not how much you’re actually worth as a human being—that’s infinite and priceless, obviously. It’s just a math formula that sounds scary but is actually as simple as a kid’s lemonade stand ledger.
So, What Is Net Worth, Really?
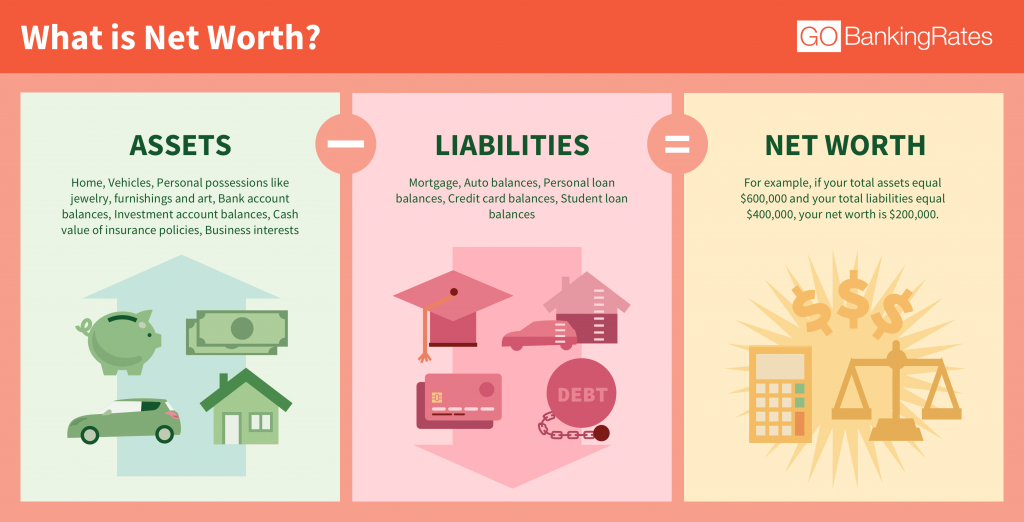
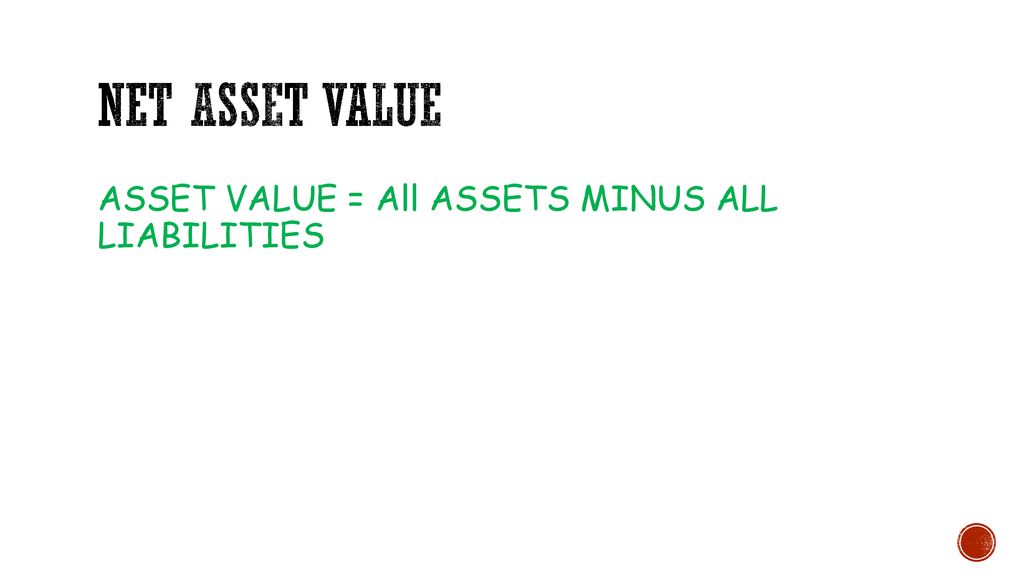
Here’s the secret sauce: Net Worth = Assets Minus Liabilities. That’s it. No wizardry, no secret handshake. You just take everything you own that has value—hello, your collection of vintage Beanie Babies—and subtract everything you owe—hello, that credit card bill from your “treat yourself” weekend. The result is your net worth. If it’s positive, congrats, you’re technically richer than a hobo in a money tree forest. If it’s negative, don’t cry; you’re just living the classic American dream on credit!
Breaking Down the Weird Parts
Assets are the stuff that puts money in your pocket—or could, if you sold it. Think cash, investments, your house (if it’s not a money pit), and that mint-condition Pokémon card you swear is worth a fortune. Liabilities are the debts that take money out of your pocket: mortgages, student loans, and that IOU you signed after borrowing $20 for pizza. The trick is that your net worth can change faster than a cat’s mood. One day you’re a millionaire on paper because your house value skyrocketed. The next day your car breaks down and you owe a mechanic your left kidney.
Must Read
Here’s a surprising fact that’ll make you spit out your latte: many millionaires actually have a negative net worth in their early days. Yep, people like Elon Musk famously had mortgages bigger than their incomes at one point. But guess what? They also had massive assets—like companies that didn’t even exist yet—so their net worth eventually exploded like a soda can in a freezer. The key is that net worth is a snapshot, not your whole life story. It can flip from “broke” to “baller” in a few years.
Why You Should Care (Even if You’re Broke)
Tracking your net worth is like having a financial GPS, but without the annoying voice yelling “recalculating.” It forces you to see that your liabilities are the real villains in your bank account drama. For example, if you have a $50,000 car loan but the car is only worth $30,000, that’s a stinky $20,000 liability hole. Your net worth just took a nosedive. Assets are your friends—they grow, they earn, they cuddle you at night with security. Liabilities are the clingy ex who texts you at 2 a.m. demanding money.
 What is the business worth? - ppt download
Still not convinced? Let me drop a mind-bender: the average American household has a net worth of around $120,000. But that number is skewed by billionaires like Jeff Bezos—take him out, and the median household net worth is closer to $10,000. That’s right, half of Americans have less than ten grand to their name. So if your net worth is a big fat zero, you’re basically normal. Congratulations, you’re average! (And that’s better than being below average, unless you’re in a limbo contest.)
How to Actually Calculate It Without a Panic Attack
Grab a napkin or your Notes app—this isn’t rocket science. List your assets: cash in your sock drawer, your 401(k) that’s slowly recovering, the value of your house (check Zillow, but don’t trust it), and yes, that stamp collection your grandpa left. Total that number. Now list your liabilities: your mortgage, car loan, credit card balance, and any other debts. Subtract the liabilities from the assets. If the result is negative, that’s okay—think of it as a future success starter pack. If it’s positive, go buy yourself a fancy coffee and smirk at your reflection.
 What’s Your True Financial Standing: Calculating Net Worth
Here’s a funny truth: your net worth doesn’t care about your feelings. It’s cold and mathematical, like a robot accountant. But if you improve it over time, it becomes your best wingman. Assets grow with compound interest—which Albert Einstein called the “eighth wonder of the world.” Liabilities grow with compound interest too, but in a bad way—like a zombie apocalypse for your wallet. So pay off high-interest debt first, then build your assets. It’s that simple.
The Final Punchline
Never fall for the trap of confusing net worth with self-worth. I once met a guy with a $10 million net worth who was miserable because his yacht had a scratch. Meanwhile, your grandma with a $50,000 net worth and a garden full of tomatoes is the happiest person alive. Net worth is just a number, but it’s a useful number—like your age, but less depressing. So track it, laugh at it, and remember: if all else fails, you can always start a TikTok about being broke. That’s an asset of personality, and it’s worth more than money.