Definition Net Worth Total Assets Minus Liabilities

Let’s be honest: the phrase “net worth” can sound like something only billionaires and finance bros whisper about over carbon-neutral oat lattes. But net worth is actually jus...
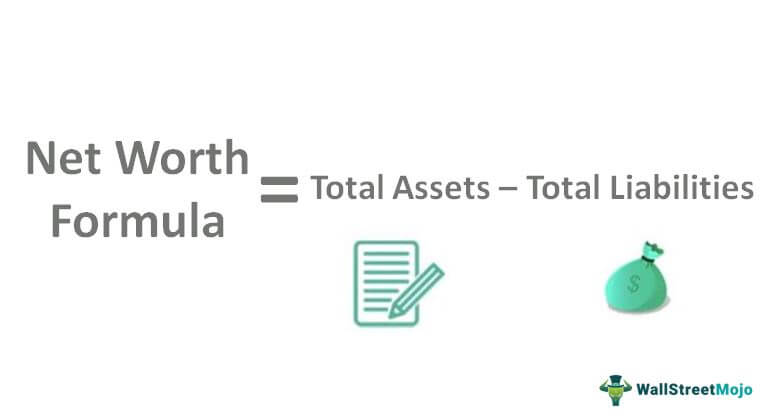
Let’s be honest: the phrase “net worth” can sound like something only billionaires and finance bros whisper about over carbon-neutral oat lattes. But net worth is actually just a simple, powerful snapshot of your financial health. It’s your winning scoreboard in the game of adulting, and the best part? Anyone can calculate it.
At its core, the definition is beautifully straightforward: Net worth equals total assets minus total liabilities. Think of assets as everything you own that has monetary value—your savings, investments, that vintage guitar, or even the equity in your home. Liabilities are your debts: student loans, credit card balances, and the car payment you keep meaning to double-check.
The Reality Check (That’s Actually Good for You)
Remember that scene in The Wolf of Wall Street where Leonardo DiCaprio screams about the number? Yeah, ignore that energy. Your net worth isn’t a measure of self-worth. It’s a quiet, honest mirror—and sometimes the reflection shows a negative number. That’s totally normal, especially if you’re just starting out.
Must Read
For most people under 40, a negative net worth is almost a rite of passage, like having a messy apartment or surviving on instant ramen. The magic happens when you stop panicking and start tracking. Fun fact: Jerry Seinfeld supposedly kept a “net worth” journal in the early days of his career, noting only the numbers without judgment. It worked.
Practical Tip #1: The 15-Minute Audit
You don’t need a spreadsheet worthy of a hedge fund. Grab a napkin (or your Notes app) and list three things: your bank account balance, your highest-interest debt, and any asset you could sell for cash in a week. Subtract the debt from the assets. That’s your raw number.
Don’t be shocked if it’s smaller than your Instagram followers. Consistency beats size every time. Do this audit once a month, and watch the plot twist unfold.
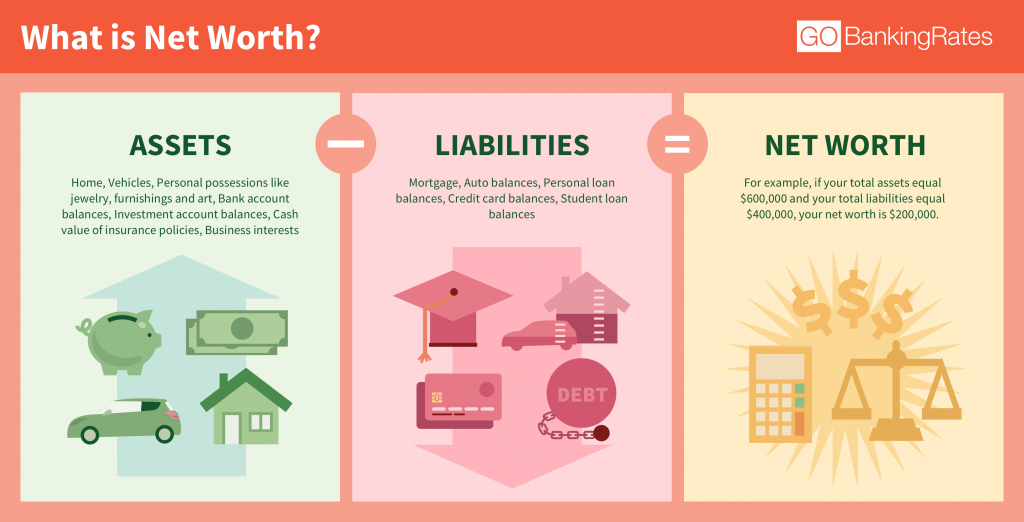 Determine Your Net Worth in 3 Easy Steps! - New Century Investments
The Life-Envy Correction: Assets ≠ Income
Here’s a cultural truth bomb: your neighbor with the shiny Tesla might have a net worth of negative $50,000 if she’s leasing it. Meanwhile, your frugal buddy who drives a ‘97 Corolla and invests $200 a month could be quietly sitting on $100,000. Income is what you earn; net worth is what you keep.
Think of it like the difference between a celebrity’s publicist and their accountant. Kim Kardashian’s net worth is famously debated, but the principle is the same: assets minus liabilities. No spin zone. Your car, your influencer wardrobe, your Peloton—they’re only assets if they’re paid off and can be turned into cash. Otherwise, they’re just fancy paperweights.
Practical Tip #2: The “Billie Eilish” Move
You know how Billie Eilish famously avoided streaming for years to protect her art? Apply that energy to your spending. Before buying something fun, ask yourself, “Is this an asset or a liability?” A streaming subscription you never use? Liability. A cooking class that helps you meal prep and save $100 a month? Sneaky asset.
Small wins add up. The average American spends about $1,300 a year on unused subscriptions. That’s a direct debit to your net worth. Kill two subscription services today, and you’ve just added $200 to the asset column.
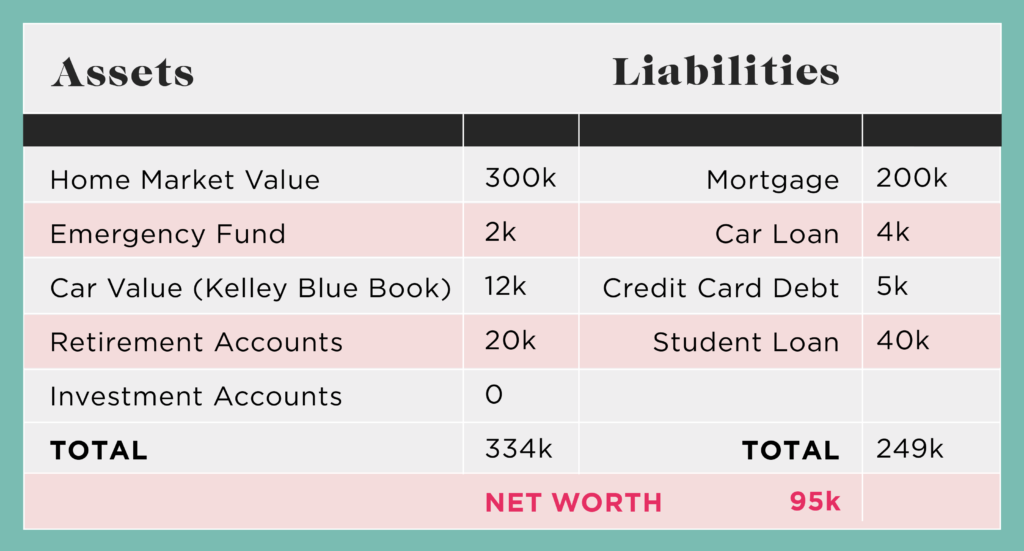 What Your "Net Worth" Is, Why You Should Always Know It, & How To
The Emotional Math: Why It’s Not Just Numbers
Net worth has a quiet psychological undercurrent. When your liabilities are high, you feel heavy, like you’re walking up a hill in wet sand. When your assets climb, you walk lighter. It’s not about being rich; it’s about having options. That’s the real luxury.
Think of it like Marie Kondo for your wallet. Does that student loan spark joy? Probably not, but paying it down sparks freedom. Viewing net worth through this lens turns a boring calculation into a daily act of self-care.
Practical Tip #3: The “Tiana” Strategy
Re-watch The Princess and the Frog (yes, the Disney movie). Tiana didn’t just dream about the restaurant—she saved, worked, and calculated every cent. That’s the net worth mindset. Every time you skip a takeout meal and cook instead, you’re adding to your assets. Every time you negotiate a lower interest rate, you’re subtracting from liabilities.
 What’s Your True Financial Standing: Calculating Net Worth
Fun fact: The average net worth of a U.S. household under 35 is about $76,000—but that’s skewed by a few big numbers. The median is closer to $14,000. Don’t compare your chapter one to someone else’s chapter twenty.
The Final Number: A Reflection for Daily Life
So, what does it all mean as you sip your coffee and scroll through Pinterest? Net worth is a compass, not a destination. It doesn’t tell you if you’re happy or kind. It doesn’t measure your late-night conversations or the laughter you share with friends.
But it does show you if you’re building a life that supports those things. Assets minus liabilities isn’t cold math—it’s cold truth. The goal isn’t a massive number; it’s a number that lets you sleep at night, say yes to a spontaneous road trip, and smile at your bank statement as you delete an unused subscription.
Track it. Play with it. Give it a ridiculous nickname like “Netty Worth” if it helps. Because at the end of the day, your net worth is just the story of your priorities told in numbers. And you’re the author.
