Definition Of Net Worth Assets Minus Liabilities

So, let’s talk about net worth. You’ve heard the term, right? It sounds like something a billionaire on a yacht throws around. But here’s the secret: it’s actually the world’s...
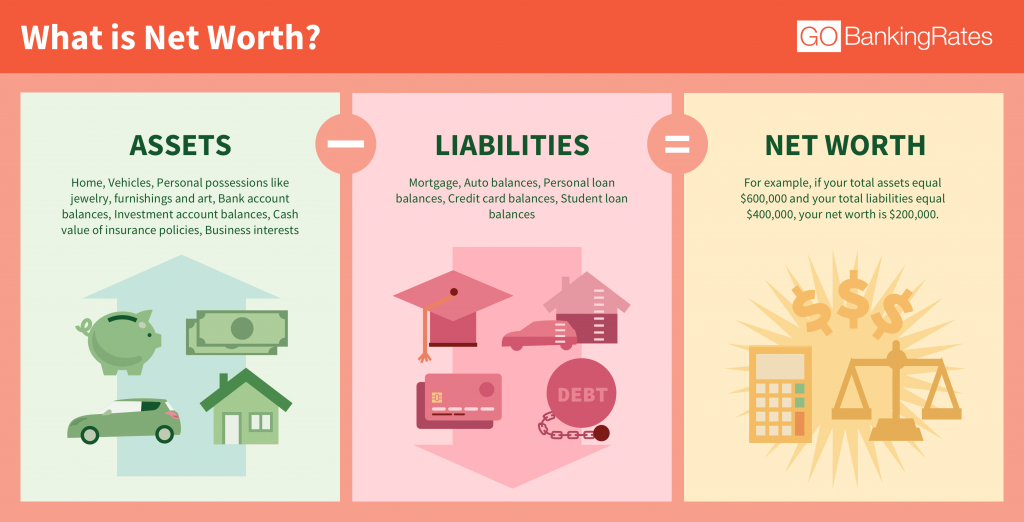
So, let’s talk about net worth. You’ve heard the term, right? It sounds like something a billionaire on a yacht throws around. But here’s the secret: it’s actually the world’s simplest math problem.
Seriously. If you can subtract one number from another, you can calculate your net worth. It’s not magic. It’s just assets minus liabilities.
What Are Assets? (The Fun Stuff You Own)
Assets are everything you own that has value. And no, that Funko Pop collection on your shelf? Yeah, that counts, at least in spirit. We’re talking about your checking account, your 401(k), that beat-up car that still runs, and maybe even the cash under your mattress.
Must Read
It’s the stuff that puts money in your pocket—or could, if you sold it. For example, your house is a big asset (hopefully). Your emergency fund? Definite asset. Even that vintage guitar you never learned to play? Asset, my friend.
The key is to be honest. Nobody is judging you for including your laptop. Except maybe your accountant. But let’s not worry about them right now.
What Are Liabilities? (The Dracula Sucking Your Wallet)
Liabilities are the opposite of fun. They are what you owe. Student loans, credit card debt, that car loan, your mortgage, and the $20 you borrowed from your buddy for pizza last week. Liabilities are the things that drain your financial blood.
Think of them as financial vampires. They suck the value right out of your assets. That car you love? If you still owe $15,000 on it, the liability is sitting right there, grinning.
It’s not bad to have liabilities. We all have them. But you can’t pretend they don’t exist. The math won’t let you. And math is a cold, heartless friend.
 Net asset value or NAV formula of an investment company is the company
The Magic Formula: Assets Minus Liabilities
Here is where the rubber meets the road. Take a deep breath. Write down your total assets on a napkin. Now write down your total liabilities underneath it. Ready?
Subtract the liabilities from the assets. That number—positive, negative, or zero—is your net worth. That’s it. No secret handshake involved. You just became a personal finance expert.
If the number is positive, congrats! You’re technically in the green. If it’s negative, don’t panic. Most people under 40 are in the red. It’s like the financial version of having a bad hair day. It’ll pass.
Why Does This Even Matter?
Because net worth is the true scorecard of your financial life. Not your income. Not your Instagram-worthy vacation. Nope. Just this one cold, hard number. It cuts through the noise. It tells you if you’re building a mountain or digging a hole.
Think of it like a video game. Assets are your power-ups. Liabilities are the monsters. You want more power-ups and fewer monsters. Net worth is simply your final score at the end of the level.
It’s a reality check, but a fun reality check. Like when you realize your coffee habit costs more than your car payment. Wait, is that fun? Maybe not. But it’s honest.
 Outside Net Worth Formula at Heather Richards blog
Common Myths That Will Make You Giggle
Myth one: “My house is worth a million, so I’m rich.” Hold on, speed racer. How much do you still owe the bank? If you owe $950,000 on a $1,000,000 house, your home equity asset is only $50,000. That’s still good, but it ain’t yacht money.
Myth two: “I have no debt, so my net worth must be huge.” Cute, but if your only asset is a half-eaten bag of chips and a library card, your net worth is essentially zero. Sorry, buddy. Debt-free is great, but zero assets means you’re still broke, just without the drama.
Myth three: “My net worth defines my worth as a human.” Pfft, no. Your net worth doesn’t measure your kindness, your humor, or your ability to parallel park. It’s just a number. A useful number, but still just a number.
A Quick Example (Because We Love Examples)
Imagine you have: Assets: $10,000 in savings, a $5,000 car (paid off), and a $500 laptop. Total assets = $15,500. Liabilities: $8,000 in student loans, $2,000 on a credit card. Total liabilities = $10,000.
Now do the math: $15,500 – $10,000 = $5,500 net worth. Not bad! You’re basically a mini tycoon. You could buy 550 fancy lattes. Or, you know, save for retirement.
If the numbers flipped? Let’s say liabilities were $18,000. Then your net worth is negative $2,500. That’s okay! The important thing is you now have a target. You know you need to slay some debt.
 What’s Your True Financial Standing: Calculating Net Worth
How to Boost That Baby (Without Selling a Kidney)
Two levers: increase assets and decrease liabilities. That’s the whole game. Pay off that credit card (high-interest debt is a jerk). Stuff some cash into a savings account. Buy a stock or two. Or just stop buying avocado toast every single day—no judgment.
Small moves add up. Paying an extra $50 toward a loan is like giving your future self a tiny high-five. Eventually, your assets outrun your liabilities, and your net worth starts looking like a racehorse.
And hey, if you’re feeling fancy, invest in things that grow. Real estate, index funds, or even a side hustle. But don’t chase get-rich-quick schemes. Unless you enjoy losing money. In which case, keep scrolling.
One Last Thing (Because I’m Winded)
Net worth is a snapshot, not a life sentence. It changes every day. You buy a coffee? It dips. You get a paycheck? It jumps. Don’t obsess over it. Check it once a month, like you check your weird neighbor’s holiday lights.
The real magic? Understanding the definition. Once you get that assets minus liabilities is the core of everything, you stop being intimidated by money talk. You become the person who quietly nods at dinner parties when someone mentions “wealth building.”
Now go ahead. Grab a napkin (or an app, if you’re fancy). Calculate your net worth. It might be scary. It might be awesome. But now you know the secret. And the secret is always just a little subtraction.
