Difference Between Net Worth And Liquid Net Worth

So, you’ve heard people toss around the words “net worth” and “liquid net worth” like they’re the same thing, right? Wrong! Think of them as cousins—one is the rockstar who ow...
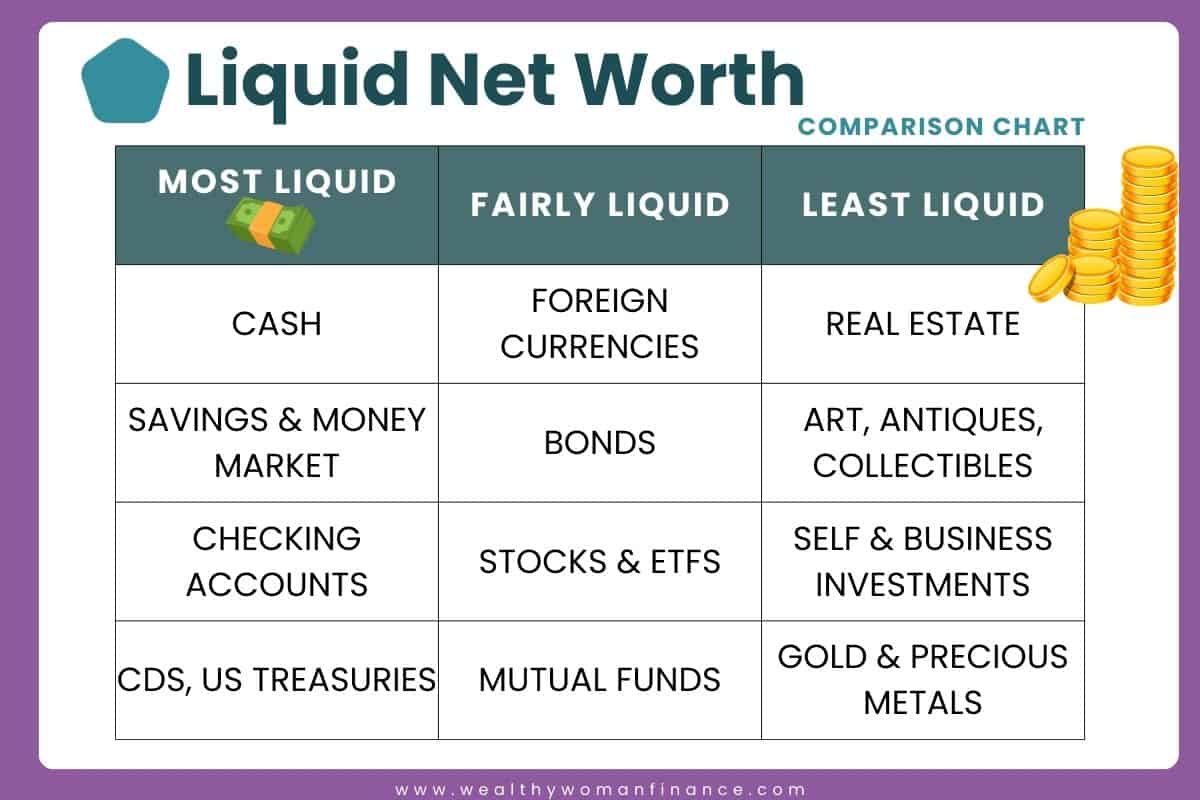
So, you’ve heard people toss around the words “net worth” and “liquid net worth” like they’re the same thing, right? Wrong! Think of them as cousins—one is the rockstar who owns a mansion, and the other is the practical sibling who actually carries cash. Let’s break this down without making your brain hurt, I promise.
What’s Net Worth? The “Total Picture” Number
Your net worth is basically your financial scoreboard. It’s everything you own minus everything you owe. Simple math: add up your house, car, retirement accounts, that dusty coin collection, and your savings, then subtract your mortgage, student loans, and credit card debt.
If that number is positive, you’re winning. If it’s negative… well, you’re not alone, but let’s focus on the positive vibes here. Net worth gives you the big-picture of your wealth, like a panoramic photo of your finances.
Must Read
Here’s the catch: net worth includes things you can’t easily turn into cash. That’s why it’s the “theoretical” wealth. Kind of like saying you’re a millionaire because you own a painting—but you can’t pay for pizza with a Monet.
Enter Liquid Net Worth: The “Get-It-Now” Number
Liquid net worth is the cooler, more practical sibling. It only counts assets you can convert to cash quickly—usually within days—without losing value. We’re talking checking accounts, savings, stocks, bonds, and maybe a vintage Beanie Baby collection if you find a sucker… I mean collector.
So, if net worth is your total wealth, liquid net worth is your “emergency fund” wealth. It’s the money you could actually use to pay a sudden hospital bill, fix your car, or buy that spontaneous flight to Bali (budget permitting).
Liquid net worth ignores your house, your car, your retirement accounts (if you’re under 59½), and that signed guitar you swear is worth thousands. Why? Because selling those takes time, fees, or tears.
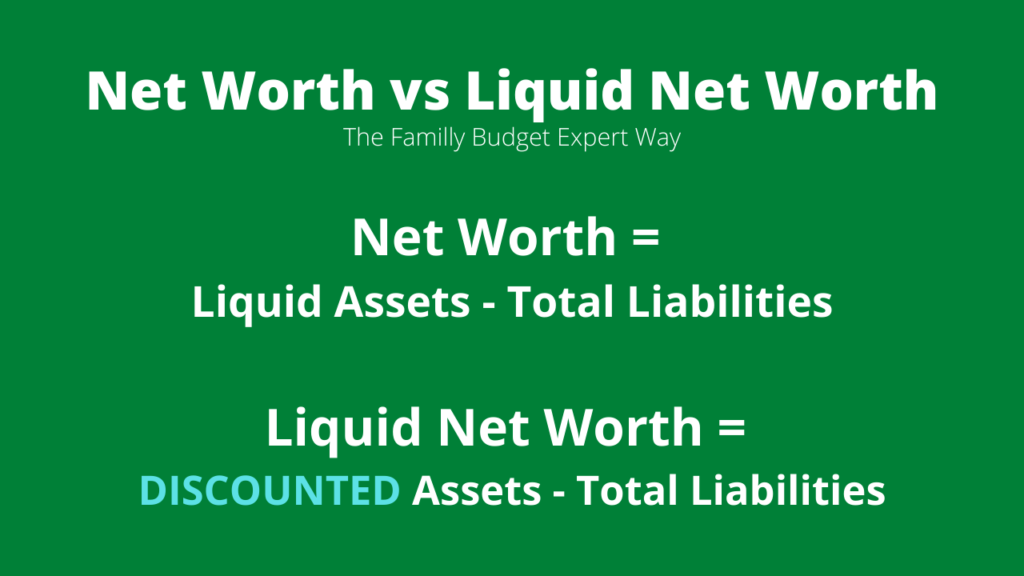 Liquid Net Worth: Your key to staying out of debt - Family Budget Services
A Real-Life Example: Meet Dave
Dave has a net worth of $500,000—a $400,000 house, a $50,000 car (paid off), and $50,000 in a retirement account. Go Dave! But his liquid net worth? A mere $5,000 in his checking account.
So if Dave loses his job tomorrow, he can’t use his house to buy groceries. He could sell his car, but then he has to walk everywhere. That’s why liquid net worth matters more for survival. Dave looks rich on paper but might struggle to pay rent for three months.
Why the Difference Matters (and Why It’s Kinda Funny)
Imagine bragging about your net worth at a party. “I’m worth a million bucks!” But if all that money is tied up in your house and a vintage wine collection, you’re technically drinking your wealth. One hailstorm or a cork gone bad, and poof—you’re broke.
On the flip side, someone with a modest net worth but high liquid net worth is the quiet genius. They have cash ready for opportunities—like investing during a market dip or buying a friend’s used couch for $20. They’re the financial ninjas you never see coming.
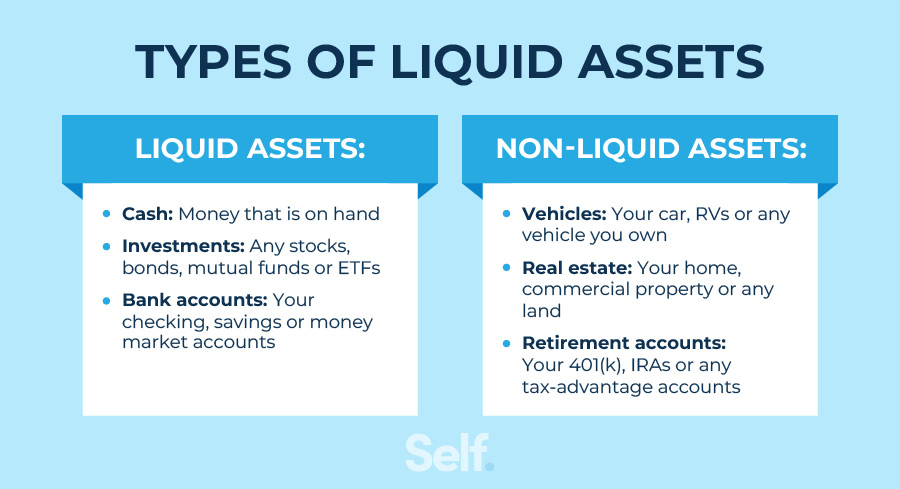 Liquid Assets
The joke? Most people focus on net worth to feel rich. But smart people focus on liquid net worth to actually be prepared. It’s like having a big, beautiful lawn (net worth) versus having a working faucet in your kitchen (liquid net worth). Both are nice, but one keeps you hydrated.
How to Boost Your Liquid Net Worth (Without Selling a Kidney)
First, keep 3–6 months of expenses in a high-yield savings account. That’s your “don’t touch unless the house is on fire” money. Second, pay off high-interest debt—credit card debt eats your liquidity like a hungry raccoon.
Third, consider diversifying. Instead of putting all your extra cash into a house down payment, stash some in a brokerage account. Stocks and ETFs are liquid—and they don’t need a plumber when the sink breaks.
Finally, don’t forget to laugh at yourself. We’ve all been the “Dave” at some point—owning a fancy espresso machine but forgetting to pay for the beans. It’s okay. Financial growth is a marathon, not a sprint, and you’re already reading this, which means you’re winning.
 What is Liquid Net Worth & Why Should You Care? - Educator FI
The Uplifting Conclusion: You’ve Got This!
So, to sum up: net worth is your financial whole, like a giant, slightly dusty library of wealth. Liquid net worth is the spark notes version—the money you can actually use to buy tacos tomorrow.
The good news? You don’t have to choose one over the other. Aim for a big net worth and a healthy liquid stash. Think of it as having a mansion with a fully stocked fridge. You’re the CEO of your own life, and you get to decide which number matters most right now.
And remember: money is just a tool. It can’t buy happiness, but it can buy you the peace of mind that comes from knowing you could handle a surprise bill without panic. So go ahead, check your numbers, smile, and maybe treat yourself to a coffee. (Cash only, please—your liquid net worth says hello.)
You’re richer than you think—especially when you count your kindness, creativity, and ability to laugh at financial jargon. Now go be awesome.
