Do Retirement Accounts Count Towards Net Worth

Alright, let’s cut through the financial jargon fog and get real. You’ve probably heard the term “net worth” thrown around like confetti at a billionaire’s birthday party. But...
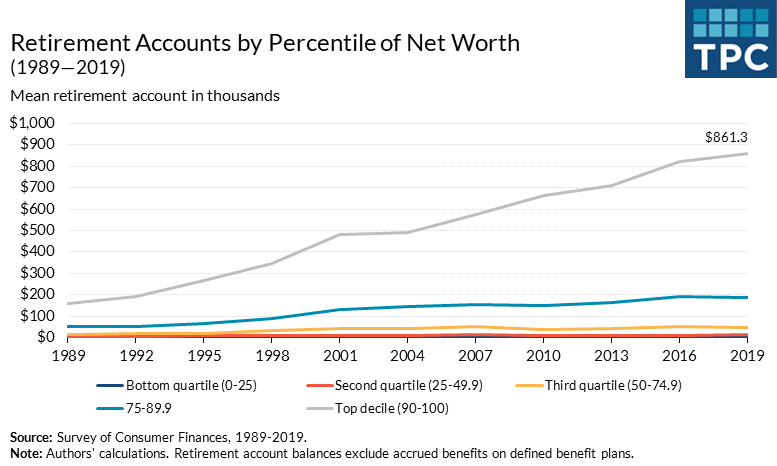
Alright, let’s cut through the financial jargon fog and get real. You’ve probably heard the term “net worth” thrown around like confetti at a billionaire’s birthday party. But does that dusty old 401(k) from your first job actually count? Short answer: yes, absolutely. But let’s unpack that, because there’s a fun twist.
Think of your net worth as your financial report card. It’s everything you own (your assets) minus everything you owe (your liabilities). And your retirement accounts—like a 401(k), IRA, or Roth IRA—are definitely assets. They’re money you’ve squirreled away for future you, so they absolutely bump up that number.
Here’s the hilarious part: your net worth doesn’t care if you can touch the cash today. That money is yours—it’s just wearing a “Do Not Open Until 59½” sign. So when you’re calculating your net worth, you throw the current balance in there, penalties and taxes be darned. It’s like counting a gift card in your wallet—you can’t spend it on pizza right now, but it’s still value.
Must Read
Why Do People Get Confused?
Because of “liquidity.” Ooh, fancy word! Liquidity just means how fast you can turn something into cash without losing your shirt. Your checking account? Super liquid—it’s basically a cash water pistol. Your retirement account? More like a savings glacier—move it too early, and you get melted by penalties and taxes.
But here’s the kicker: net worth isn’t a liquidity score. It’s a wealth snapshot. Imagine taking a photo of your financial life—your house, your car, your vintage Beanie Baby collection—and yes, that IRA balance. The photo doesn’t ask, “But can you buy groceries with it right now?” It just says, “This is what you’ve built.” So count it.
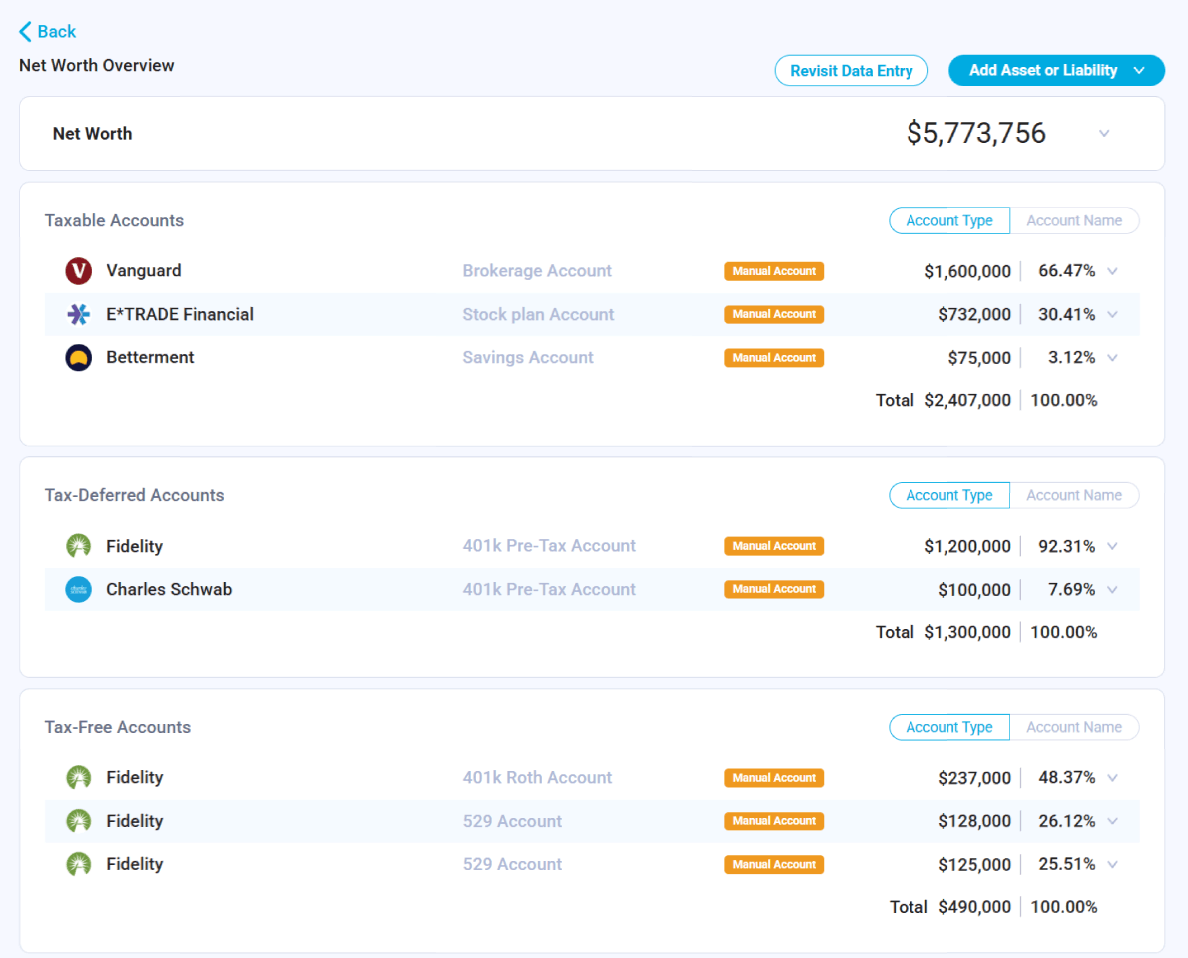 Liquid Net Worth: What It Is, What Counts, and Why It Matters for Early
A common myth is that you should only count money you can access immediately. That’s like saying your house doesn’t count until you sell it. Nonsense! Your retirement accounts are value, even if they’re locked in a retirement vault. And hey, turning 59½ isn’t that far off… unless you’re 25, in which case, ouch, that’s 34 years of waiting. But still, it’s yours.
How to Handle the Tax Twist
Here’s where we get a little accountant-y, but I promise it’s painless. For traditional retirement accounts (like a 401(k) or traditional IRA), you’ll owe income tax when you withdraw. So some smarty-pants advisors suggest subtracting a rough tax estimate from the balance when calculating net worth. It’s a good idea—but most people just use the full balance for simplicity.
For Roth accounts? No tax later, baby! The full balance is yours, penalty-free after age 59½. So count every single cent. That’s like finding a $20 bill in a coat you haven’t worn since winter—pure bonus.
 The Retirement Café: April 2015
So, do retirement accounts count? Yes, yes, and yes. They don’t vanish into a black hole just because you can’t tap them today. In fact, for many people, retirement accounts are the biggest chunk of their net worth. If you left them out, you’d be lying to yourself about how well you’re doing. And we don’t lie to our financial mirrors—that’s bad juju.
Why This Matters for Your Smile
Here’s the uplifting part you didn’t know you needed. When you look at your net worth and see that retirement account number, you’re seeing proof of your future self’s security. That number isn’t just digits—it’s you, time-traveling to pay for your golden years. It’s the money you’ll use for books, beach trips, or finally buying that giant inflatable dinosaur for your grandkids.
 Closing Ira Account For Elderly – NYYSC
And let’s be honest: net worth can feel like a scary scoreboard. But when you include your retirement accounts, it becomes a hopeful scoreboard. That 401(k) from a job you hated? It’s still working for you. That IRA you started with just $50 a month? It’s now a tiny money tree in a forest of bigger trees. You’re not broke—you’re just rich in a delayed-gratification way.
So go ahead, calculate your net worth—retirement accounts and all. Watch that number grow, even if you have to wait a few decades to party with it. Think of it like aging a fine wine or waiting for a pizza delivery that takes 30 years. The anticipation makes it sweeter.
And remember: your net worth isn’t about what you can grab today—it’s about what you’ve built for every tomorrow. Including the tomorrows where you’re sipping coffee on a porch, wearing socks with sandals, and laughing at how smart your younger self was. You’ve got this. Now go count your coins—retirement ones, too.
