Does Fafsa Net Worth Of Investments Include 401k

So, Does the FAFSA Count Your 401(k)? Let's Dig Into This Money Mystery. Okay, let's be real. Filling out the FAFSA feels like decoding a secret language, right? You’re typin...

So, Does the FAFSA Count Your 401(k)? Let's Dig Into This Money Mystery.
Okay, let's be real. Filling out the FAFSA feels like decoding a secret language, right? You’re typing in numbers, crossing your fingers, and hoping the government doesn't think you're secretly a millionaire. One of the biggest head-scratchers is always: what about our retirement savings?
You’ve been working hard, stashing cash in your 401(k) for decades. Now you’re looking at sending a kid to college, and you're probably wondering, “Will they count that?” It’s a fair question, and the answer is actually pretty great news. Let’s unpack this, nice and slow.
The Big, Beautiful Truth: Your 401(k) is (Mostly) Invisible to the FAFSA
Here’s the short, sweet, and huge relief: No, the FAFSA does not ask you to report the net worth of your 401(k) or any other qualified retirement account. That’s right. All those years of saving? The algorithm won't see a penny of it as an "asset" you can use for tuition.
Must Read
Think of it like this: you’re a pirate, and your 401(k) is your secret treasure chest buried on a deserted island. The FAFSA is just a friendly guide who gives you directions to the mainland—they know the treasure is out there, but they’re not allowed to dig it up. They consider it "off-limits" because the government wants you to save for retirement.
This is a massive difference from other assets like a second home or a brokerage account. Why is that cool? Because it means you don’t have to choose between your future self and your kid’s next semester.
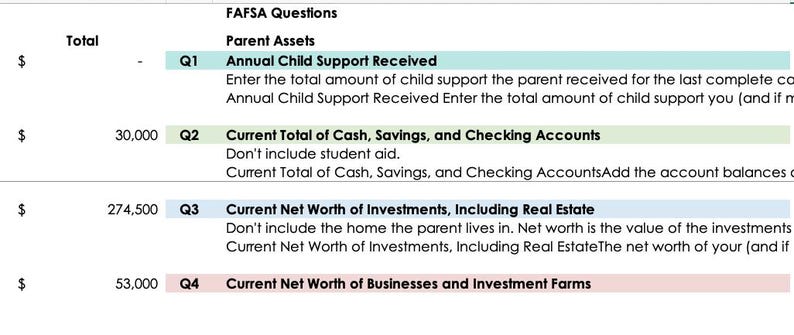 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
But Wait, What About IRAs and 529 Plans?
You might be thinking, “Okay, cool. But what about my IRA?” Same deal. Traditional IRAs and Roth IRAs are also exempt from being reported as assets on the FAFSA. The government is basically saying, “We see your retirement egg, but we’re not going to count it in your ‘nest egg’ for college costs.”
Now, here’s where it gets a little trickier: a 529 plan. Unlike your 401(k), a 529 plan is absolutely counted as a parent asset if you own it. But guess what? It’s treated very generously. It’s considered a savings tool, not a retirement tool. So while it does show up, it doesn’t hurt you nearly as much as a regular bank account would.
The Fun Comparison: It’s Like a Cheat Code for Life
Imagine you’re playing a video game. Your 401(k) is that super-powerful magic sword you found early on. The game’s main enemy—college costs—can see your health bar and your gold coins. But that magic sword? Invisible. You get to keep its power without it affecting your battle rating.
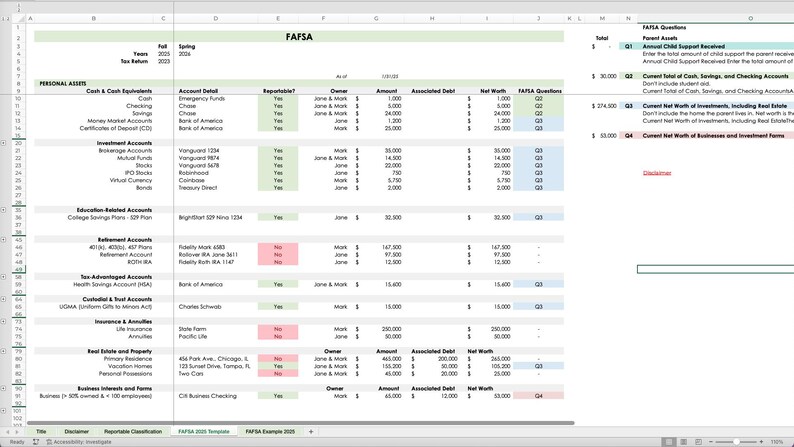 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
Or picture this: you’re baking a cake (college finances). The FAFSA is the recipe. Your 401(k) is the secret ingredient that makes the cake taste way better, but the recipe doesn't tell you to add it. You just get to enjoy the bonus. Isn’t that a beautiful thing?
A Quick Reality Check: Income is the Real Boss Battle
Now, don’t get too carried away with the victory dance just yet. While your 401(k) balance is safe, the income you earned that you put into the 401(k) is not. The FAFSA looks at your adjusted gross income from two years ago. So, if you made a ton of money and contributed heavily to your 401(k), that income still counts against you in the aid formula.
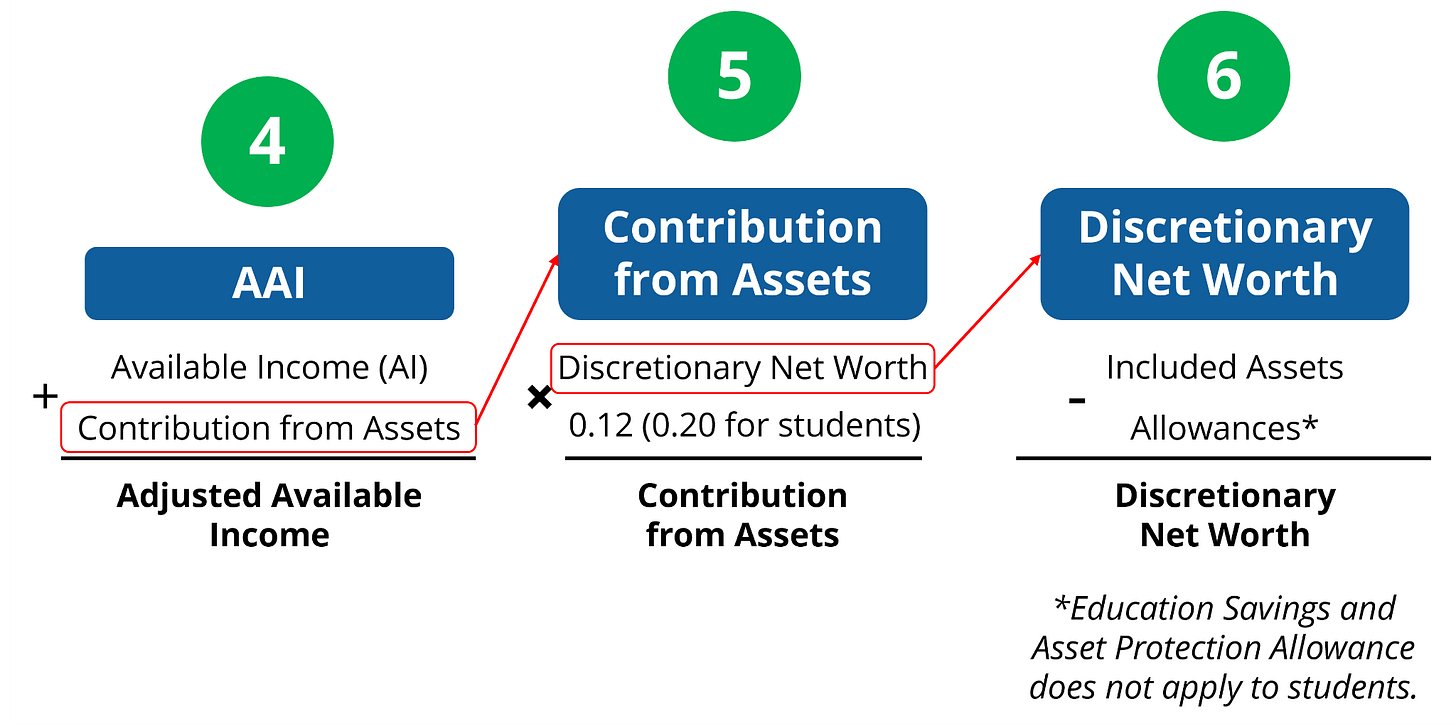 Your Complete Guide to FAFSA | Money Guy
But here’s the silver lining: a $20,000 contribution to your 401(k) lowers your reported income for that year. And since the FAFSA looks at income from two years prior, a big contribution can actually reduce your expected family contribution (EFC) for that specific year. It’s a little loophole, but it’s a real one.
The Final Takeaway: Keep Saving, Keep Chill
So, don’t stress. Your 401(k) is your financial fortress, and the FAFSA is not coming with a battering ram. Keep contributing, keep building that nest egg, and know that the government is, for once, on your side about this.
The takeaway is simple: Your retirement is your priority, and the college financial aid system agrees. So take a deep breath, pour a cup of coffee, and keep doing what you’re doing. You’ve got this. And your 401(k) is quietly cheering you on from its invisible, tax-advantaged hideout.
