Does Liquid Net Worth Include Retirement Accounts

So, you’re staring at your bank account, wondering if you’re secretly a millionaire or just a human with a 401(k) and a dream. The question pops up: Does liquid net worth incl...
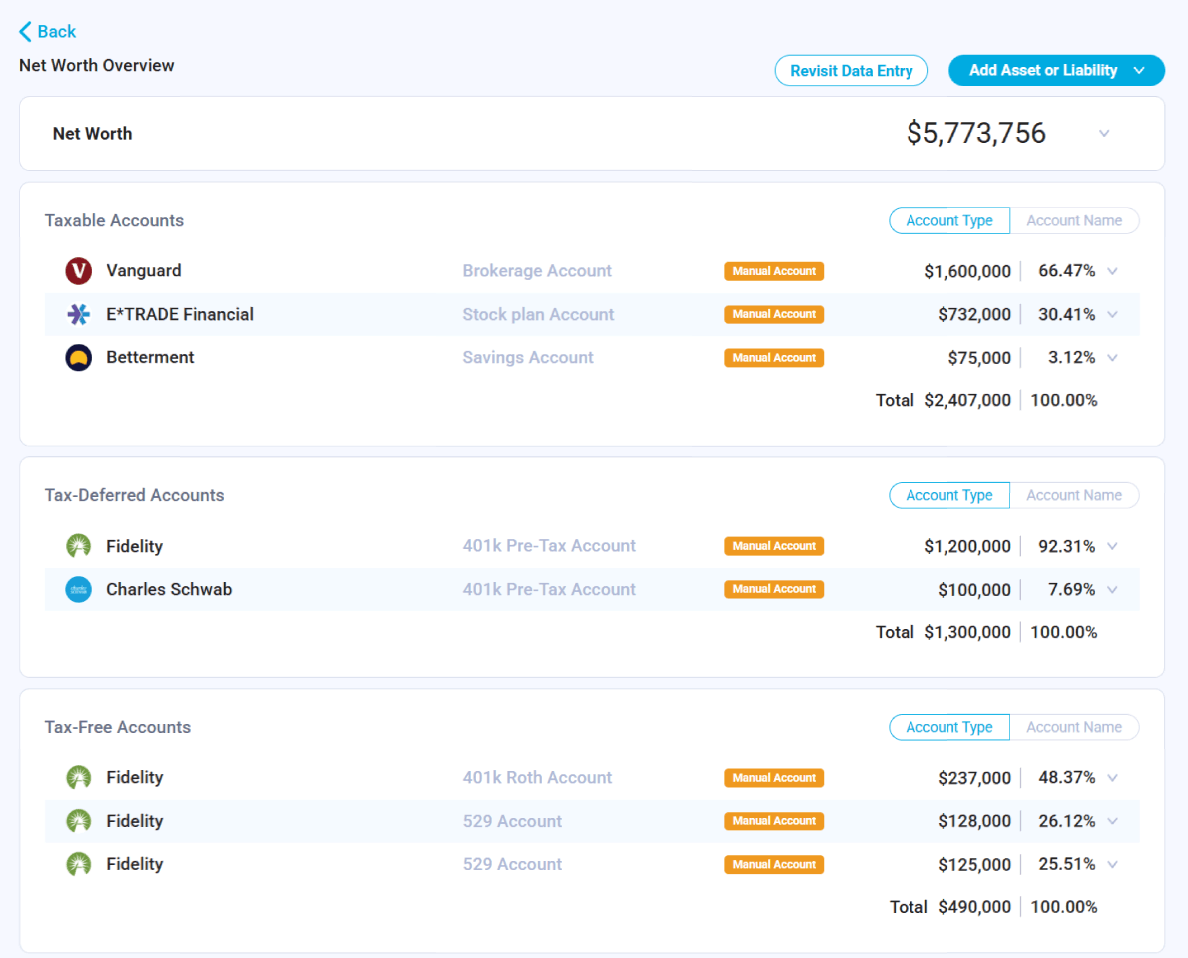
So, you’re staring at your bank account, wondering if you’re secretly a millionaire or just a human with a 401(k) and a dream. The question pops up: Does liquid net worth include retirement accounts? Let’s be real—nothing kills a coffee buzz faster than financial jargon.
First, let’s rip off the bandage: No, retirement accounts are not liquid net worth. Sorry to burst your golden-age bubble. Liquid net worth is the cash you can grab right now without selling a kidney or crying to the IRS.
What Exactly Is Liquid Net Worth?
Think of liquid net worth as the “escape fund.” It’s the money you could turn into spendable cash within a day or two. We’re talking checking accounts, savings accounts, money market funds, and stocks you’d sell in a snap.
Must Read
Retirement accounts like your 401(k) or IRA? They’re more like a dragon’s hoard—impressive, but you’ll get burned if you touch them early. The IRS charges a 10% penalty plus taxes for early withdrawals before age 59½. That’s like paying a troll toll just to get your own gold.
But Wait—What About Roth IRAs?
Ah, the cheeky exception! With a Roth IRA, you can pull out your contributions (not earnings) anytime, tax-free and penalty-free. That part is technically liquid. But the rest of that account? Nope—it’s still trapped until retirement, unless you want to hand Uncle Sam a slice of your pie.
So, your Roth IRA contributions are liquid-ish, but don’t go planning a yacht purchase on them. You earned that money, but the government is a clingy party guest.
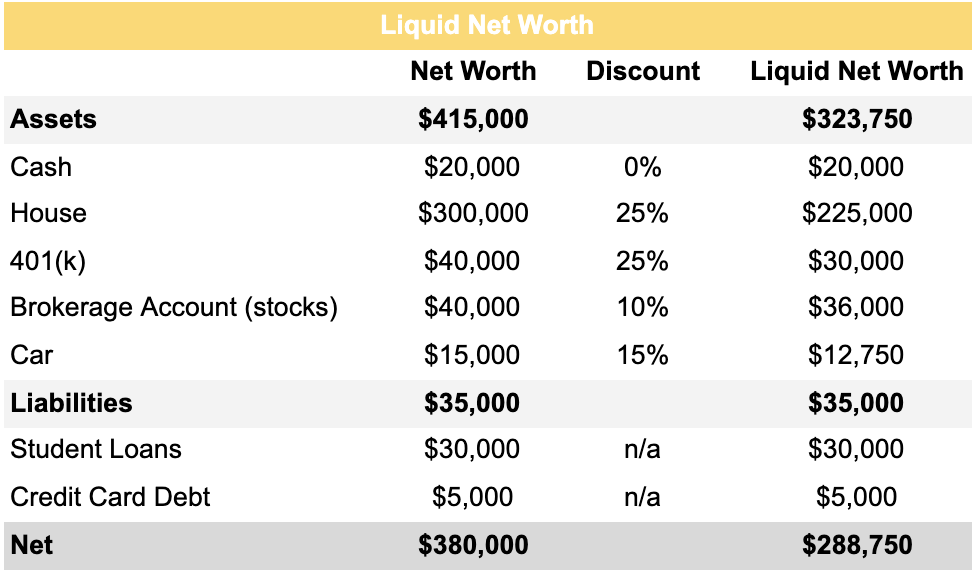 What is Liquid Net Worth and How to Calculate Yours
Why Does This Matter?
Imagine you suddenly need $10,000 for a medical emergency or a screaming match with your car mechanic. If all your wealth is locked in a 401(k), you’re basically a paper billionaire who can’t afford a pizza. Liquid net worth is your financial fire extinguisher—not your slow-burning retirement candle.
Here’s a jaw-dropper: a 2023 survey found that 37% of Americans couldn’t cover a $400 emergency with cash. Meanwhile, the average 401(k) balance is over $100,000. So yes, plenty of people are “rich” on paper but one medical bill away from a panic attack.
The Math of Illiquidity
Let’s be brutally honest: your retirement account is not a piggy bank. It’s more like a time capsule—you can’t open it without a jackhammer and a tax form. If you include your 401(k) in liquid net worth, you’re lying to yourself harder than a dieter hiding a donut.
Financial planners use a simple rule: Liquid net worth = Total assets you can turn into cash within 24 hours minus debts. By that definition, your retirement stash is sleeping beauty—lovely to look at, but not waking up for decades.
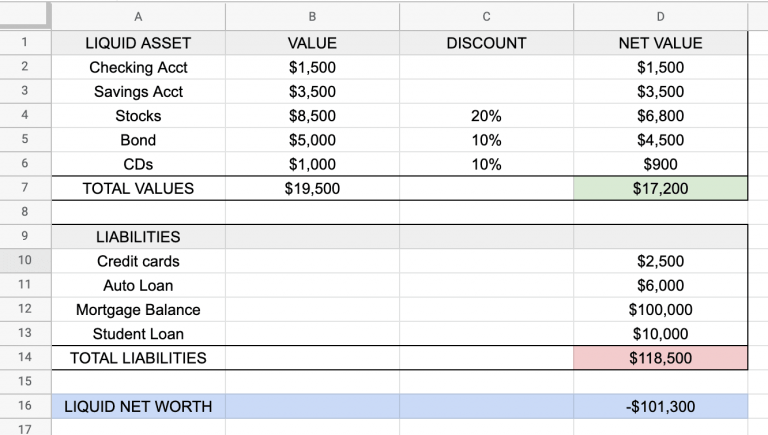 Liquid Net Worth: Its Definition, Calculation, and Purpose For Your
But Why Do People Get Confused?
Because “net worth” sounds like a magic number that defines your life. You hear celebrities with “$50 million net worth” and assume their liquid cash matches. Spoiler: Elon Musk’s net worth is mostly Tesla stock—he can’t walk into a bank and withdraw $200 billion. Even the rich are playing pretend with liquidity.
Here’s a fun fact: in 2021, a Reddit user famously claimed they were a “millionaire” thanks to a 401(k)—and then couldn’t afford rent. The internet roasted them like a bad accountant. Moral of the story: Liquidity is king, but retirement accounts are the kingdom’s forbidden attic.
The One Exception That Proves the Rule
If you’re over 59½, retirement accounts suddenly become gorgeously liquid. No penalty! At that point, you can withdraw freely, and they join your liquid net worth party. But until then, they’re just fantastic, tax-advantaged handcuffs.
Think of it this way: a 30-year-old with $500,000 in a 401(k) has zero liquid net worth from that account. A 65-year-old with the same amount? They have a half-million in liquid assets. Age is the secret sauce.
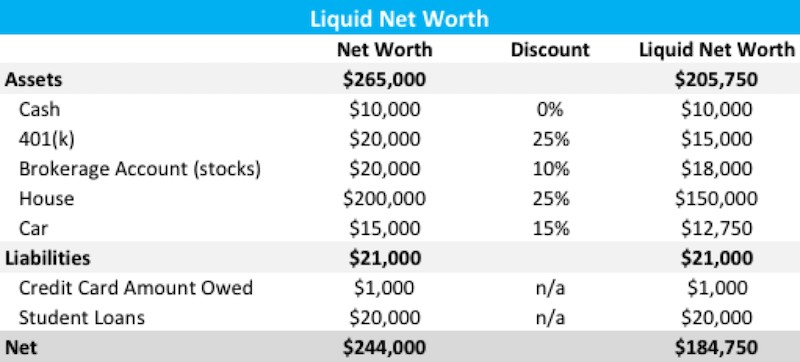 Liquid Net Worth: Definition And Calculation – VLIB
So, What Should You Track?
Track both: total net worth (retirement + everything) for long-term bragging rights. Liquid net worth for the “how fast can I run?” question. If you ever need to bribe a snowplow driver or flee a zombie apocalypse, that’s liquid net worth talking.
And here’s the kicker: experts say you should aim for 3–6 months of living expenses in truly liquid assets. That’s your “oh crap” fund—separate from retirement accounts. Anything more is just showing off.
The Bottom Line (No Pun Intended)
Does liquid net worth include retirement accounts? Only if you’ve hit retirement age or you’re okay with IRS penalties that feel like a personal attack. For most of us, those accounts are glorious, long-term hostages—not liquid cash.
So go ahead, check your liquid net worth. If it’s lower than you hoped, don’t panic. Just remember: being “rich in retirement” is great, but having cash now means you can actually buy that coffee you’re sipping. Cheers to liquidity—even if it’s just $37.24.
