Fafsa Current Net Worth Of Investments

Hey there, future college grad! Let’s talk about something that sounds as fun as a root canal: the FAFSA and your current net worth of investments. I know, I know—your eyes ju...

Hey there, future college grad! Let’s talk about something that sounds as fun as a root canal: the FAFSA and your current net worth of investments. I know, I know—your eyes just glazed over. But stick with me. We’re going to make this as painless as possible, maybe even a little funny. Think of it as financial therapy with snacks.
What Even Is “Current Net Worth of Investments”?
First, the FAFSA (Free Application for Federal Student Aid) wants to know everything about your money. It’s like that nosy aunt at Thanksgiving who asks about your salary. Specifically, it asks for your “current net worth of investments.” That’s a fancy way of saying: “How much money do you have in stocks, bonds, real estate, and other stuff that isn’t a bank account?”
It does not include your retirement accounts (like a 401k or IRA). Why? Because the government figures you need that money for, well, not being a broke senior citizen. Phew, right? So your 401k is safe from the prying eyes of the FAFSA. You can keep pretending you’ll retire at 35.
Must Read
Also, it doesn’t include the value of your family home or your car. Unless you’re driving a Ferrari and living in a castle, you’re fine. The FAFSA assumes you need a roof over your head and wheels to get to class, not to pay tuition.
The “Fun” Math (Don’t Panic)
Now, here’s where we get to the math. But don’t run away yet—I promise it’s simpler than figuring out why your roommate always steals your milk. You just add up the current market value of your investments. So, if you have $500 in a stock you bought on a whim, that counts. If you have $2,000 in a savings account earning 0.01% interest, that’s cash, not an investment.
Wait—what about that vintage Pokemon card collection? Sorry, unless you’re selling them on eBay right now, the FAFSA doesn’t care about your holographic Charizard. Investments are things like brokerage accounts, trust funds, rental properties, and mutual funds. Basically, anything that might make you look “rich” to a financial aid officer.
And here’s a joke for you: What’s the difference between a student and an investment? One is volatile, and the other is… well, stocks. (I’ll see myself out.)
 The Surprising FAFSA/SAI and Roth IRA Conflict that Almost Sabotaged
Why Does the FAFSA Even Care?
Great question! The FAFSA uses your net worth to calculate your Student Aid Index (SAI). That’s a number that determines how much financial aid you qualify for. Simply put: the more investments you have, the less “need” you have. The government assumes you can sell your stocks to pay for tuition instead of asking Uncle Sam for a grant.
But here’s the kicker—your parents’ investments matter too, if you’re a dependent student. So if your mom has a fat 401k, you’re probably okay (because that’s excluded). But if she has a second house in the Bahamas? Yeah, that counts. Sorry, no spring break mansion for you.
Pro tip: Don’t hide your investments. The FAFSA can verify everything through a tax return. Plus, lying is a bad look—and it can get you fined. So be honest, but also take advantage of the exclusions. Your 401k is your best friend.
How to Report It Without Crying
Start by logging into your brokerage account—if you have one. Look for the “account value” or “current balance.” That number is your net worth for that account. Add up all your accounts (checking, savings, stocks). Then, subtract any debt tied to those investments (like a margin loan). The result is your current net worth.
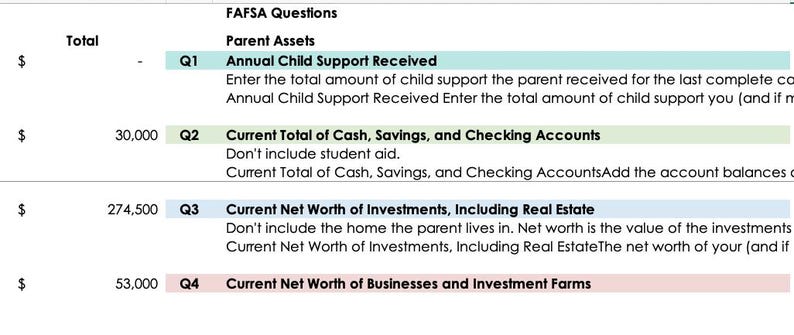 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
If you’re a normal human and have, like, $200 in a Robinhood account, just report $200. The FAFSA doesn’t penalize you for being a small-time investor. It only gets picky when you’re rolling in dough—like, “I own three Starbucks franchises” level of dough.
Also, don’t stress if you have negative net worth (more debt than assets). That’s actually good for aid purposes! You just report it as zero or a negative number. The FAFSA won’t laugh at you—it will give you more money. Silver linings!
A Few More Laughs (and a Reality Check)
Still worried? Let’s put it in perspective: the average college student has a net worth that’s less than the cost of a used Honda Civic. Most of you probably have zero investments, which means your net worth is basically a can of soup and a dream. That’s fine! The FAFSA expects that. It’s designed for people who don’t have trust funds named after their childhood pets.
One more joke: Why did the FAFSA form break up with the investment account? Because the relationship was too net for the form to handle. (Okay, I’ll stop now.)
 Do we really need to disclose true net worth ? : r/FAFSA
If you’re still confused, just remember: report what you have, exclude retirement accounts and your primary home, and don’t try to outsmart the government. They have algorithms for that.
Your Uplifting Conclusion (Right Here)
Alright, let’s wrap this up with a smile. The FAFSA might feel like a snooze-fest, but it’s actually a bridge to your future. Every number you plug in, even the scary-looking net worth of investments, is just a step toward getting the help you need. You’re not “being fined” for having a little savings—you’re being honest. And honesty, my friend, is the best policy when free money is on the table.
So take a deep breath. Your current net worth doesn’t define you. It’s just a snapshot of a moment in time, like a goofy photo from high school—awkward, but not permanent. Whether you’re reporting $5 or $50,000, you’re doing the smart thing by applying for aid. And that makes you a financial superhero. You’ve got this.
Now go fill out that form, maybe treat yourself to a pizza afterward, and remember: in a few years, you’ll be wealthy enough to laugh about this. Probably. But until then, keep on keeping on. You’re going to college, for crying out loud—you’ve already won half the battle.
