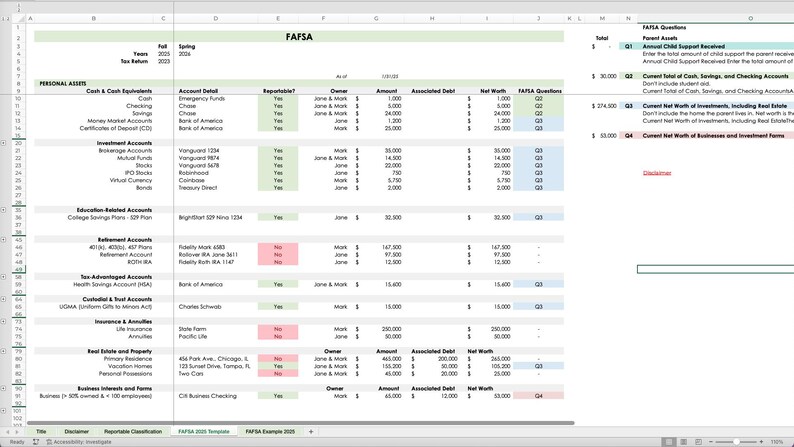
Fafsa Current Net Worth Of Investments Including Real Estate

So there I was, staring at my friend Jenna’s face, frozen mid-syndrome on our Zoom call. She was twenty-three, living in a tiny apartment, and had just inherited her grandmoth...
So there I was, staring at my friend Jenna’s face, frozen mid-syndrome on our Zoom call. She was twenty-three, living in a tiny apartment, and had just inherited her grandmother’s old cottage in Vermont. “I’m terrified to fill out the FAFSA,” she whispered, as if the federal government was listening through her webcam. “Do I have to report the cottage? It smells like mothballs and old dreams.” I knew exactly what she was feeling. That weird, sinking panic when you realize your definition of “investment” might not match the government’s definition.
The “Wait, That’s an Investment?” Moment
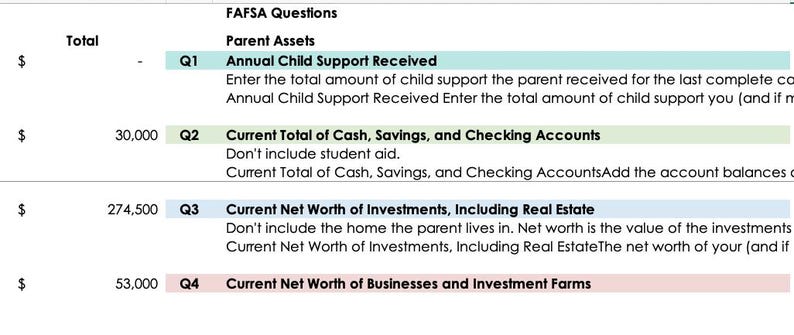
Let’s cut straight to it: FAFSA absolutely cares about the current net worth of your investments, including real estate. And yes, that includes Jenna’s mothball cottage. The Department of Education isn’t trying to be nosy—okay, they kind of are—but they use this number to figure out how much your family can actually contribute to college. Think of it as a financial honesty box, but with more paperwork and less gum.
Here’s the kicker: not all real estate counts. If you own the home you live in, you can breathe. Your primary residence is exempt. That means your family’s ranch-style house with the leaky faucet? It’s off the hook. But that second property? The beach condo you rent out? The farm you bought as a “long-term investment” (read: a place to host awkward family reunions)? That is fair game.
Must Read
The Net Worth Dance (and Why It’s Awkward)
When FAFSA asks for the “current net worth,” they aren’t asking about the vibe of the property. They want the cold, hard math: current market value minus any debt you still owe. So if Jenna’s cottage is worth $100,000 (mostly thanks to a good roof and a charming mouse problem), but she still owes $20,000 on a loan, her net worth is $80,000. That number gets plugged into a formula that spits out your Expected Family Contribution. Hint: expected is the government’s polite way of saying “we expect you to cash in that 401k.”
But wait—there’s an ironic twist. FAFSA treats investments differently than income. Income is taxed at a higher rate in their formula. Investments? They’re taxed at a lower rate. So if you have $80,000 in a rental property, FAFSA will ask you to contribute less of that than if you just earned $80,000 from a job. It’s a little backhanded compliment to landlords everywhere: “We don’t love how you make money, but we’ll punish you slightly less.”
 Net Worth Of Real Estate Fafsa at Madison Calder blog
The Line Between “Investment” and “Crap I Own”
Let’s get a little philosophical (but keep it blog-length, I promise). What isn’t an investment for FAFSA? Your car. Your personal jewelry. That collection of signed baseballs your dad gave you. Basically, anything you can’t turn into tuition fast isn’t an investment to them. Real estate for investment purposes is specifically about property you don’t live in and use to generate money. So the vacation cabin you visit twice a year? If you rent it out on Airbnb when you’re not there, congratulations—you’re a real estate mogul in FAFSA’s eyes.
And here’s where it gets a little meta. You might think, “I’ll just say the property is worth less!” Don’t. FAFSA requires you to estimate the current market value honestly. The Department of Education doesn’t send appraisers to your door (thankfully), but if you’re audited, they’ll compare your numbers to public tax records. It’s not worth the stress of lying about your grandma’s cabin.
 FAFSA Basics: Parent Assets — How to Pay for College
A Tiny Cheat Code (Sort Of)
Okay, I’ll give you a little strategy, but keep it between us. You can reduce net worth by paying down debt on the property before you file the FAFSA. If you have $10,000 cash sitting around, using it to pay off a loan on the rental property lowers your net worth by that $10,000. It’s not magic, but it’s legal. Also, remember that small businesses—if you or your parents own one—are treated differently. Real estate used solely for a business is not counted as an investment. So if you run a bakery out of that cottage? That’s a business asset, not a real estate investment.
The Final (Real) Talk
So what did Jenna do? She logged onto the FAFSA website, typed “current market value: $95,000,” subtracted the $20,000 she still owed, and reported a net worth of $75,000. Did it crush her financial aid? A little. But she also found out that her state ignores small real estate holdings for certain grants. Always check your state’s rules—it’s like finding a free coffee voucher in your tax return.
Here’s the bottom line: Don’t fear the real estate question on FAFSA. Fear is just a distraction from math. Calculate the net worth honestly, exclude your primary home, and remember that the government’s idea of “investment” is usually narrower than yours. And if you’re still anxious? Treat yourself to a glass of wine (not paid for by the rental property income). You got this.