Federal Reserve Scf 2022 Net Worth Distribution Percentiles

So, you’re sitting in a café, sipping an overpriced latte, and wondering: Am I rich? Or am I just… existing? Well, my friend, the Federal Reserve’s 2022 Survey of Consumer Fin...
So, you’re sitting in a café, sipping an overpriced latte, and wondering: Am I rich? Or am I just… existing? Well, my friend, the Federal Reserve’s 2022 Survey of Consumer Finances (SCF) has the brutally honest answer—and it’s a wild, uncomfortable ride. Picture this: the Fed basically snooped through 4,500 American households’ finances, from their brokerage accounts to that dusty jar of quarters under their bed. Then, they ranked everyone by net worth percentiles, like a ruthless high school yearbook for adults.
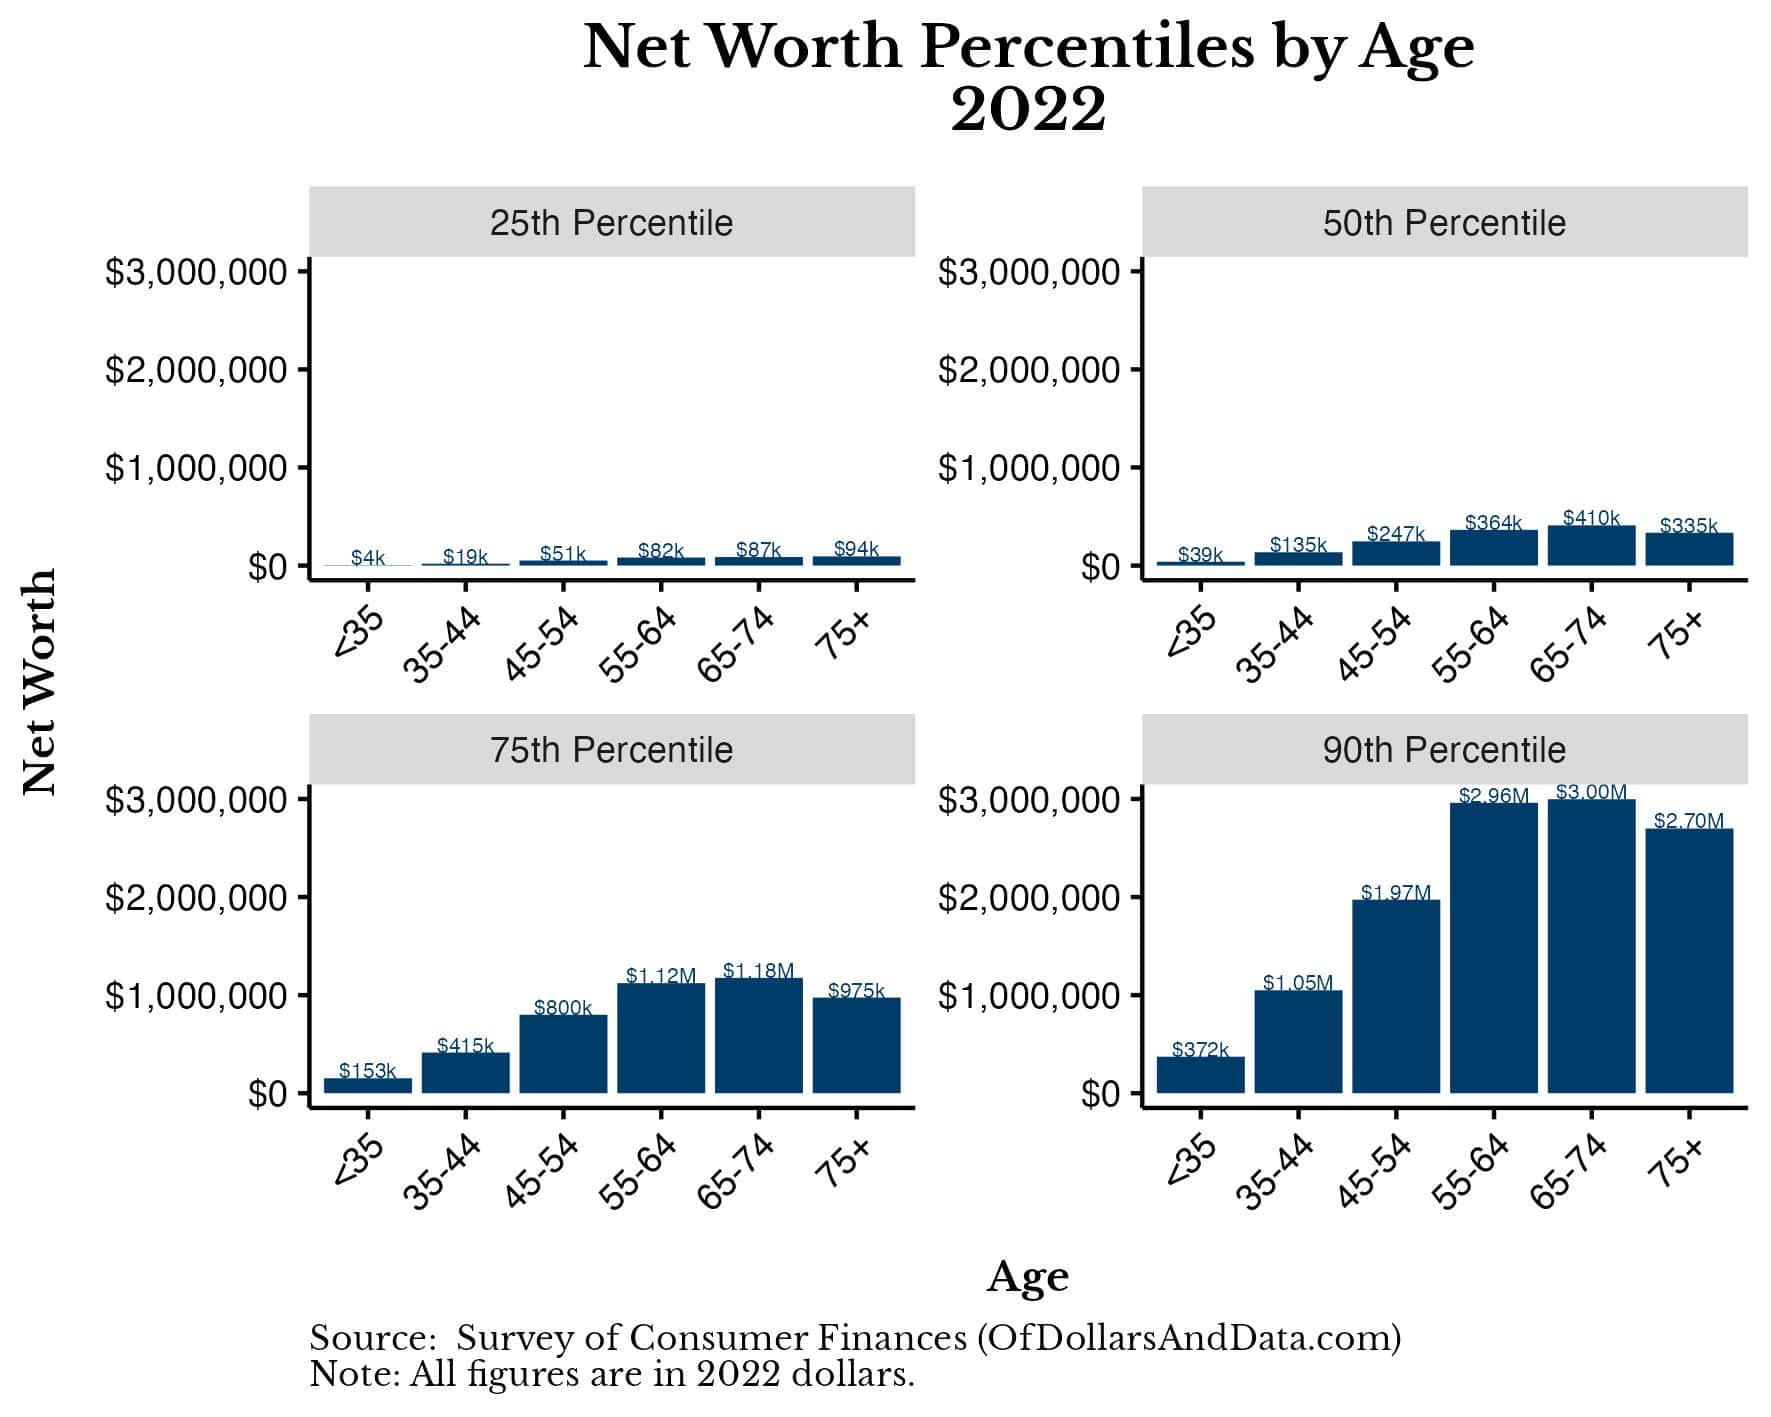
Let’s start with the bottom rung: the bottom 25%. If your net worth is under roughly $11,000, congrats—you’re in the club of “I’d be screwed if my car broke down.” That’s less than the price of a used Honda Civic with a dented door. The middle class—the 50th percentile—has a median net worth of about $166,900. Which sounds okay until you realize that’s mostly home equity, a 401(k) with your ex’s name on it, and maybe a stamp collection your aunt left you.
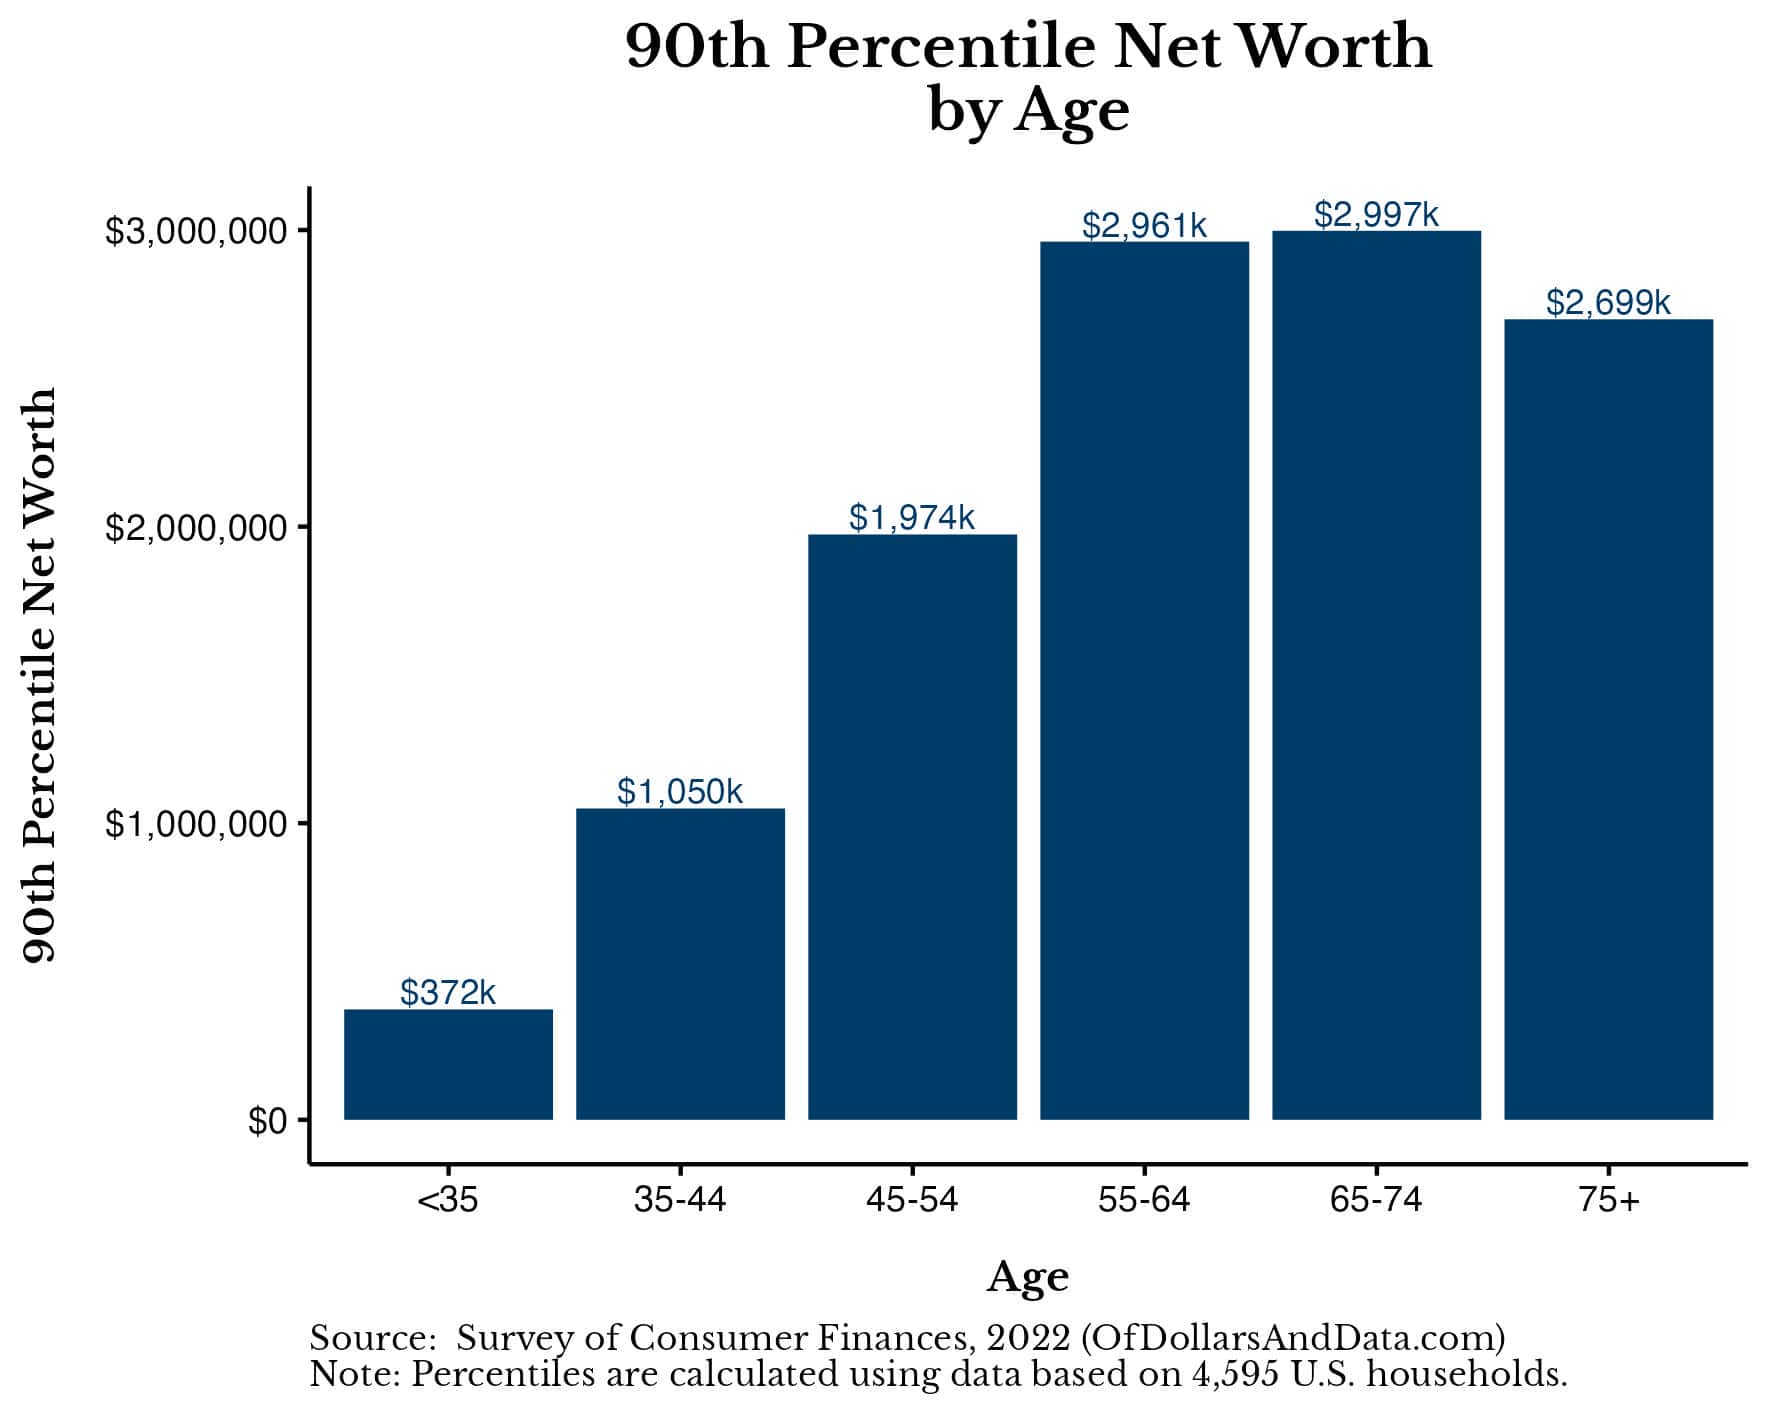
Now, here’s where it gets spicy. The top 10%? They start at a cool $1.9 million. That’s the “I can afford to ignore the price of avocados” crowd. But the top 1%—oh, honey—they laugh at a million. The 99th percentile requires at least $11.1 million. That’s not a net worth; that’s a small country’s GDP. And the top 0.1%? We don’t even have a clean number, but imagine Scrooge McDuck diving into a vault of gold, except it’s all in ETFs and hedge funds.
Must Read
The “Uh-Oh” Percentiles
Let’s talk about debt, because I know you have some. The 25th percentile has a median net worth of $3,100—for some people, that’s a month of rent. Below that? The 10th percentile is actually in negative territory: minus $1,000. That’s right, they owe more than they own. It’s like showing up to a potluck with an empty Tupperware container and asking for leftovers.
 There is a guy in the 2022 SCF, 31 years old, married, no kids, high
The 20th percentile barely scrapes by at $3,800. That’s what I spend on avocado toast in a bad month (just kidding… mostly). But the 30th percentile jumps to $23,100—a small emergency fund if you don’t have a pet or a car. Meanwhile, the 60th percentile sits at $294,000, which is just enough to buy a house in Ohio but a closet in San Francisco.
Fun fact: The 80th percentile (top 20%) requires $590,000. That’s the “I can afford a vacation to Cancún but I’ll still fly Spirit Airlines” zone. And the 90th percentile? A cool $1.1 million. At that point, you can start saying things like, “We’re thinking of diversifying into alternative assets,” and people nod seriously.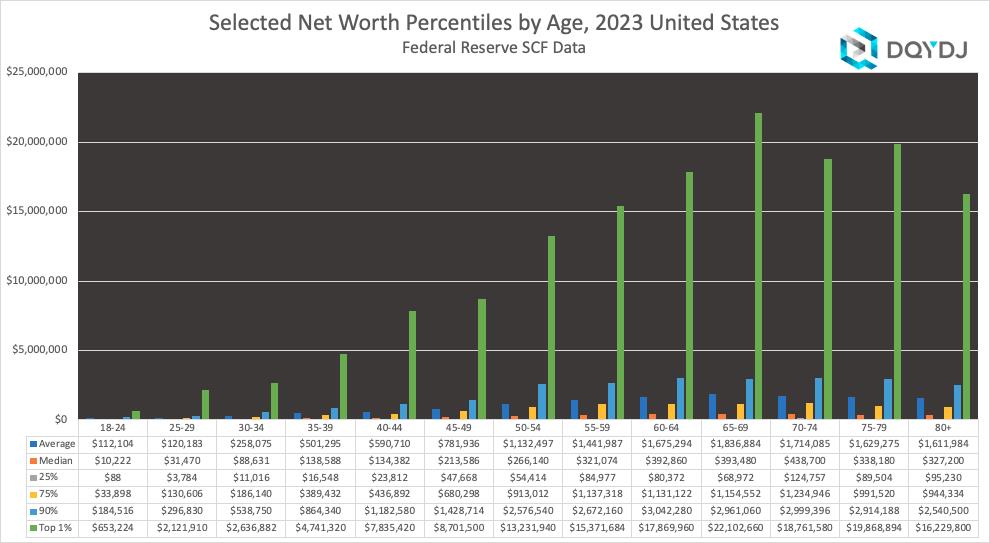 Average Net Worth by age plus median, top 1% and all percentiles
What This Actually Means for You (and Your Latte)
Here’s the secret the Fed doesn’t put in bold: These numbers are from 2022. Since then, inflation has eaten your lunch, and the stock market has done a backflip. If you’re in the 50th percentile, your $166,900 might feel like $120,000 in 2024 dollars. That’s not a net worth; that’s a Tetris block about to crash.
But the top 10%? They’re fine. Their $1.9 million grew because they own Apple stock and a second home in Vermont. Meanwhile, the bottom 25% is still hoping their stimulus check hasn’t bounced. The real surprise? The median net worth for people under 35 is just $14,000. That’s not a fortune—that’s a down payment on a gently used camper van.
 What is the Average Net Worth by Age?
So, what’s the takeaway? The Fed’s numbers are like a funhouse mirror: they show you how absurdly lopsided wealth is. You’re not just competing with your neighbor’s new SUV—you’re competing with a hedge fund manager who buys islands. The 80th percentile might seem fancy, but remember: half of Americans have less than the median. That’s not a statistic; that’s a lot of people living on the edge.
Next time someone asks, “Are you in the top 10%?” just smile and say, “Depends on which percent of my paycheck goes to rent.” And if you’re drinking that latte, consider it a victory: you’re in the top 1% of caffeine consumers. The Fed can’t tax that—yet.
