Federal Reserve Survey Of Consumer Finances 2022 Median Net Worth

Let’s talk money. Not the boring, "save-for-retirement" kind. I mean the real stuff: median net worth. The Federal Reserve dropped their 2022 Survey of Consumer Finances (SCF...
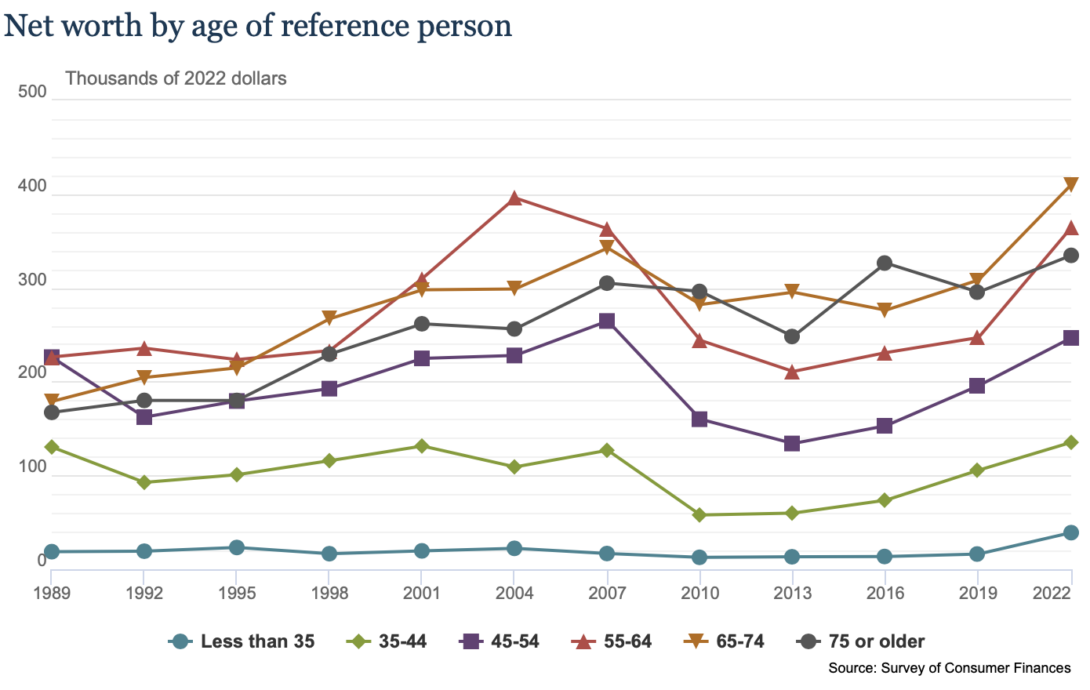
Let’s talk money. Not the boring, "save-for-retirement" kind. I mean the real stuff: median net worth.
The Federal Reserve dropped their 2022 Survey of Consumer Finances (SCF). And it’s a goldmine of quirky data. Like finding your grandma’s hidden candy stash—except the candy is cold, hard cash.
So, what’s the big number? The median net worth for US families in 2022 was $192,900. That’s up a whopping 37% from 2019. Because, apparently, a global pandemic is great for your balance sheet.
Must Read
Wait, what’s "median" again?
Think of a party. If Jeff Bezos walks in, the "average" net worth explodes. The median is the person exactly in the middle. Half the people have more, half have less. It’s the true heartbeat of the American wallet.
And that heartbeat is louder for some than others. The top 10%? Their median hit $3.8 million. The bottom 20%? Just $4,700. Ouch. That’s a difference bigger than a T-Rex compared to a Chihuahua.
The Homeowner Hero
Here’s the fun part: homeownership is the secret sauce. Homeowners saw their net worth surge—median of $396,000. Renters? Just $10,400. That’s not a gap; that’s a canyon.
Why? Because house prices went bananas during COVID. Your 1970s fixer-upper suddenly became a gold mine. You didn’t do anything. You just owned it. Real estate is the lazy person’s lottery ticket.
 Know Your (Net) Worth
Stocks and the "Rich Get Richer" Machine
Stock ownership also skyrocketed. 58% of families now own stocks, directly or through retirement accounts. That’s up from 53% in 2019. Everyone bought the dip. Or at least, everyone who could.
The top 1%? They hold 30% of all company shares. The bottom half? They hold just 1%. It’s like one person eating the whole pizza while everyone else fights over a breadstick.
Debt: The Uninvited Guest
But wait—there’s debt! Credit card balances fell during 2022 (thanks to stimulus checks). But student loans? Still partying. 30% of families had education debt, with the median balance at $27,000. That’s a small car or a really bad vacation.
Funny detail: older families are carrying more debt than ever. Grandparents are still paying off their Apple stock from 2005. It’s the financial equivalent of a forever lease.
Race: The Awkward Elephant
Let’s not ignore the uglier funny bits. White families had a median net worth of $285,000. Black families? $44,900. Hispanic families? $62,000. The gaps are stubborn. They’re like that one stain on your favorite shirt—no matter how many times you wash it, it just stays.
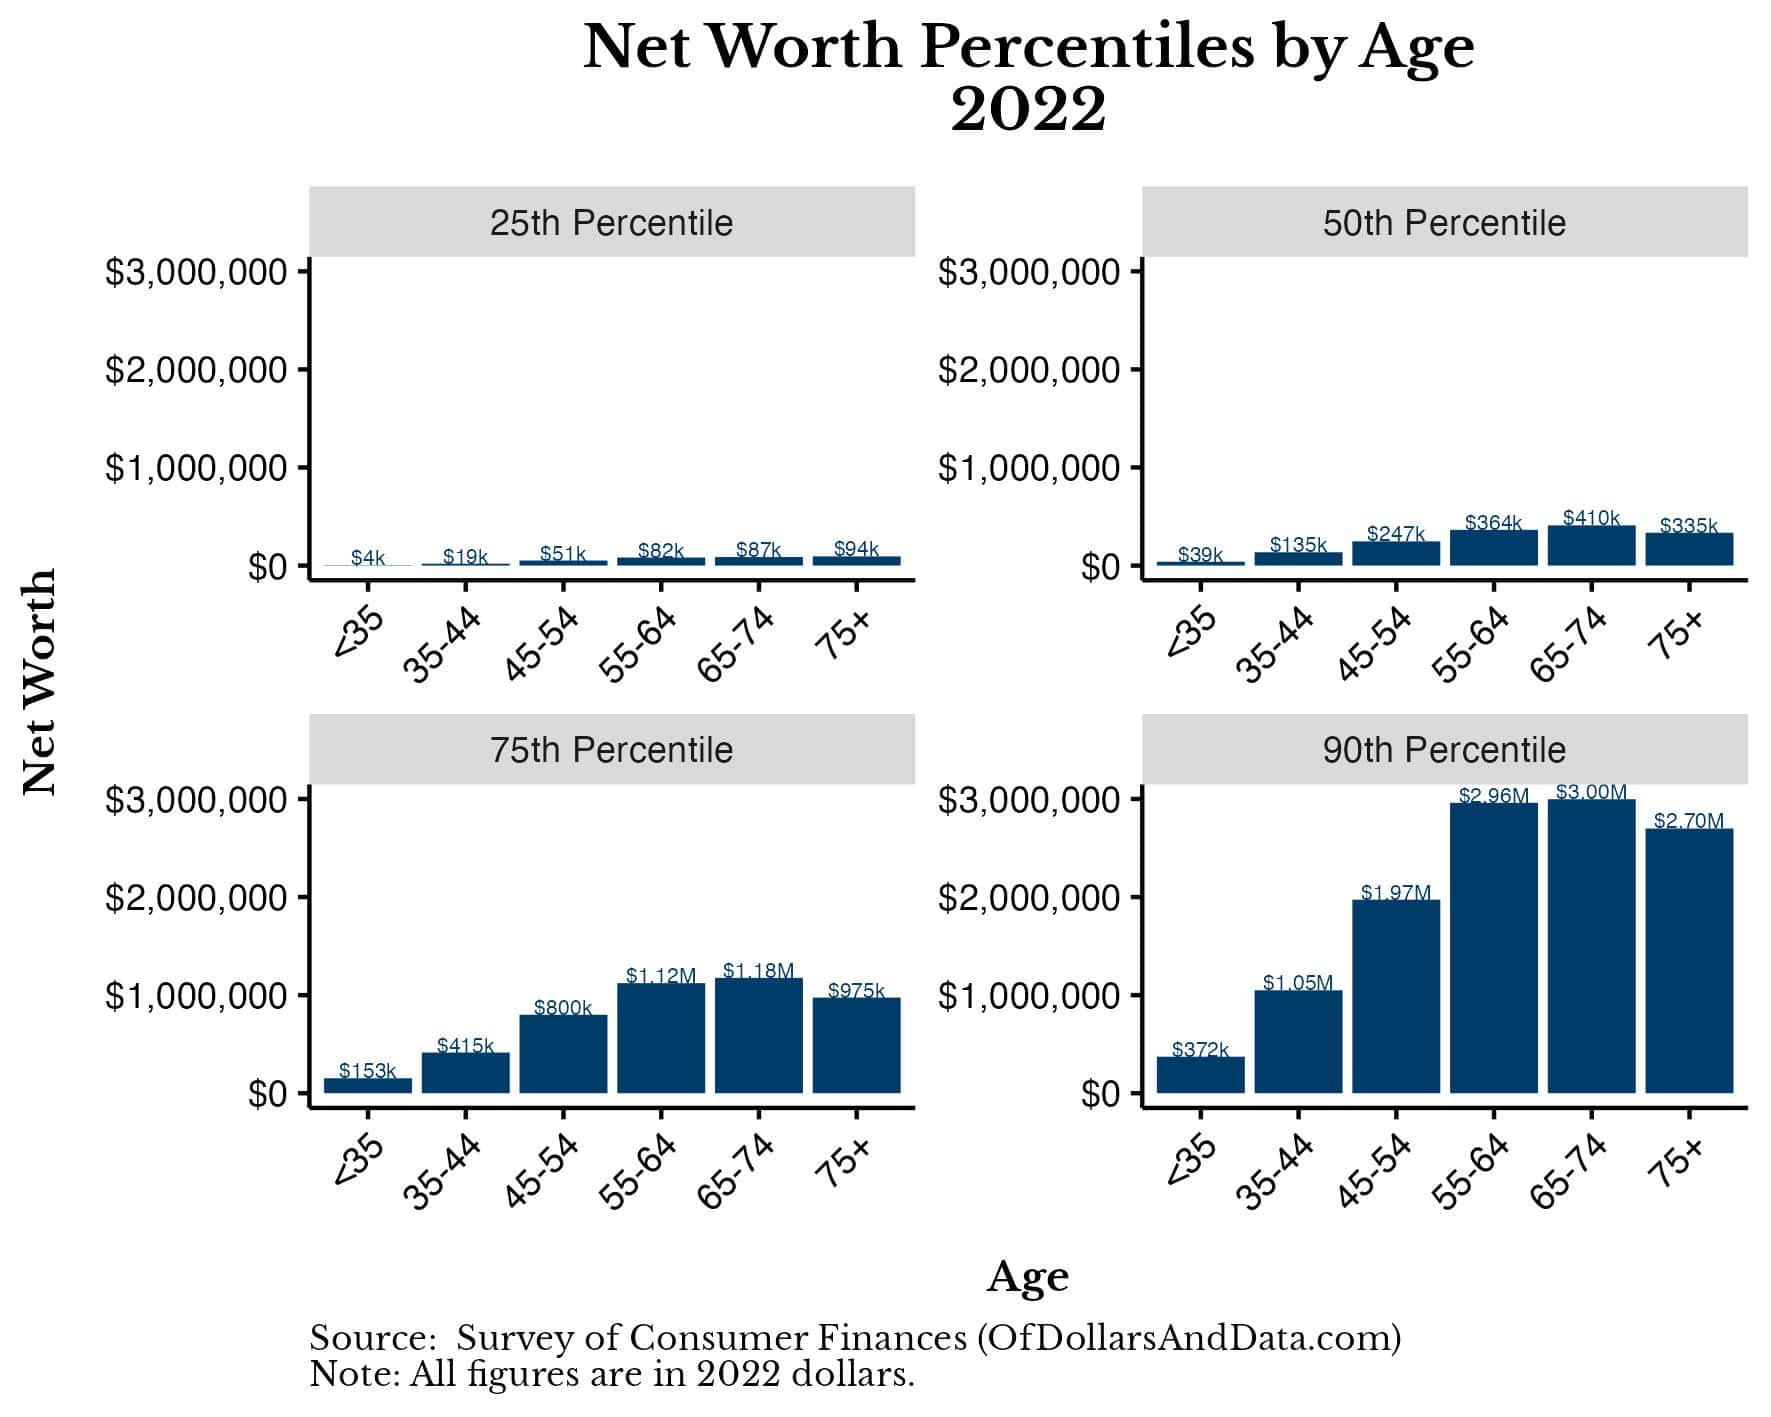 What is the Average Net Worth by Age?
But here’s a weird twist: every racial group saw massive gains from 2019 to 2022. Black families especially grew their net worth by 60%. It’s like everyone got a pay raise, but the starting line was still miles apart.
The "You Are Here" Moment
So where do you fit? If you’re under 35, your median net worth is just $30,000. Yep. You’re broke compared to your boomer parents. But hey, you have memes.
If you’re over 75, your median net worth is $440,000. You’ve been saving since the invention of the wheel. Congrats, you win the game of life.
Why This is Fun (Seriously)
This data is like a sociology party game. It shows how weird money is. Did you know that 65% of families have a retirement account? Yet the median balance is just $87,000. That won’t buy you a decade of cat food.
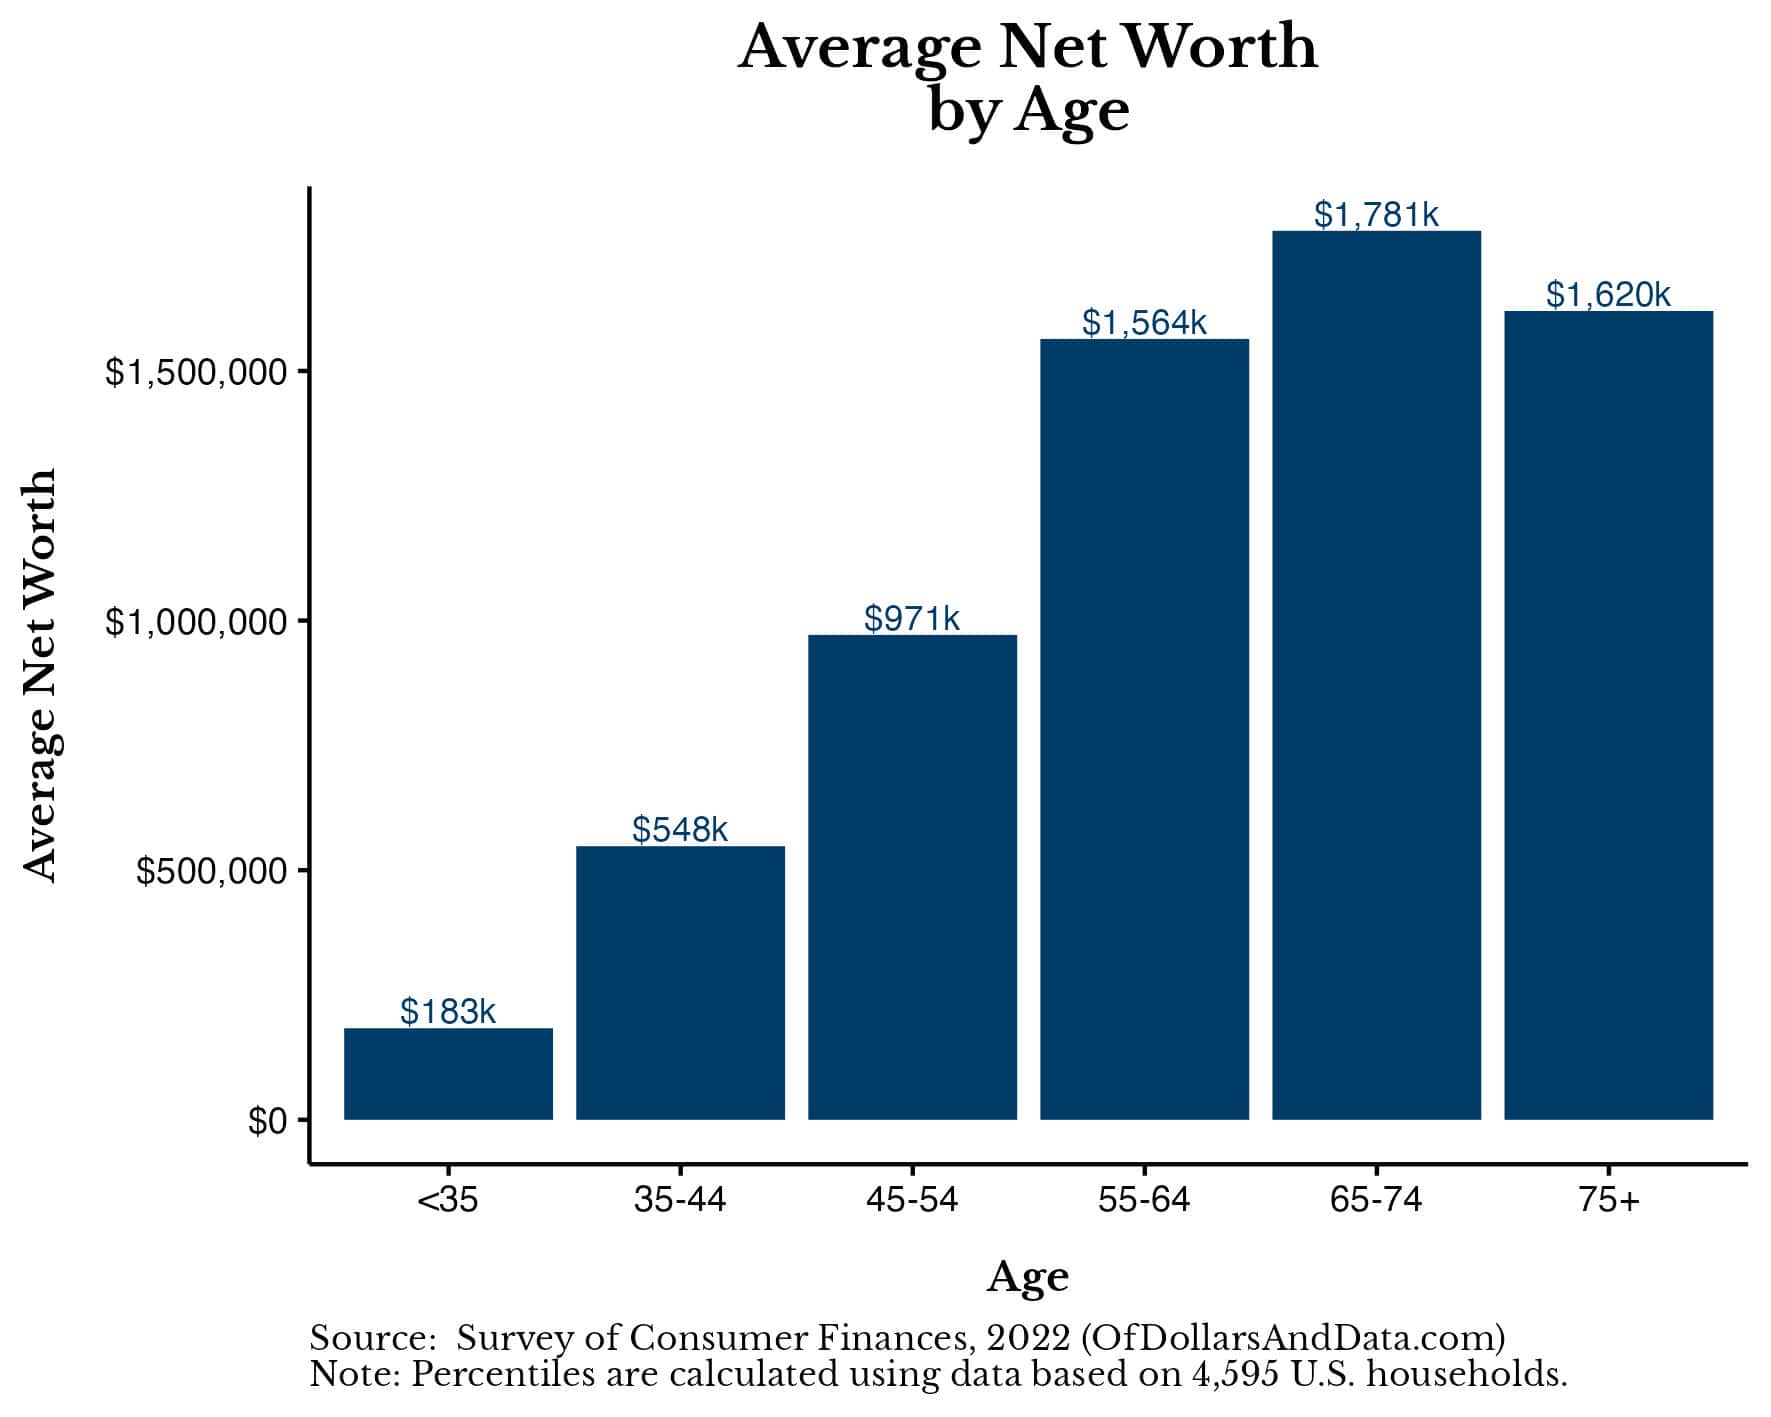 What is the Average Net Worth by Age?
And get this: the top 10% control 67% of all wealth. The bottom 50%? Just 4%. It’s a pyramid with a very pointy tip. Like a financial Mount Everest.
The Takeaway (No Homework)
The Fed’s survey is a time capsule. It captures a moment when people got free money from the government. When houses became magic beans. When the stock market turned into a TikTok challenge.
It’s messy. Unequal. And weirdly hilarious. Because in 2022, the median American family was worth about $193,000—but only if they owned a home and didn’t have a student loan.
So next time you feel poor, remember: the middle is always weird. And the Fed is just here to tell you, with a straight face, that your neighbor is probably richer than you thought.
Now go check your 401(k). Or don’t. Ignorance is bliss. But the data? It’s a hoot.
