Financial Planning For High Net Worth Individuals

So, you’ve got a few extra zeros in your bank account. Maybe a lot of them. First off, congratulations—or, you know, condolences on the new headache. Because let’s be real: be...
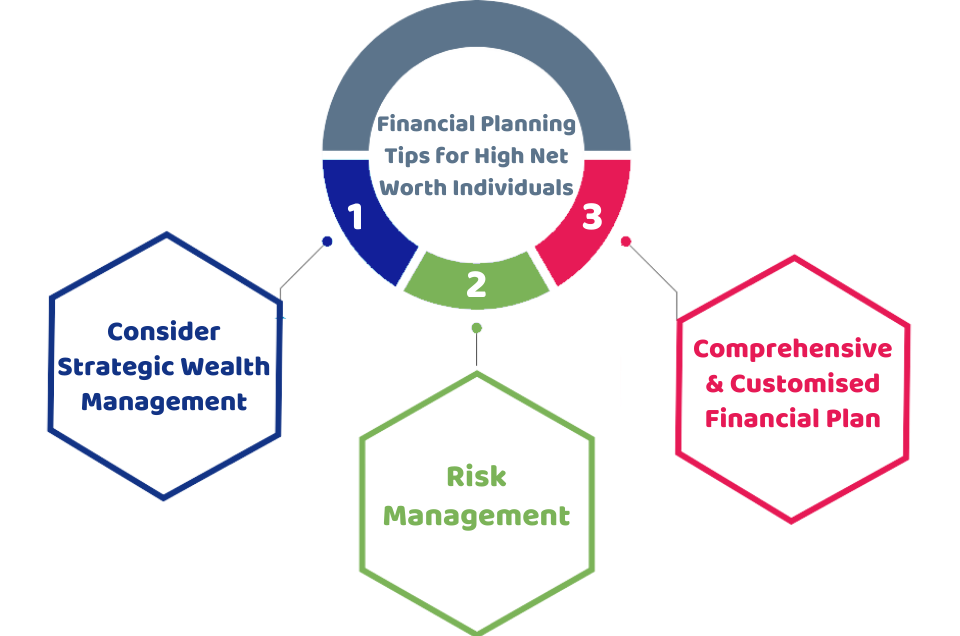
So, you’ve got a few extra zeros in your bank account. Maybe a lot of them. First off, congratulations—or, you know, condolences on the new headache. Because let’s be real: being rich doesn’t mean you’re done worrying. It just means you worry about different things, like yacht depreciation and whether your private chef’s pension plan is sound.
The Big Secret Nobody Tells You
Here’s the thing about high net worth individuals (HNWIs): you’re not just managing money. You’re managing a reputation, a legacy, and probably a very complicated family tree. Your financial plan isn’t a spreadsheet. It’s a soap opera waiting for a director.
Think about it: you have assets in three countries, a vineyard that loses money every year (but your spouse loves it), and a cousin who keeps asking for a “loan.” Sound familiar? Yeah, I thought so.
Must Read
Step One: Stop Treating Your Money Like a Hobby
I get it—you worked hard. You earned it. But wealth without a plan is just a very expensive pile of stress. You wouldn’t fly a plane without a co-pilot, right? So why are you managing $20 million with a spreadsheet and a prayer? Hire a team. Seriously. Get a CFO for your personal life. It’s a thing.
Your team should include a tax strategist (not just an accountant, a strategist), an estate attorney who loves drama, and a financial advisor who’s seen it all. Bonus points if they’ve handled an art collection or a racehorse trust. You know, normal stuff.
The Tax Man Cometh (And He’s Bringing Friends)
Let’s talk taxes. Ugh, I know. But for HNWIs, taxes are the main character in your financial story. You’re not hiding money (that’s illegal and messy). You’re strategically relocating it. Think of it like a game of chess, but the pieces are made of gold and the board is on fire.
 Financial Planning Ideas for High Net Worth Individuals — IntelliVest
You need to ask yourself: Am I paying taxes in the right state? What about countries? Should I give money to charity now, or in five years? Spoiler alert: the answer is usually now, because the government is always hungry. Donor-advised funds are your new best friend. They’re like a savings account for generosity—but with a tax deduction.
Estate Planning: The Plot Twist
Nobody wants to think about dying, especially when you’re busy living on a boat in Monaco. But here’s the hard truth: if you die without a plan, the government gets to decide who gets your stuff. And trust me, they don’t know your nephew’s name. He’ll end up with a tax bill and a dusty painting of a clown.
You need a will. A trust. Maybe three trusts. One for the house, one for the business, one for the “fun” money (yes, that’s a real category). And an irrevocable life insurance trust? That’s just fancy talk for “I don’t want my heirs to hate me.” You’re welcome.
 Tax Planning for Ultra High Net Worth Individuals and Families - CCMI
Risk Management: Prepare for the Absurd
Let’s be playful for a second. What’s the weirdest thing that could happen to your money? A lawsuit? A divorce? A rogue wave that sinks your second yacht? Yes, all of that. Insurance isn’t boring; it’s freedom insurance.
You need umbrella liability (umbrella implies you’re covered in all weather, get it?), cyber insurance (your crypto can be hacked, Brad), and maybe even kidnap and ransom insurance. I’m not kidding. If your net worth is over $10 million, you’re on a list. Wear sunscreen. And buy the policy.
Investing: Don’t Be Boring, But Don’t Be Stupid
You’ve probably got a portfolio that looks like a zoo—stocks, bonds, private equity, crypto art, and a share in a whiskey distillery. Diversification is great, but only if you know why you own each piece. Why do you own that vintage car collection? Because you love it? Great. Just don’t pretend it’s a retirement strategy.
 Top 5 Tips For High Net-Worth Financial Planning
Ask yourself: Am I chasing returns, or am I building a fortress? A real financial plan for HNWIs is 75% defense, 25% offense. You don’t need to double your money. You need to never lose it. Unless you’re under 40, then maybe swing for the fences. But wear a helmet, genius.
The Final, Awkward Question
So, how much is enough? When do you stop? I’ll tell you a secret: enough is the day you can buy anything you want and still sleep at night. For most HNWIs, that’s already today. So stop worrying about the next zero and start worrying about the next generation. Or your next trip to Antarctica. Both.
And hey, if all else fails? Just remember: you can’t take it with you. But you can make sure your grandchildren fight over the right stuff—like your vintage wine, not your tax bill. Cheers to that. ☕
