Help Me Understand Net Worth Better

Last week, my friend Dave called me in a panic. He’d just checked his banking app and saw a $50,000 balance. “I’m a net worth millionaire!” he texted, complete with a rocket e...

Last week, my friend Dave called me in a panic. He’d just checked his banking app and saw a $50,000 balance. “I’m a net worth millionaire!” he texted, complete with a rocket emoji. I had to break it to him gently: that $50k in his checking account was actually a loan he took out for a van conversion.
Dave thought net worth was just how much cash you have. Spoiler: it’s not. And if you’re reading this, you’re probably as confused as he was—which is exactly why we need to talk.
So What Even Is Net Worth?
Net worth is the financial snapshot of your life on one specific day. It’s the total value of everything you own minus everything you owe. Think of it like a sandwich: assets are the delicious stuff like bread, meat, and cheese, and liabilities are the crumby, soggy parts.
Must Read
You don’t want a soggy net-worth sandwich, my friend. The formula is brutally simple: Assets (cash, home, investments, that collection of vintage Star Wars figures) minus Liabilities (mortgage, student loans, credit card debt). Whatever number pops out is your net worth.
And yes, your beanie baby collection counts as an asset—if you actually sell it for money. I’m looking at you, Dave.
Why You Should Care (Even If You’re Broke)
Here’s the weird truth: your net worth can be negative, and that’s totally normal if you’re under 30. A medical student with $200k in loans and a beat-up Honda has a net worth of negative $190k. That sounds awful, right?
But that same student will likely earn a doctor’s salary in five years. Net worth is a progress meter, not a judgment of your worth as a human being. (Thank goodness.) It’s the map, not the destination. You track it to see direction: are you driving toward a cliff or a beach?
 Positive Net Worth: Khám Phá Tài Chính Cá Nhân Ổn Định và Bền Vững
Side note: never compare your net worth to a tech bro on Twitter. He’s probably lying about his crypto gains anyway.
Assets: The Good Stuff
Assets are things that put money in your pocket over time. A rental property that pays you rent? That’s an asset. A car that you use for Uber? Also an asset. But your daily driver that costs you gas, insurance, and repairs? That’s a liability disguised as freedom.
Here’s the trick: liquid assets (cash, stocks) are worth their current market value. Illiquid assets (your house, your comic book collection) are only worth what someone will pay you today. Grandma’s antique vase might be priceless to you, but to a pawn shop it’s $20. Be honest with yourself.
Oh, and your 401(k) counts. Even if you can’t touch it until you’re 65, it’s still part of your net worth. Don’t ignore the retirement savings—future you is counting on present you.
 Understanding Net Worth | How to Calculate and Grow It: – mrtrimfit.com
Liabilities: The Soggy Part
Liabilities are the opposite of fun. They’re debts: that student loan, the car payment, the credit card balance from your “stress-shopping” phase. We’ve all been there. Even your mortgage counts, even if you live in it and love it.
A key thing to remember: a mortgage on a $300k house with $250k remaining? That’s a $250k liability. The house itself is an asset worth $300k, so your net equity is $50k. But the bank owns most of that house right now—sorry, not sorry.
Here’s a wild thought: debt isn’t always evil. Low-interest debt for a degree or a home can increase your future net worth. High-interest credit card debt? That’s a tax on being broke. Prioritize killing that beast first.
How to Calculate It (Without Crying)
Grab a piece of paper—or open a spreadsheet, you digital minimalist. List every asset you own: checking, savings, retirement accounts, home value (use Zillow, it’s close enough), car value (use Kelley Blue Book). Add them up. Feel rich yet?
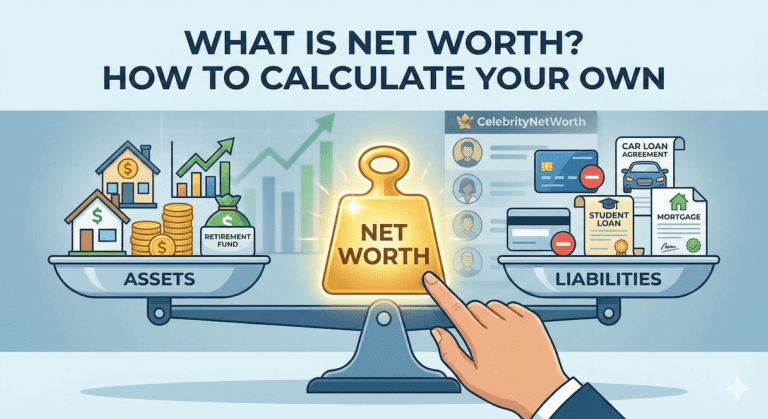 Understanding net worth: A guide to calculating your financial standing.
Now list every liability: mortgage balance, car loan, student loans, credit card balances. Add those up too. Then do the math: Assets minus Liabilities equals Net Worth. If the number is negative, don’t panic. You’re just early in the game. If it’s positive, high-five yourself—but don’t get cocky.
Pro tip: Track this number once a month. Watching it grow is addictive. Watching it shrink is a wake-up call—like when Dave found out he owed $48k on that van.
The “Duh” Moment
After our talk, Dave recalculated his net worth. It turned out to be negative $46,000. He laughed, then asked, “So I’m poorer than I thought?” I told him the truth: “You’re aware of it now, which makes you richer than most people.”
Net worth isn’t about bragging rights or shame. It’s a mirror that shows your financial reflection. If you don’t like what you see, you can change the lighting—or start paying down that van loan. The goal is to make that number go up over time, even if it’s slowly.
And remember: your net worth is not your self-worth. Unless you’re a total billionaire—then they’re basically the same thing. But for the rest of us? Keep tracking, keep learning, and maybe don’t take out a loan for a van you don’t need. (Sorry, Dave.)
