High Net Worth Whole Life Insurance

So, picture this: my friend Dave—a guy who once tried to pay for a coffee with a black Amex (it declined, by the way, so awkward)—calls me in a panic. He’d just realized his e...
So, picture this: my friend Dave—a guy who once tried to pay for a coffee with a black Amex (it declined, by the way, so awkward)—calls me in a panic. He’d just realized his entire net worth was tied up in a volatile tech stock and a comic book collection. He asked, “What if I die tomorrow? My kids get a pile of Spiderman #1s and a tax bill?”
That’s when I introduced him to the beast he’d been avoiding: High Net Worth Whole Life Insurance. Not the boring term life your dad bought at the airport kiosk. I’m talking about the champagne of insurance—a financial Swiss Army knife for people who have more zeros in their bank account than in their stress levels. Ready to dive into this weird, wonderful tool? Buckle up.
What Even Is This Thing?
First, let’s get real: whole life insurance for high net worth folks isn’t about paying for a funeral. You’re not burying a millionaire in a discount casket. It’s about leveraging a policy as a living asset that grows tax-deferred and can be borrowed against.
Must Read
Think of it as a secret underground bunker for your cash. You pay premiums (yes, they’re chunky—like a monthly mortgage on a small yacht), and in return, the policy builds cash value that earns a guaranteed interest rate plus dividends from the insurance company’s profits. Boring? Maybe. Lucrative? Absolutely.
Here’s the kicker: when you’re a high net worth individual, Uncle Sam loves to take a bite out of your estate. Whole life insurance dodges that bite like a ninja in a taxicab. The death benefit goes to your heirs income-tax-free, and if structured right, it skips estate taxes too. (Cue the angels singing.)
The Mirage of “Buy Term and Invest the Difference”
You’ve heard that phrase from your brother-in-law the day trader, right? “Just buy term insurance and invest the rest in crypto, bro!” Oh, the irony. Most people who try that end up with a term policy that expires at age 60, just when they actually need coverage, and a crypto portfolio that looks like a melted popsicle.
 Whole Life Insurance
For the wealthy, volatility isn’t “fun”—it’s a nightmare when you’re planning generational wealth. High net worth whole life acts as a stabilizer. It’s the boring, reliable friend who shows up with a casserole when your stocks are on fire. You can borrow against the cash value at low interest rates to fund a business, buy real estate, or even pay for that private jet rental. The best part? You don’t have to pay the loan back—it just reduces the death benefit. Talk about a win-win loophole.
But wait—you’re thinking, “Isn’t the return on whole life tiny?” Yes, if you compare it to a hot IPO. But compare it to bonds, which are supposed to be safe and yield 2%, and suddenly a policy returning 4–6% tax-deferred looks like a genius move. Plus, you get a death benefit on top. Take that, bond fund.
Who Actually Needs This? (Hint: It’s Not You If You Drive a Honda)
Let’s be blunt: if your net worth is under, say, $5 million, whole life is probably overkill. You’re better off with term insurance and a 401(k). But if you’re part of the “1% but anxious about it” club, listen up. High net worth whole life shines when you have estate tax exposure, illiquid assets (like a family business or a ranch), or you want to leave a legacy without the government taking half.
 High Net Worth Life Insurance: A Comprehensive Guide
I know a retired surgeon who used his policy to buy a vineyard. Another client—a tech founder—funded his daughter’s startup using policy loans instead of selling stock. The common thread? They hate paying taxes more than they love brussels sprouts. (And who can blame them?) This insurance lets you move money around like a chess master, shielding it from market crashes and the IRS’s hungry hands.
Now, before you call your insurance agent, a savage reality check: this stuff is complicated. If you buy the wrong policy, you’ll pay high fees and get garbage returns. You need a specialized advisor who eats, sleeps, and breathes high net worth planning. Ask them, “What’s your internal rate of return on the cash value after year 20?” If they stare at you blankly, run.
The Ironic Twist: It’s Not Really “Insurance”
Here’s the part that makes my head spin: most people think insurance is a grudge purchase—like a toaster you buy only because your old one caught fire. But high net worth whole life is actually a wealth creation tool disguised as protection. You’re not paying for peace of mind; you’re paying for optionality and control.
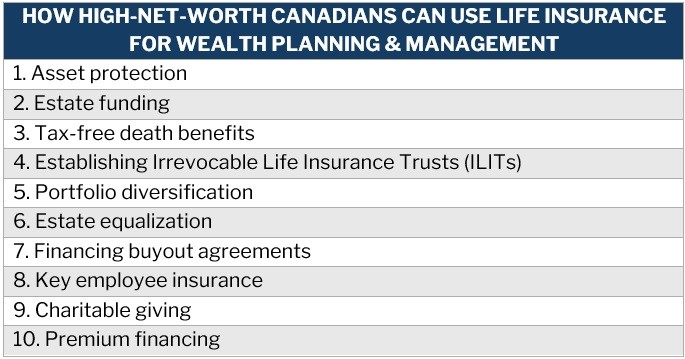
 10 High Net Worth Life Insurance Strategies Updated For 2026
Imagine you get hit by a bus tomorrow. (Sorry, morbid but necessary.) Your family doesn’t just get a payout—they get a tax-free pile of cash that’s bigger than your estate tax bill. But if you live to 95 (and let’s be honest, you’ll probably outlive your offspring with your avocado toast habits), you can withdraw the cash value in retirement, tax-free, because it’s structured as a return of premium. Mind. Blown.
The irony? The wealthier you are, the more you realize you don’t need “life insurance” for life—you need it for life’s loopholes. It’s like finding out your emergency blanket is actually a parachute, a tent, and a solar charger. Who knew?
Final Word? More Like a Warning With a Wink
Don’t buy high net worth whole life insurance because some slick guy at a cocktail party told you to. Buy it if you have a liquidity problem in your estate, or you want to borrow against cash without selling assets, or you just enjoy financial planning that makes your accountant cry with joy. It’s not for everyone—it’s for you, Mr. or Ms. I-Have-More-Cash-Than-Common-Sense. (Kidding, mostly.)
So, what did Dave do? He bought a policy, sold his comic books (turns out Spiderman #1s are heavy to store), and now he sleeps like a baby. When I asked him if it was worth the hefty premium, he smirked and said, “It’s cheaper than therapy—and it comes with a death benefit.” Touché, Dave. Now go forth and protect your kingdom, you magnificent financial rumple-stiltskin. Just don’t forget to read the fine print. (I’m watching you.)
