Household Net Worth By Age Percentile

So, picture this: I’m at a dinner party last week, and my friend Mark—who drives a beater and wears the same Patagonia fleece he’s had since 2019—casually drops that he just b...

So, picture this: I’m at a dinner party last week, and my friend Mark—who drives a beater and wears the same Patagonia fleece he’s had since 2019—casually drops that he just bought a second property. Meanwhile, another friend, Jen, who always looks like she just stepped out of an Anthropologie catalog, whispers to me that she’s drowning in student loans and has exactly $400 in savings. Cue the internal panic. I started mentally comparing my own bank balance to theirs, and I realized: I have no idea where I actually stand.
That moment sent me down a rabbit hole of Household Net Worth By Age Percentile. And let me tell you, it’s both a relief and a kick in the pants. You’ve probably seen those viral charts—the ones that show the median net worth for a 30-year-old is $12,000, but that the 90th percentile is chilling at $250,000. Excuse me, what? It’s like comparing a lemonade stand to a tech IPO.
Let’s break this down in a way that doesn’t make you want to throw your phone across the room. First, the median numbers are your reality check. If you’re in your 20s and have a net worth of $10,000, congratulations—you’re smack in the middle. That’s not bragging, but it’s also not a disaster. The trick is that “net worth” isn’t your paycheck; it’s everything you own minus everything you owe. So, yes, that $40,000 student loan balance is dragging you down, but your emergency fund is lifting you up.
Must Read
The shocking spread: 10th vs. 90th percentile
This is where things get weirdly poetic. Imagine standing in a room with ten people. The person at the 10th percentile for a 35-year-old might have a negative net worth—like, they owe more than they own. The person at the 90th percentile? They’re sitting on $1.2 million. One person is fighting to keep the lights on; the other is debating whether to buy a sailboat. And you’re probably somewhere in that messy middle.
But here’s the ironic kick: those top-percentile folks didn’t just “save harder.” Most of them had a head start—inheritances, family loans for a down payment, or a tech job that handed out RSUs like candy. Meanwhile, the bottom percentiles are often people doing everything “right” but getting crushed by housing costs or medical debt. It’s not a merit badge, folks.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
What this means for you (and your anxiety)
If you’re under 40 and your net worth is below the median, you are normal. Seriously. The internet loves to make you feel like a failure because some 28-year-old YouTuber bought a Lamborghini. But real life? Most people your age are sleeping on IKEA mattresses and praying their car doesn’t break down. The median net worth for a head of household aged 35-44 is about $135,000—but that includes home equity. If you don’t own a home, subtract a huge chunk of that number.
Here’s a side note that might piss you off: age percentiles are a blunt tool. They don’t account for cost of living. A net worth of $200,000 in San Francisco is basically “I have a used Honda and a meth lab in the garage won’t scare my roommates.” But the same number in rural Ohio? You’re practically a baron. So stop comparing your Zip Code anchors to someone else’s.
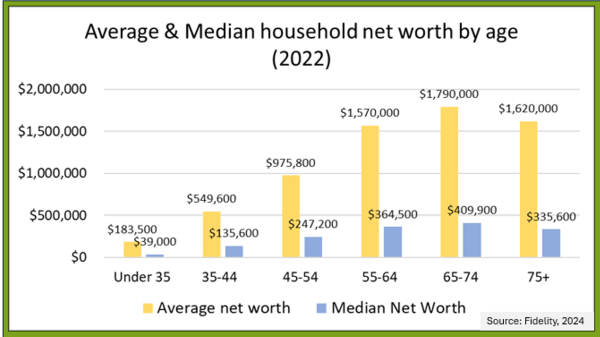 Chart and Comment: Average and Median Household Net Worth by Age — HOME
Let’s talk about the 50-64 age bracket, where the numbers get truly bonkers. The 90th percentile net worth here is around $2.6 million. But remember: that’s after decades of compounding, mortgage payments, and probably a couple of divorces. If you’re 30 and have $50,000, you’re not “behind.” You’re just early in the game. The math works in your favor if you keep saving—even if it feels like you’re filling a bathtub with a teaspoon.
The elephant in the room: Debt isn’t the enemy (usually)
I know, I know—you’ve heard it a million times: “Debt is bad!” But here’s a little secret: the people in the top percentiles often have massive mortgage debt. Their net worth is high because their assets (a house, investments) outpace what they owe. Meanwhile, someone with zero debt but zero assets is actually worse off. It’s not about avoiding debt; it’s about taking on “good debt” that buys appreciating stuff. Sorry, your credit card for concert tickets doesn’t count.
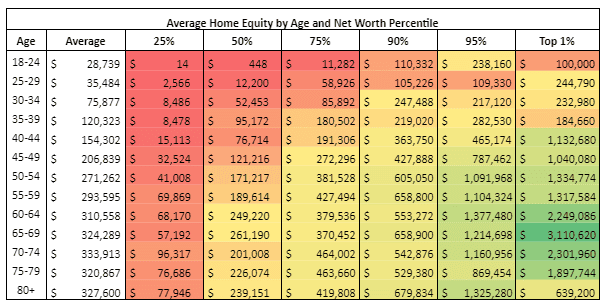 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
If you’re feeling queasy about your own percentile, do this: look at the median for your age group, then subtract 20%—because most surveys miss the poorest households. That “average” is tilted upward by billionaires. The real middle is humbler. Still anxious? Good. Use that anxiety. Put $50 more into your 401(k) this month. It won’t change your percentile overnight, but it will nudge the needle. And yes, I’m talking to you, the person who skimmed this while eating cereal at 11 p.m.
So what’s the takeaway? Household net worth by age percentile is a snapshot, not a verdict. It’s a tool to see where you are, but it’s also a reminder that wealth is a slow, boring marathon—not a viral dance trend. Ignore the show-offs, pity the comparison-shoppers, and keep stacking. The only percentile that matters is the one where you can sleep at night without checking your bank balance twice.
