Household Net Worth Percentile By Age

So picture this: my friend Mark, a 34-year-old graphic designer, called me last week, his voice a mix of panic and curiosity. He’d just stumbled onto some online calculator th...

So picture this: my friend Mark, a 34-year-old graphic designer, called me last week, his voice a mix of panic and curiosity. He’d just stumbled onto some online calculator that spits out your “net worth percentile by age.” After plugging in his modest savings, a beat-up car, and his half-share of a one-bedroom apartment, he stared at the screen. The result? He was in the 25th percentile for his age bracket. He laughed nervously and said, “So, I’m basically the backup dancer at the wealth concert.”
That moment got me thinking—and probably you too, right? We all secretly wonder where we stack up against the Joneses, especially when the Joneses seem to be driving Teslas and buying second homes. But here’s the thing: net worth percentiles by age are less a scorecard for your life and more a weird, revealing map of American financial reality. They show you who’s sprinting, who’s crawling, and who’s just standing still eating a hot dog.
What even is “net worth,” and why should you care?
Let’s get the boring stuff out of the way. Net worth is everything you own (cash, investments, home equity, that Funko Pop collection) minus everything you owe (student loans, credit cards, that tab from your cousin’s wedding). Simple math, but brutally honest. It’s a snapshot of your financial health, not your paycheck—because you could earn six figures and still have a negative net worth if you’re drowning in debt. Ouch, right?
Must Read
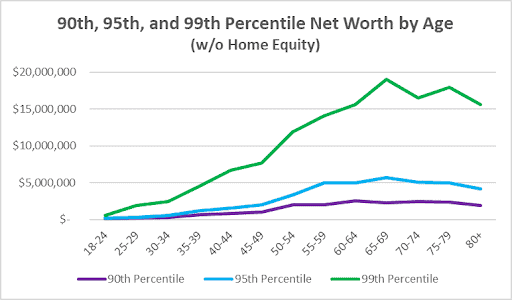
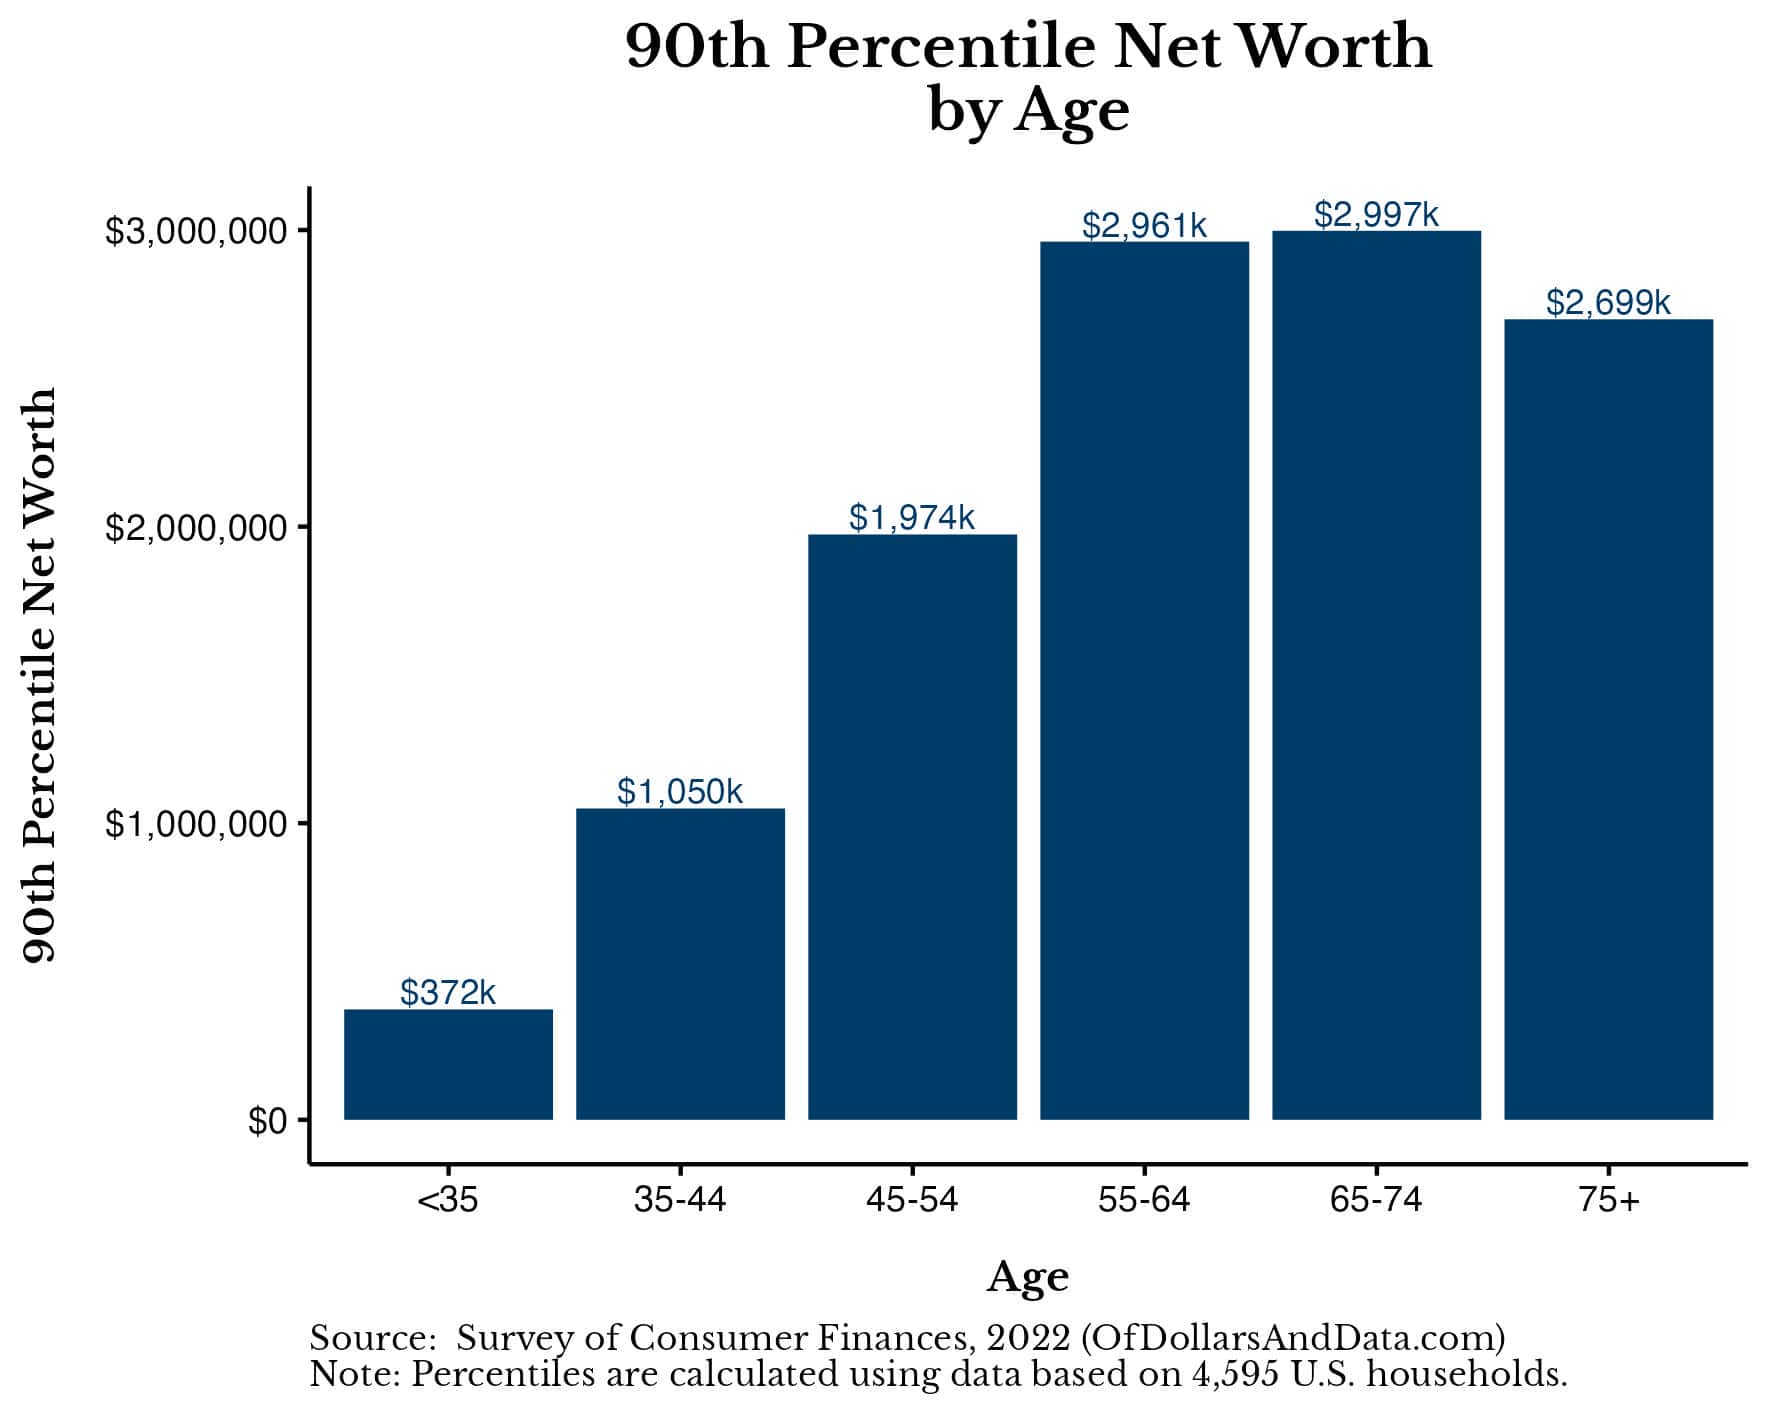
Now, the percentile bit. If you’re in the 50th percentile for your age, it means half the people your age have less net worth, and half have more. It’s not a ranking you should obsess over—but let’s be real, you’re going to peek anyway. The data, often pulled from Federal Reserve surveys, shows a wild range. For example, the median net worth for someone under 35 is around $14,000. Yes, fourteen thousand. Meanwhile, the top 10% of that same age group is sitting on over $400,000. It’s not a fair race; it’s a relay where some people get a head start and a better baton.
The 20s: A financial wasteland or a golden opportunity?
If you’re in your 20s, brace yourself: the average net worth for Americans aged 20-29 is often negative, thanks to student loans. You’re basically paying for the privilege of having a degree. The 25th percentile here is often below zero—like, negative $1,000 or more. Don’t panic. Seriously, don’t. This is the decade of ramen, roommate drama, and building habits. The goal isn’t to be rich yet; it’s to avoid being stupid. A $1,000 emergency fund puts you ahead of a shocking number of people. You’re planting seeds, not harvesting a forest.
 Net Worth by Age: How Do You Compare to Your Peer Group? - Wealthtender
By the time you hit 30, the gap widens. The median net worth for ages 30-34 jumps to about $36,000. But here’s the kicker: the top 10% in this age group already has over $650,000. Why? Inheritance, high-paying tech jobs, or just crazy good luck. You’re not failing if you’re at $30,000—you’re just not the lottery winner. Ironic, isn’t it? We spend our 20s being told to “follow your passion,” then get shocked when passion doesn’t pay like an IPO.
40s and 50s: The squeeze and the stretch
Now we’re in the “real adult” years. For ages 45-54, the median net worth climbs to around $135,000. That sounds decent, until you realize a big chunk is often tied up in home equity. Your house isn’t a cash fountain—it’s a place you sleep that happens to be worth something. The 75th percentile here is about $600,000, while the top 10% is over $2 million. This is where life happens: kids’ college, aging parents, and a sneaky midlife crisis car purchase.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
Notice the pattern? Homeownership is the great divider. If you bought a house before 2020, congratulations—you’re basically coasting on capital gains. If you’re still renting, you’re fighting a rising tide. It’s not fair, and I’m not here to sugarcoat it. The percentiles just reflect that reality: those with assets (and time) are pulling away. You’re not lazy; you’re late to the game.
60s and beyond: The retirement mirage
Here’s where it gets sobering. For ages 65-74, the median net worth is around $250,000. That’s not a lot when you face 20+ years of medical bills and Netflix subscriptions. The bottom 25% have less than $50,000. The top 25% have over $1 million. The difference? A lifetime of compounding, luck, and maybe not divorcing twice. If you’re in your 60s and reading this, the data says to hope you have a pension or a wealthy sibling.
 What is the Average Net Worth by Age?
But let’s take a step back. These numbers can make you feel like a failure if you’re below the median. Please don’t. The “average” 30-year-old with $36,000 probably got help from parents. The “average” 50-year-old with $135,000 might have sacrificed travel and hobbies. Net worth percentiles measure money, not happiness, health, or the fact that you make your friends laugh until they snort.
So, what do we do with this?
Here’s my takeaway: use these percentiles as a compass, not a mirror. If you’re in your 20s and below the median, fine—focus on increasing your income and automating savings. If you’re in your 50s and behind, maybe adjust your retirement expectations or get a side gig you actually enjoy. The goal isn’t to be in the top 10%; it’s to be financially secure enough that a surprise car repair doesn’t ruin your month.
Mark, my graphic designer friend, eventually calmed down. He realized his 25th percentile status came from living in a high-cost city and prioritizing travel over a down payment. “I’ve been to 15 countries,” he told me, “and I have zero regrets.” And you know what? That’s a net worth you can’t calculate. So check the percentiles, laugh at the absurdity, then go build a life that makes the numbers feel less important. You’ll thank yourself later.
