How Are Assets And Liabilities Connected To Net Worth

Let’s be honest: words like “assets,” “liabilities,” and “net worth” can sound like something only a banker in a stuffy suit would care about. But here’s the secret—they’re ac...

Let’s be honest: words like “assets,” “liabilities,” and “net worth” can sound like something only a banker in a stuffy suit would care about. But here’s the secret—they’re actually about you, your favorite coffee mug, and that tiny credit card bill you keep meaning to pay. Once you see how they’re all connected, it’s like unlocking a cheat code for your own life.
Think of your net worth as the score in a very personal video game. Assets are your power-ups, and liabilities are the pesky obstacles that slow you down. The score goes up when you collect more power-ups than you hit obstacles. Simple, right?
So, What Exactly Are Assets?
An asset is anything you own that puts money in your pocket or could be turned into cash. This includes your savings account, the car you own outright (not the one you’re still paying off), and even that vintage guitar you inherited from your uncle. If you can sell it or use it to make money, it’s an asset.
Must Read
Let’s use a real-life example. Imagine Lisa, who just got a birthday card from her grandma with $50 inside. She sticks it in her desk drawer. Congratulations, Lisa—that $50 is now an asset. It’s money she can use whenever she wants.
Your assets don’t have to be huge to matter. That spare change jar on your dresser? That’s an asset, too. Every little piece of what you own that has value is a tiny part of your net worth puzzle.
And What About Liabilities?
Liabilities are the opposite. They’re everything you owe—the money that you have to give back. This includes your student loan, the balance on your credit card after that sneaky online shopping spree, and your mortgage. Liabilities are basically the anchors that pull your boat downward.
 What Your "Net Worth" Is, Why You Should Always Know It, & How To
Take our friend Lisa again. She also has a library fine of $10 she forgot about. That $10 is a liability—money she needs to hand over. Even though it’s small, it’s like a tiny hole in her pocket. The bigger the liability, the bigger the hole.
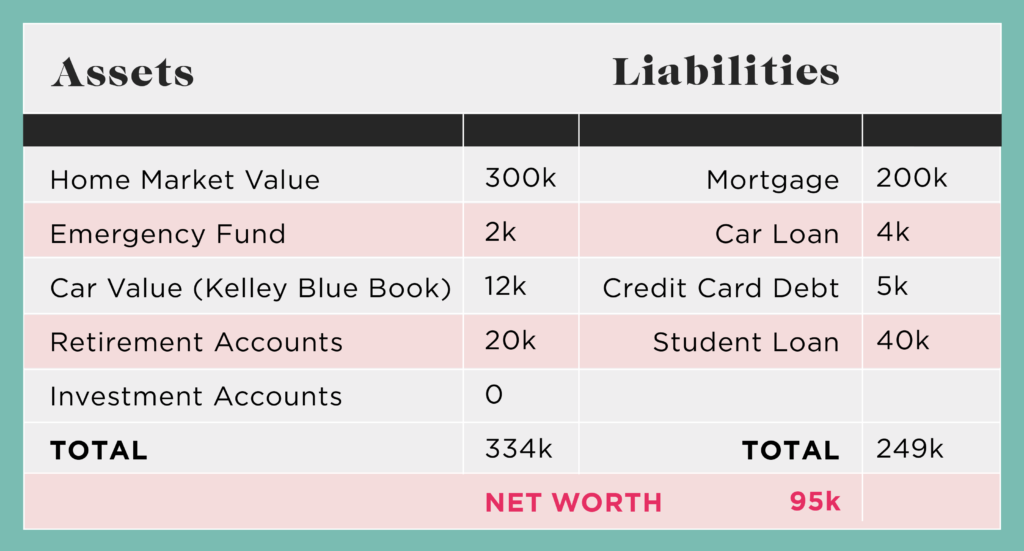
A common mistake is thinking your house is always a pure asset. If you still owe a huge mortgage on it, the value of the house is an asset, but the loan is a liability. You only count the difference.
The Simple Math That Connects Them
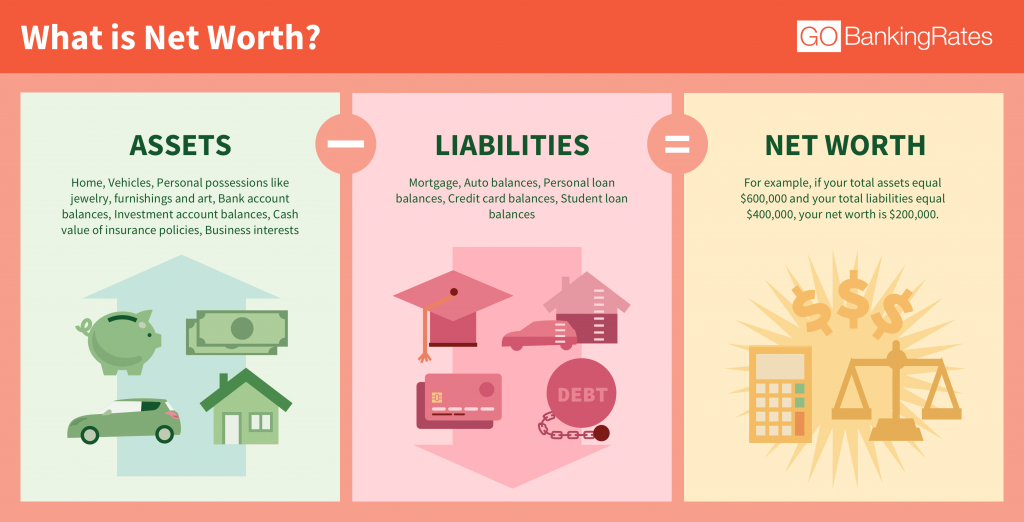
Here’s the golden formula you can whisper to yourself at the grocery store: Assets minus Liabilities equals Net Worth. That’s it. If your assets are bigger than your liabilities, your net worth is positive. If not, it’s negative—like being underwater financially.
Let’s do Lisa’s math. She has $50 (asset) minus $10 (liability) = a $40 net worth. Not bad! She’s in the green. Now imagine her friend Tom has a $500 video game console (asset) but also $600 in credit card debt (liability). His math is $500 - $600 = negative $100 net worth. Ouch.
 Net Worth: What Is It and How Do You Calculate It? | GOBankingRates
This connection matters because your net worth is a snapshot of your financial health at any moment. It’s not about being rich or poor; it’s about knowing where you stand so you can make better decisions tomorrow.
Why Should You Care About This?
Because it’s the easiest way to stop feeling anxious about money. When you understand that every time you pay off a liability (like a credit card) or gain an asset (like a savings bonus), your net worth grows, you start seeing progress. It’s like watching a plant grow—slow but satisfying.
It also helps you make smarter choices. You might decide to sell that old tablet you never use (turning it from junk into cash, an asset) instead of buying a new one on credit (which creates a liability). That one tiny decision can shift your net worth in the right direction.
 What’s Your True Financial Standing: Calculating Net Worth
Most importantly, it’s never about judgment. Everyone has a different starting point. The goal is just to make sure your assets are dancing and your liabilities aren’t dragging. Even a small positive net worth is a victory.
A Little Story to Make You Smile
Think of your neighbor, Bob. Bob is a classic “asset grower.” He buys a used lawnmower for $100 (an asset), mows lawns for $500, then pays off his $50 gas bill (a liability). His net worth climbs. Meanwhile, his brother Dave buys a new jet ski for $10,000 (a depreciating asset) using a loan (huge liability). Dave’s net worth sinks like a stone. Be Bob, not Dave.
The beauty is that you can start right now. Look around your room. Is there a book you can sell? A subscription you can cancel? That’s you managing your own net worth. It’s your life’s scoreboard, and you control the game.
So next time someone says “net worth,” don’t zone out. Smile, think of Lisa and her $40, and remember: assets are your friends, liabilities are your debts, and the difference is your financial superpower. Go ahead and calculate yours—you might just surprise yourself.
