How Do I Figure Out My Net Worth

So, you want to figure out your net worth. Maybe you heard a finance guru say it on a podcast, or you’re just wildly curious about your financial superhero status. Either way,...

So, you want to figure out your net worth. Maybe you heard a finance guru say it on a podcast, or you’re just wildly curious about your financial superhero status. Either way, welcome to the math party where the only calculator needed is you.
First, take a deep breath. This isn’t a test of your self-worth, okay? It’s literally just a subtraction problem. Think of it as the ultimate game of "What do I own?" vs. "What do I owe?" Spoiler alert: you probably own more than you think.
Step One: Gather Your Stuff (The Fun Part)
Grab a notepad, open a spreadsheet, or—if you’re feeling fancy—just shout numbers into your phone’s voice recorder. We’re making a list of everything you own that has monetary value. This is your Assets list.
Must Read
Start with the big ticket items: your checking and savings accounts, that 401(k) you’ve been feeding, and any investment accounts. Also, throw in the current value of your car (hint: it’s less than what you paid for it—sorry, depreciation is a party pooper).
Don’t forget the fun stuff! That vintage guitar you inherited, your comic book collection, or even the Beanie Baby you’re sure will fund your retirement. Be honest, not generous. Unless you have a signed first-edition Harry Potter, those Beanie Babies are worth about fifty cents and a nostalgic smile.
Step Two: The Reality Check (The Not-So-Fun Part)
Now, let’s look at the other side of the balance sheet: your Liabilities. This is everything you owe. It’s like the bill at the end of a really good meal—nobody loves seeing it, but you gotta face it.
Write down your mortgage, car loan, student loans, credit card balances, and that money you borrowed from your mom for concert tickets in 2019 (she hasn’t forgotten). Pro tip: Don’t include your Netflix subscription. That’s not a liability; that’s a survival expense for your social life.
 How to Increase Your Net Worth [7 Proven Strategies]
Total it all up. Feel a little knot in your stomach? That’s normal. Remember, this is just data. Data doesn’t judge you. It just sits there, looking very numerical.
Step Three: The Magic Equation
Okay, put on your imaginary math hat. It’s subtraction time! Take your Total Assets and subtract your Total Liabilities. What’s left? That’s your net worth.
If the number is positive, congratulations! You are a financial superhero. High-five yourself, maybe buy a celebratory coffee. If the number is negative? Breathe. You are not alone, and you are not doomed. Most recent grads and early-career humans have a negative net worth. It’s just a snapshot, not your life sentence.
Think of it like this: your net worth is like the numbers on your car’s dashboard. If it says "E" for empty, you don’t sell the car. You just drive to the nearest gas station. You’re the driver. You can always refuel.
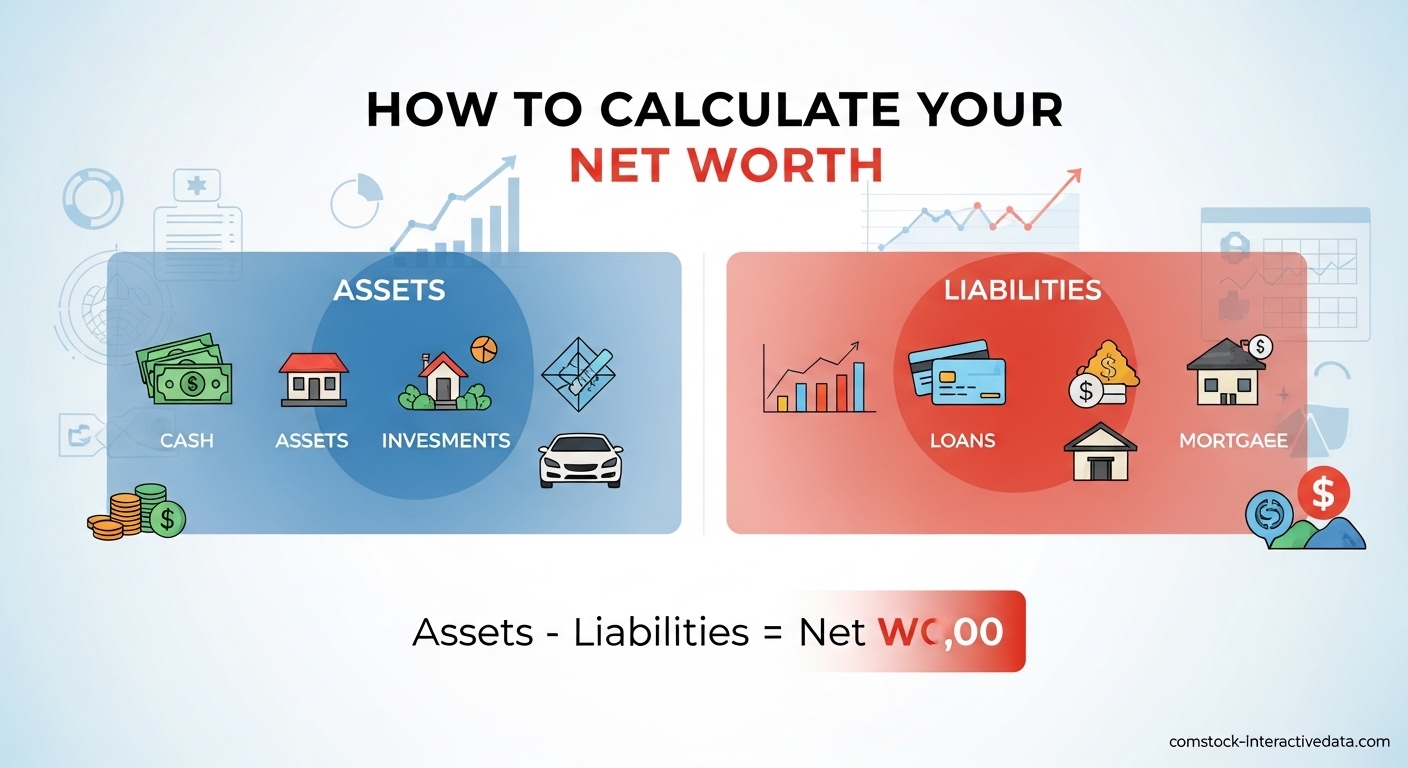 How to Calculate Your Net Worth and Why It Matters (August 2026)
But Wait, What About My House?
Great question! Your house is an asset—but only for its current market value, not what you paid for it. And that mortgage? That’s a liability. Do not count the house twice. The house is the asset; the loan is the debt. You’re just left with your slice of ownership.
Here’s a joke: What do you call someone who counts their house as pure wealth? A homeowner with a very friendly calculator. (Sorry, I couldn’t resist.)
How Often Should You Do This?
Once a month? Overkill. Once a year? Perfect. It’s like a financial birthday. You check in, see how you’ve grown (or shrunk), and then move on with your life. Don’t obsess over daily fluctuations—the stock market is drunk, and your car value is eternally sad.
And please, please don’t compare your net worth to your friends’ net worth. They might be lying, or they might have a trust fund from Grandpa Gerald. Your journey is your own.
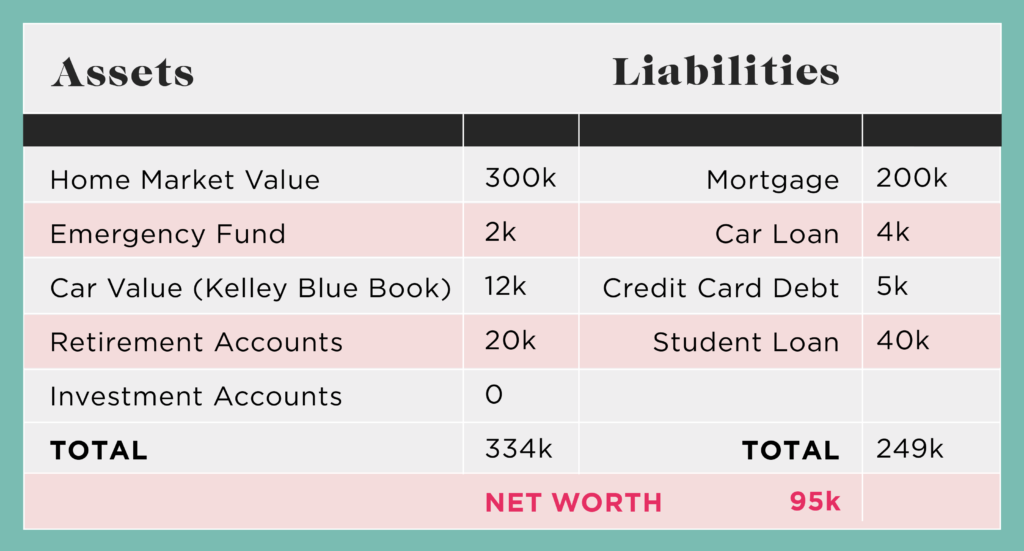 What Your "Net Worth" Is, Why You Should Always Know It, & How To
What If It’s Ugly? (A Small Crisis Guide)
So you did the math and the number is, let’s say, minus $15,000. Don’t panic. Don’t burn your calculator. This is not a report card on your soul. It’s simply a starting point.
You can make it less ugly by paying down high-interest debt (hello, credit cards) and adding to your savings. Even fifty bucks a month changes the story. Small steps turn a negative into a positive faster than you’d think. It’s like whittling a log—you won’t see progress for a while, then suddenly: a wooden spoon.
Uplifting Conclusion (The Dessert)
Here’s the beautiful truth: Your net worth is not your self-worth. It’s just a number that changes with every paycheck, every debt payment, and every wise (or silly) purchase. You are so much more than a spreadsheet row.
So go ahead, calculate your net worth today. If it’s tiny, laugh at it. If it’s negative, give it a name—“Steve”—and tell Steve he’s on notice. And if it’s huge? Awesome—don’t forget to enjoy it. Money is just a tool, not a trophy. You are the one building the life around it.
Now, close that calculator, go pet a dog, and remember: you’re richer than you think—especially in snacks, memes, and bad puns. Congrats, you just leveled up.
