How Do You Calculate Net Worth Of A Person

Let’s be real: when someone mentions net worth, most of us picture a billionaire’s yacht or a celebrity’s diamond collection. But calculating your own net worth is far less in...

Let’s be real: when someone mentions net worth, most of us picture a billionaire’s yacht or a celebrity’s diamond collection. But calculating your own net worth is far less intimidating—and way more useful—than you might think. Think of it as your personal financial health score, not a judgment on your life choices.
At its core, net worth is brutally simple: it’s everything you own minus everything you owe. The formula is Assets – Liabilities = Net Worth. That’s it. No complex math, no hidden fees, just a snapshot of where you stand financially at this very moment.
So, grab a coffee, open a notes app, and let’s walk through it like you’re curating a playlist. First up: assets. These are your financial pluses: cash in checking and savings, investment accounts, retirement funds, your car’s market value, and your home’s estimated worth. Don’t forget that vintage guitar or your collection of signed first-edition books—if you could sell it, it counts.
Must Read
Now for the less fun part: liabilities. This is your debt—credit card balances, student loans, car loans, mortgage, and any personal loans you owe. Be honest with yourself here; ignoring the credit card balance won’t help you get that Zen lifestyle you’re after. The goal is clarity, not shame.
Here’s a fun fact: Jay-Z once said, “I’m not a businessman, I’m a business, man.” He was talking about his net worth strategy—turning art into assets. You don’t need a Roc Nation empire to apply this. Even small side hustles or a well-invested savings account build your asset column over time.
The Nuance Nobody Talks About
Net worth isn’t static. It’s a living number that shifts with the stock market, your spending habits, and even the season (hello, holiday credit card bills). Don’t compare your figure to someone else’s—compare it to your own past self. A rising net worth over time is the real win.
Think of it like your closet. You don’t wear everything at once, but you know what’s there. Your net worth is the same: it’s the total value of your “wardrobe,” not just what you’re wearing today. And just like a good capsule wardrobe, quality assets matter more than quantity.
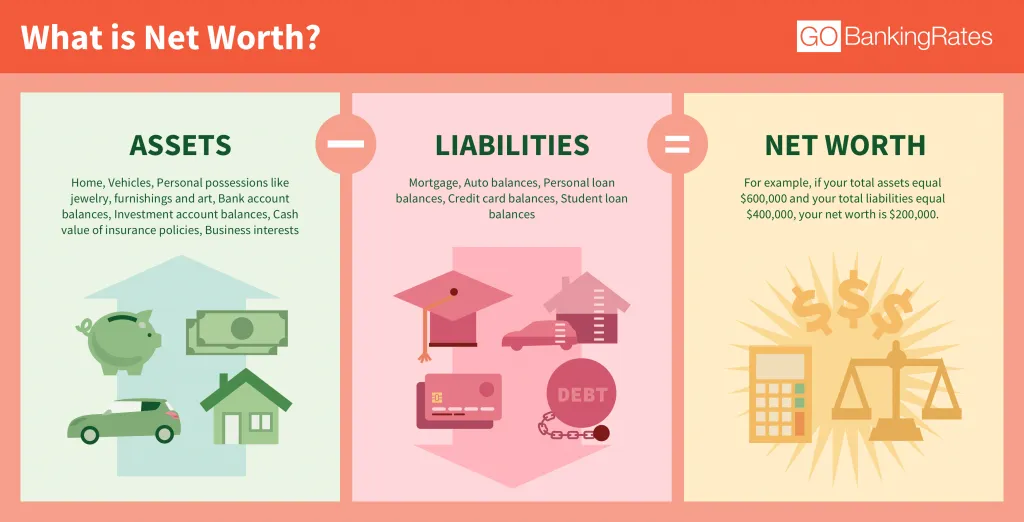 Net Worth: What It Is and How To Calculate It | GOBankingRates
Here’s a practical tip that feels like a life hack: calculate your net worth quarterly. Set a calendar reminder for the first day of January, April, July, and October. It takes ten minutes and gives you a pulse on your financial trajectory. You’ll start spotting patterns—like that post-vacation spending spike.
The Emotional Side of Numbers
It’s easy to feel anxious about this process, especially if the number is lower than you’d hoped. But here’s the secret: a low net worth doesn’t mean you’re failing. It means you have a starting point. In fact, most people under 40 have a net worth in the tens of thousands, not millions. The real indicators are direction and consistency.
Remember the scene in The Wolf of Wall Street where Leonardo DiCaprio’s character is manic about his wealth? That’s the extreme—and not the vibe we’re going for. Instead, take inspiration from Warren Buffett, who still lives in the same house he bought in 1958. His net worth is massive, but his daily life is modest. Use your net worth as a tool, not a trophy.
One clever way to boost your number without a huge raise? Reduce your liabilities. Paying off a $5,000 credit card balance increases your net worth by exactly $5,000—same as earning $5,000 more in savings. It’s like finding money under your couch cushions, but legit.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
Let’s Do the Math
Let’s build a quick example: Imagine you’re a freelance graphic designer in Austin. Your assets: $8,000 in savings, $15,000 in a Roth IRA, a car worth $10,000, and a laptop worth $2,000. Total assets = $35,000. Your liabilities: $3,000 on a credit card and $12,000 left on your car loan. Total liabilities = $15,000. Your net worth = $20,000. Not bad for a creative soul.
Now, what if you add a $1,000 debt payment next month? Your liabilities drop to $14,000, and your net worth jumps to $21,000. That’s progress you can feel. It’s like leveling up in a video game—small wins stack into big numbers.
Fun fact: Taylor Swift is reportedly a net worth of $740 million. But here’s the kicker—most of her wealth isn’t in cash. It’s in music catalogs, real estate, and touring revenue. Your net worth doesn’t need to be liquid; it just needs to be real.
When Culture Meets Finance
In many cultures, net worth is tied to community and land. In Japan, for instance, kakeibo (a simple household accounting method) focuses on mindful spending, not just accumulation. In Latin American families, property and inheritance often form the backbone of generational wealth. Your net worth story is uniquely yours—honor it.
 Statement of Net Worth: A Step-by-Step Guide
Another cultural reference: remember when Kanye West famously claimed to be $53 million in debt? That was a liability-heavy net worth moment. But he leveraged that debt into creative assets (like Yeezy). The lesson? Debt isn’t always a villain—it depends on what you’re using it for. Just be careful you’re not buying liabilities that look like assets.
The Reflection That Sticks
After you calculate your net worth, don’t obsess over the number. Instead, ask yourself: Does this number reflect the life I want to live? A high net worth with zero joy is just a spreadsheet. A lower net worth with purpose, security, and freedom? That’s the real luxury.
Think of your net worth as a compass, not a destination. It tells you where you are so you can decide where to go next. Maybe you’ll pay off that lingering student loan. Maybe you’ll start a side project that turns into an asset. The point is to stay curious, not anxious.
So here’s the takeaway: your net worth is not your worth as a human. It’s just a tool—like a fitness tracker for your finances. Use it to improve, not to define. And next time someone drops the “net worth” bomb at a dinner party, you can smile and say, “Mine is a work in progress—and I’m proud of it.”
Now go ahead: open that notes app. Your future self will thank you.
