How Do You Find Out Your Net Worth

Okay, let’s talk about net worth. It sounds terrifying, right? Like something only for Wall Street wizards or people who own yachts. But trust me, it’s not a scary math test....

Okay, let’s talk about net worth. It sounds terrifying, right? Like something only for Wall Street wizards or people who own yachts. But trust me, it’s not a scary math test.
Figuring out your net worth is actually freeing. It’s just a snapshot of your financial health. Think of it as a financial selfie, not a full-blown identity audit.
What Even Is Net Worth?
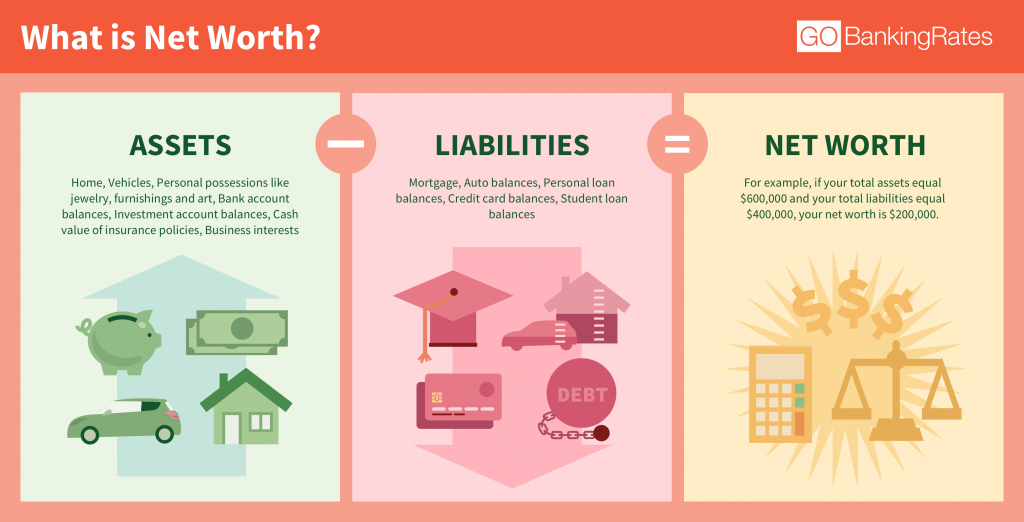
Here’s the super simple recipe. Take everything you own that’s worth money. That’s your assets.
Must Read
Then, subtract everything you owe. That’s your liabilities. The leftover number? That’s your net worth.
It can be positive (yay!) or negative (a wake-up call). And most importantly, it’s a starting point, not a final grade.
Step One: Gather Your "Stuff" (Assets)
Grab a coffee. Actually, grab two. You’ll feel fancy. Now, list out everything that isn’t bolted down and has cash value.
Start with the big ones. Your checking and savings accounts. Your retirement accounts (401k, IRA, that weird pension from an old job). Your investment accounts (stocks, crypto you bought on a whim).
Don’t Forget the Weird Stuff
Your car. Yes, that slightly dented sedan. Use Kelley Blue Book for a realistic value, not your sentimental “it’s my baby” price. Your home, if you own it. Use Zillow or a recent appraisal.
Then, the fun category. That vintage guitar you never play. Your comic book collection. Your emergency fund. Even that $200 you loaned your cousin Dave (I’d count it, but I also wouldn’t hold my breath).
 How to Calculate Your Net Worth: Step-by-Step Guide
Add it all up. Don’t worry if the number is small. Small numbers are just cozy.
Step Two: Face the "Owes" (Liabilities)
This part feels like checking your texts after a bad night out. Do it anyway. Breathe.
List every single debt. Your mortgage balance. Your student loans (the ones that follow you like a sad ghost). Your credit card balances. Any car loan, personal loan, or buy-now-pay-later thing you forgot about.
That subscription to a gym you haven’t visited since 2019? Not a debt. The balance on that subscription? That is a debt.
Add them all up. This number might sting. That’s okay. We’re just observing, not judging.
Step Three: The Scary Math (It’s Not Scary)
Now, do the subtraction. Total Assets minus Total Liabilities. Boom. That’s your net worth.
 Statement of Net Worth: A Step-by-Step Guide
If it’s negative, you’re not alone. Like, really not alone. Most people start here. It just means you owe more than you have right now. It’s a map, not a tombstone.
If it’s positive, give yourself a high five. Maybe buy a celebratory donut. You’re building wealth, you money ninja.
Why Bother Doing This?
Because you can’t improve what you don’t measure. This is your financial GPS. It tells you if you’re driving toward Las Vegas or a ditch.
Checking your net worth yearly (or even quarterly) keeps you honest. It’s the difference between hoping you’re fine and knowing you’re fine.
Plus, it’s oddly satisfying. Like tracking steps, but for your wallet. You get to see your progress in real numbers.
Pro Tips for the Slightly Lazy
Use an app. Mint, Personal Capital, or even just a spreadsheet do the heavy lifting. They link to your accounts.
 Determine Your Net Worth in 3 Easy Steps! - New Century Investments
Don’t include personal belongings like your laptop or your socks. Unless you’re a tech reseller with 500 laptops, just skip it. It’s too annoying to track.
Also, don’t worry about the exact dollar. A rough estimate is fine. You’re not launching a rocket; you’re checking your vibes.
The Real Secret
Your net worth is just a number. It doesn’t measure your kindness, your taste in movies, or how good you look in sweatpants. It’s a tool, not a tattoo.
The goal isn’t to have a huge net worth tomorrow. The goal is to have a bigger net worth than you did last year. Even if it’s just $50 bigger. That’s a win.
So go ahead. Do the math. It takes ten minutes. You might surprise yourself. Or you might get a reality check. Either way, you’re now the boss of your money.
And that’s way cooler than having a yacht. (Okay, maybe not, but it’s a solid start.)
