How Do You Work Out Your Net Worth

Last week, I nearly had a heart attack over a burrito. I’m standing there, staring at the menu, and I realize I’ve mentally categorized every dollar I have left until payday....

Last week, I nearly had a heart attack over a burrito. I’m standing there, staring at the menu, and I realize I’ve mentally categorized every dollar I have left until payday. It was a pathetic inventory: “Okay, one burrito equals no coffee tomorrow.” That’s when it hit me—I had no idea what my actual net worth was. I knew my checking account balance (not great), but that’s like knowing the color of your car’s paint while the engine is on fire.
So, how do you actually work out your net worth without wanting to crawl under a rock? It’s simpler than you think, and no, you don’t need an accounting degree. You just need a calculator, a little honesty, and the guts to face the numbers. Let’s break it down, side-eye included.
Step One: Add Up Everything You Own (The Fun Part)
Start with your assets. That’s fancy talk for “stuff you could sell for cash.” Your savings account, your checking account, that random $50 your grandma gave you for your birthday that’s still in your sock drawer. Write it all down.
Must Read
Then, add the big-ticket items. Your car (check Kelley Blue Book, not your emotional attachment), your house (estimated value, not what you paid in 2005), and yes, even that guitar you haven’t touched since college. Include your retirement accounts—401(k), IRA, whatever—because that money is still your money, even if it’s officially “off limits” until you’re old.
Side note: Please don’t count your collection of Beanie Babies. I love that you have a Patti the Platypus, but she’s not paying your rent. Be realistic, or you’re just lying to yourself.
What About That Vintage Lamp?
If you can sell it in under a month for cash, count it at a conservative estimate. That vintage lamp? Maybe $40, not the $150 you saw on Etsy. Your sanity will thank you later.
 Outside Net Worth Calculation at Taj Miller blog
Step Two: Add Up Everything You Owe (The Honest Part)
Now for the part that requires a deep breath (and possibly a glass of wine). List your liabilities—that’s everything you owe. Credit card debt, student loans, car loans, mortgage, the $50 you owe your friend for pizza last weekend. Yes, that counts.
Write them all down with their current balances. Don’t round down. That $12,743 student loan is not “about $12,000.” Trust me, the bank knows the exact number. Precision matters here, even if it stings.
If you have a mortgage, include that too. It’s scary, but it’s also necessary math. You can’t know your net worth without seeing the whole picture, bad hair day and all.
 How to Calculate Your Net Worth: A Simple Guide – Accounting Basics
Step Three: Do the Simple Subtraction
Here’s where the magic (or panic) happens. Take your total assets and subtract your total liabilities. That number—could be positive, could be negative—is your net worth. It’s that simple: Assets minus Liabilities equals Net Worth. No spreadsheet wizardry required.
If the number is negative, don’t panic. Seriously, don’t. Most people under 40 have a negative net worth because of student loans and mortgages. You’re not a failure; you’re just in the middle of the game. Negative means you owe more than you own, but now you know where you stand.
If it’s positive? Nice work! You’re ahead of the curve. But don’t get cocky—net worth is a snapshot, not a movie. It changes every time you spend or save.
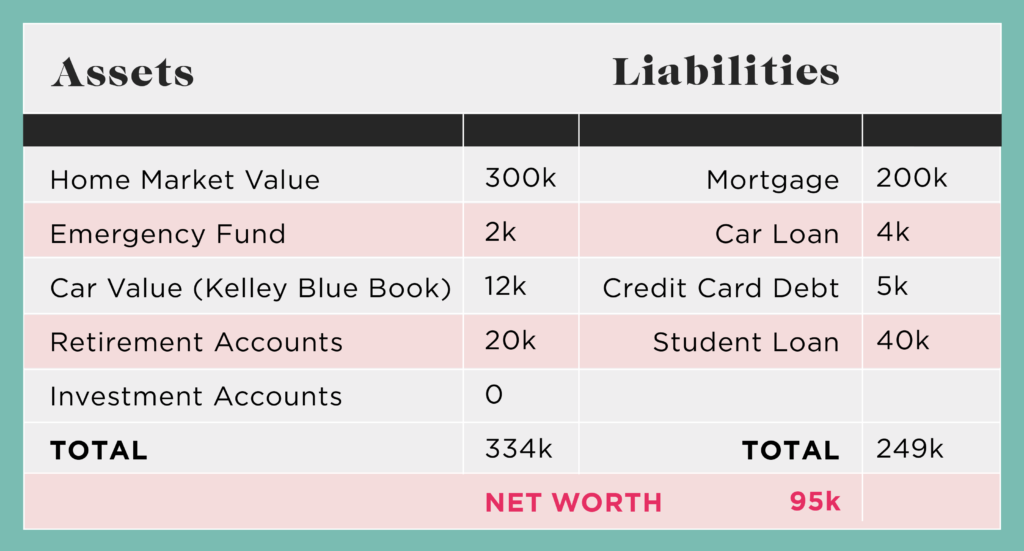 What Your "Net Worth" Is, Why You Should Always Know It, & How To
Why Bother? (Because Ignorance is Expensive)
Knowing your net worth is like having a healthcare check-up for your wallet. You wouldn’t ignore a weird mole, right? Ignoring your financial health is way more dangerous because it leads to bad decisions—like buying a car you can’t afford or skipping that 401(k) match.
Plus, tracking it over time is weirdly motivating. When I first did this, my net worth was a sad, negative number. Six months later, after paying down a credit card, it had moved. I literally cheered out loud. Numbers don’t lie, but they also give you a game plan.
A Quick Reality Check
Your net worth is not your self-worth. Repeat after me: I am not a balance sheet. I once had a negative net worth and still ate fancy cheese. You can be broke and happy, or rich and miserable. But knowing the number gives you power over it, not the other way around.
So, grab a napkin, a notes app, or that old receipt in your pocket. Write down what you own, what you owe, and subtract. You might be surprised, humbled, or a little bit proud. Either way, you’ll know exactly where you stand—and that’s worth more than any burrito.
