How Is Net Worth Of A Person Calculated

Alright, let’s be real for a second. The term “net worth” can sound stuffy, like something whispered in mahogany-paneled boardrooms or on financial news tickers. But I promise...

Alright, let’s be real for a second. The term “net worth” can sound stuffy, like something whispered in mahogany-paneled boardrooms or on financial news tickers. But I promise you, it’s actually one of the most fun and empowering numbers you’ll ever calculate. It’s your personal scoreboard, a snapshot of your life in dollars and cents—and you get to be the star player. Ready to turn a boring finance term into your new favorite game? Let’s dive in.
The Simple, No-Sweat Formula
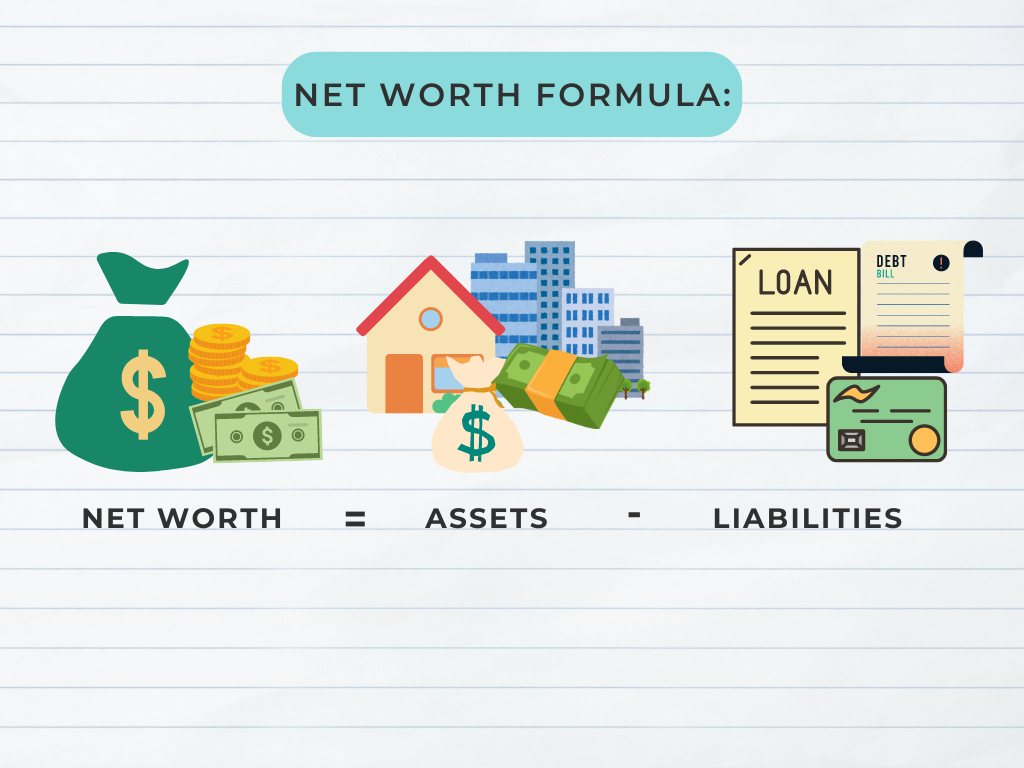
Here’s the secret, and it’s almost embarrassingly simple: Net Worth = What You Own minus What You Owe. That’s it! No wall street wizardry, no complex algorithms. Think of it like a tug-of-war. On one side is everything you’ve built up, and on the other side is what’s holding you back (debts, we’re looking at you). The result? A number that tells you how strong your rope is getting. And guess what? You can pull the rope any way you want.
Step One: The Treasure Chest (Assets)
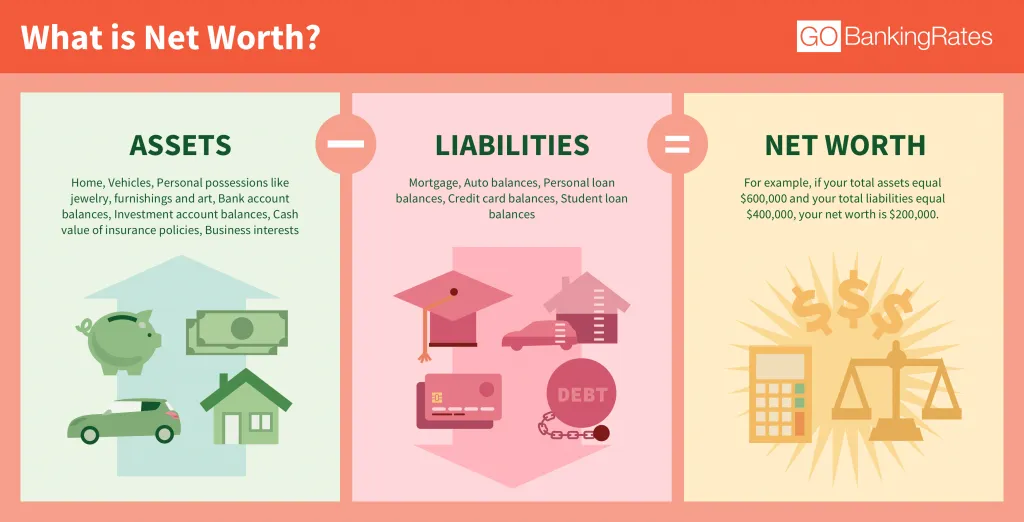
First, grab a list of everything you own that has value. This isn’t about being flashy; it’s about being honest. Start with the big stuff: your house (what could you sell it for today?), your car (check Kelley Blue Book, not your dreams), and your retirement accounts (401(k), IRA—the whole enchilada). Then, don’t forget the medium-sized gems: your savings account, that small investment portfolio, and even the cash value of a life insurance policy if you have one.
Must Read
Even your trusty laptop, a vintage guitar, or that comic book collection might count! The rule? If you could sell it for cash in less than a year, it belongs here. It feels surprisingly good to realize that your diligent saving is actually a pile of treasure hiding in plain sight. Suddenly, that “boring” bank account feels like a chest of gold doubloons.
Step Two: The Unwanted Baggage (Liabilities)
Now for the less thrilling part—but don’t worry, we’ll keep it short. List everything you owe. This is your mortgage balance, your credit card balances, student loans, car loans, and that money you borrowed from Mom for the security deposit (we see you). This is not a time for shame—it’s a time for clarity. Think of it as a map revealing where your treasure is being siphoned off by pirate ships (interest payments). The more you see the ropes, the easier it is to cut them.
 A Simple Guide to Calculating Your Net Worth - bestbuhay.com
Do the Math, Then Pop the Confetti
Subtract your total liabilities from your total assets. You might get a big positive number (awesome!) or a negative one (totally normal in early life!) . The key isn’t the number itself today—it’s the direction you’re moving. If you tracked it again in six months, is your net worth higher? Are you buying fewer gadgets and paying off more debt? That’s the real win. It turns a dreaded finance chore into a personal progress bar, like an experience points system for real life.
Why This Makes Life More Fun (Seriously)
Knowing your net worth transforms you from a passive passenger to the pilot of your financial plane. When you see a big number, you get to ask: “What if I invested that to work for me?” When it’s smaller, you get to play a game: “How can I shrink my liabilities and boost my assets this quarter?” It’s not about being rich overnight; it’s about building momentum. And momentum is deeply satisfying.
 Net Worth: What It Is and How To Calculate It | GOBankingRates
Think of it this way: every time you pay off a tiny credit card, your net worth jumps a little. Every time you skip the fancy latte and invest ten bucks, your net worth chuckles with delight. You start to see your life as a series of tiny, joyful victories. It’s like a video game where the only cheat code is consistent action.
The Uplifting Finale
So, here’s the beautiful truth: your net worth is not your worth as a human being. It’s just a tool, a mirror that shows where your money currently lives. But using that mirror, you can sculpt your future. You can decide today to increase your assets by 1% or reduce a debt by 1%. That tiny shift starts a chain reaction. It’s the most hopeful metric in the world because it can always be improved. So grab a calculator, a piece of paper, and five minutes of your time. Calculate your number, smile at it, and then ask yourself: “What’s my next adventurous move?” Because your financial story is yours to write, and the best page is always the blank one ahead.

