How Is Your Net Worth Calculated

You’ve probably heard the term net worth thrown around like confetti at a billionaire’s birthday party. But stripping away the jargon, it’s actually the simplest math you’ll e...

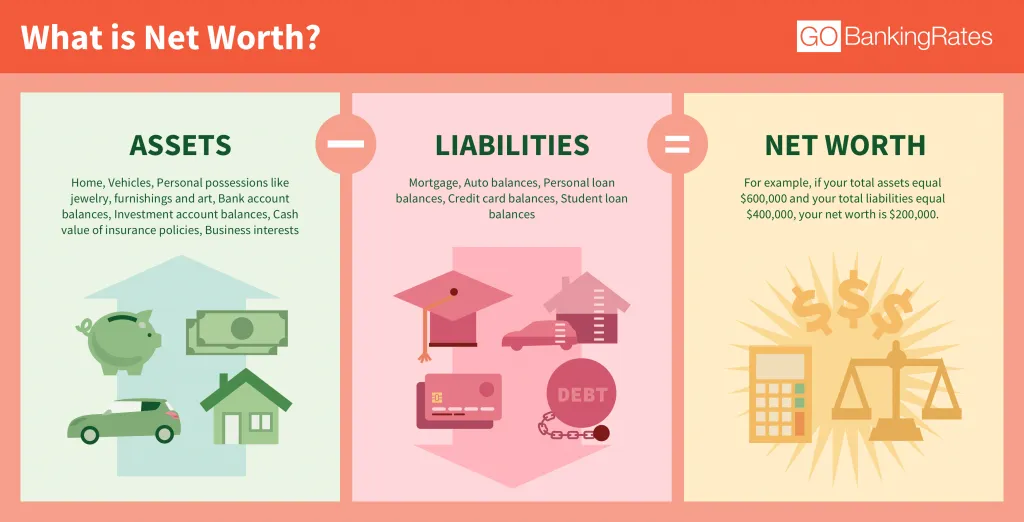
You’ve probably heard the term net worth thrown around like confetti at a billionaire’s birthday party. But stripping away the jargon, it’s actually the simplest math you’ll ever do: what you own minus what you owe. Think of it as your financial report card, but way less stressful than that algebra final you tried to forget.
The magic formula is deceptively clean. On one side, tally up your assets: cash, investments, your car, your 401(k), even that vintage guitar you swear will fund your retirement. On the other side, list your liabilities: student loans, credit card balances, your mortgage, and that IOU from your friend’s wedding fund.
Subtract the second number from the first. That’s it. If you get a positive number, you’re in the green. Negative? Don’t panic—many of the most successful people started there, including a certain musician who famously lived on ramen while building a publishing empire.
Must Read
The Line-By-Line Breakdown (No Calculators Required)
Let’s start with assets. This isn’t just your bank account balance—it’s anything you could sell for cash. Your home equity (the market value minus what you still owe on the mortgage) counts. So does your emergency fund, your stock portfolio, and even the cash value of a life insurance policy.
Now, liabilities. This is the part where honesty reigns. Include that credit card debt you swore you’d pay off last summer. Include the car loan, the student debt you tell your parents is “almost done,” and the interest you’re still paying on that furniture financing from 2021.
Here’s a fun cultural fix: Think of your net worth like a Stranger Things Upside Down. The top (your assets) looks rosy, but the shadowy version (your debts) can flip everything upside down. Balance is the goal.
Why Your House (Probably) Isn’t a Win-Win
Your home’s value is an asset, but that monthly mortgage payment is a liability. Don’t double-count it. Real estate can boost your net worth, but it’s not liquid cash—so don’t start planning that yacht trip just yet.
 Net Worth: What It Is and How To Calculate It | GOBankingRates
For example, if your house is worth $500,000 but you still owe $400,000, your equity is $100,000. That’s your net contribution. If the market crashes and it’s worth $350,000, your asset shrinks faster than a wool sweater in a hot dryer.
Practical tip: Use online tools like Mint or a simple spreadsheet. Update your net worth quarterly—not obsessively, but enough to catch trends. It’s like checking your car’s oil; you don’t need to do it every day, but ignoring it is a recipe for a stalled engine.
The Net Worth of Famous People (And Why It’s Weird)
Celebrity net worth is the gold standard of financial fiction. That number you see on a gossip site? It’s usually a guess based on movie deals, real estate, and a lot of maybe. For instance, Jay-Z’s net worth is often estimated at $2.5 billion, but does he have that in cash? Unlikely.
Most of it is tied up in illiquid assets—art, business stakes, and bottles of Armand de Brignac that are aging in a vault. If you tried to sell all of it tomorrow, the market would tank and his real net worth would be a fraction of the rumor.
Fun fact: When Mark Zuckerberg first appeared on the Forbes list, his net worth was based on Facebook’s private valuation—which changed every time he had a good lunch. Today, it’s a more stable (but still volatile) public stock.
 Net Worth Formula - What is Net Worth Formula? , Examples
The “Wealthy vs. Rich” Trap
Don’t confuse net worth with cash flow. A doctor making $400,000 a year can have a lower net worth than a retiree who owns a paid-off $2 million home. The doctor has high income but also high student loans, a big mortgage, and a taste for luxury SUVs.
The retiree might only have a pension of $40,000, but their assets (house, savings, maybe a rental) beat the doctor’s liabilities. That’s why net worth is a better measure of financial health than your paycheck. It’s the long game, not the monthly sprint.
Practical tip: Focus on increasing your assets while shrinking your liabilities. Pay off high-interest debt first (credit cards, payday loans) because they act like a tax on your future self. Then, invest in assets that grow, like index funds or a diversified portfolio.
The Fun Part: Small Wins Add Up Quickly
Here’s a little math that feels like magic. If you save $200 a month and invest it at a 7% average return (the stock market’s historical average), in 30 years you’ll have over $240,000. That’s not a lottery win—that’s just time and patience.
 Statement of Net Worth: A Step-by-Step Guide
And don’t underestimate the power of paying off a $5,000 credit card. Your net worth instantly jumps by $5,000 because that liability disappears. It’s like finding $5,000 in your couch cushions—except it was already yours, just hiding behind interest payments.
Cultural checkpoint: Think of your net worth like your Instagram grid. A few embarrassing posts from your early 20s? Delete them (pay off debt). Add more highlights (investments). The final number isn’t about being perfect—it’s about being real.
Daily Life Reflection: It’s Not a Scoreboard
Here’s the truth: your net worth today is not the measure of your worth as a human being. It’s a snapshot, not a life sentence. If you’re twenty-five and just starting, don’t stress if you’re in the red. That’s normal—and more common than you think.
What matters is the direction. Is your net worth trending up? If yes, you’re winning. If no, adjust. Life happens—a baby, a medical bill, a bad investment—but the math always works the same way. You just keep subtracting and adding.
So tonight, before you binge-watch your next show, take ten minutes. Open a spreadsheet. Write down your numbers. No judgment, just curiosity. Because that simple subtraction is the difference between feeling broke and actually building something. And that’s a lifestyle upgrade money can’t buy.
