How Much Of Net Worth Should Be In House

Let’s be real: your home is likely your biggest flex. It’s where you host game nights, binge-watch prestige TV, and hide from the world in your favorite sweatpants. But that s...
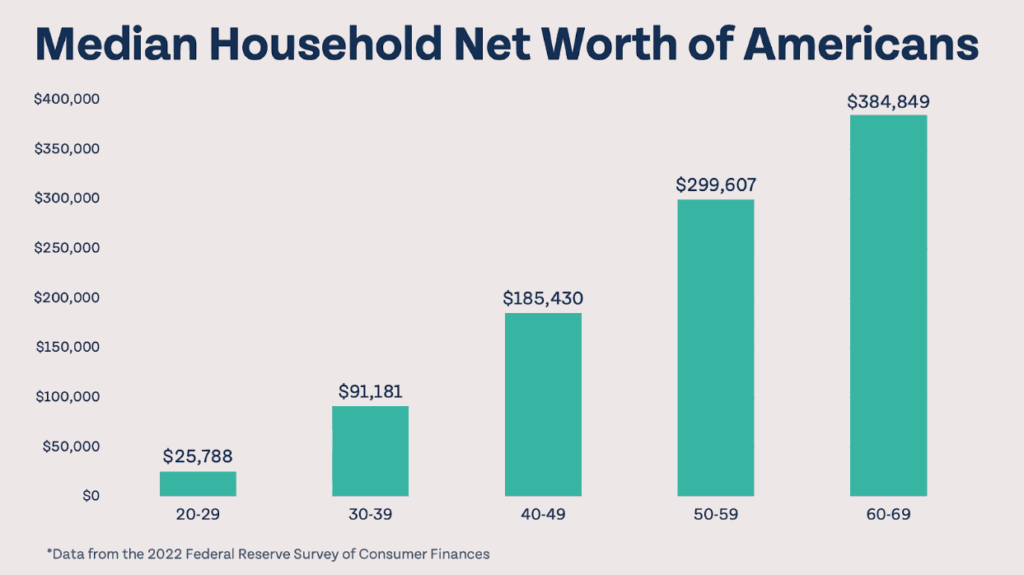
Let’s be real: your home is likely your biggest flex. It’s where you host game nights, binge-watch prestige TV, and hide from the world in your favorite sweatpants. But that same cozy sanctuary can also be a massive financial anchor—or a golden ticket.
So, how much of your net worth should be tied up in your house? The answer is juicier than a season finale of Succession. And spoiler alert: it’s not a one-size-fits-all number.
The Magic Number: 30% to 40% (But Don’t Get Trigger-Happy)
Financial planners often whisper a golden rule: keep your home equity between 30% and 40% of your total net worth. Think of it like a cocktail—too much house makes the mix bitter, too little leaves you wondering if you’re really adulting. For the average American homeowner, the home accounts for roughly 35% of their net worth, according to Federal Reserve data. That’s a cozy middle ground—unless you’re house-rich and cash-poor, which is the financial equivalent of wearing a tuxedo to a taco truck.
Must Read
Here’s the kicker: your home is a lifestyle asset, not an investment like stocks or bonds. It doesn’t pay dividends, buy you avocado toast, or fund your early retirement. It just sits there, looking pretty (and slowly appreciating). So keep that percentage in check, or you’ll be counting wall outlets as part of your retirement plan.
When Too Much House Feels Like a Trap
Imagine your net worth is a pizza. If you put 70% of it into a single giant slice labeled “house,” you’re left with tiny pepperoni bits for emergency funds, travel, and that spontaneous trip to Bali. This is the house-poor dilemma. You’re living in a marble-clad fortress but eating ramen in a tuxedo, because all your cash is locked in drywall. Financial guru David Bach calls this “householic syndrome,” and it’s basically the real estate version of buying a luxury car you can’t afford to fuel.
Fun fact: In 2023, a study by Clever Real Estate found that 18% of homeowners felt “house poor”—meaning they regretted their purchase because it squeezed out life’s little joys. Don’t be that person who has granite countertops but zero vacation days.
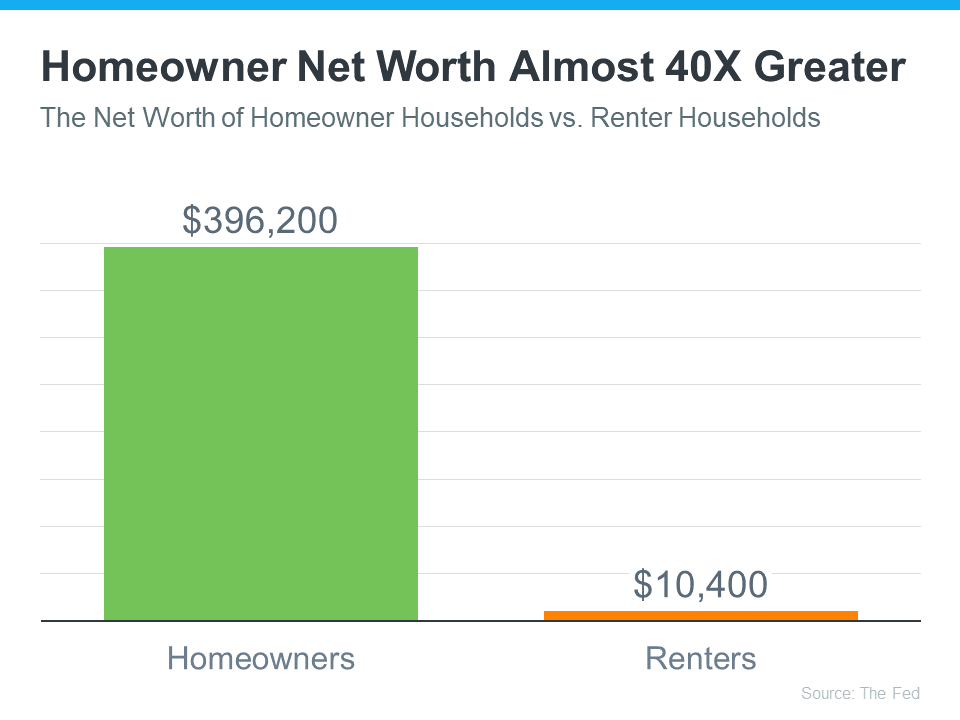 Homeowner Net Worth Has Skyrocketed
On the Flip Side: When Being Under-Housed Works
On the other end of the spectrum, some folks treat their home like a semi-permanent hotel room. They keep only 10% to 20% of their net worth in the house. This is the “I rent because I invest all my cash in S&P 500 and Bitcoin” crowd. It’s a valid strategy if you’re hyper-disciplined, but it comes with risks. Renting forever means you’re funding someone else’s mortgage, and rent hikes can crash your vibe faster than a flood alert on your phone.
A sweet spot? Consider buying a modest home in a fast-growing area. Your equity grows, but you still have cash left to, you know, live. Think Emily in Paris apartment energy—cute, functional, and not swallowing your whole bank account.
Practical Tips to Tame the Real Estate Beast
Tip one: Calculate your “house-to-life ratio.” Add up your home’s current market value (not what Zillow guessed last week) and divide it by your total net worth. If that number is over 50%, you might want to sell, downsize, or start a side hustle selling artisanal candles on Etsy.
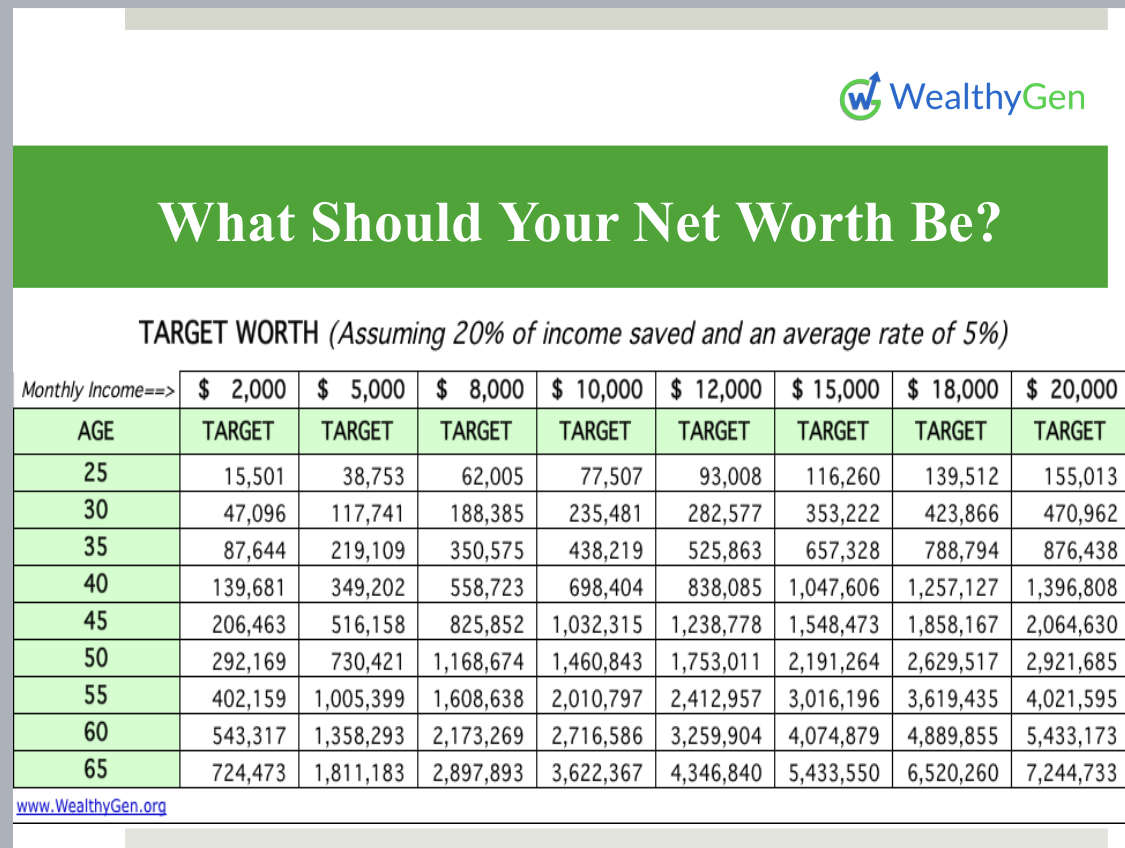 THIS IS WHAT YOUR NET WORTH SHOULD BE - WealthyGen Foundation
Tip two: Don’t count appreciation as a bankable guarantee. Real estate cycles are like Bridgerton seasons—exciting, dramatic, and unpredictable. Your house might double in value or get stuck in a 2008-style slump. Treat home equity as a safety net, not a lottery ticket.
Tip three: Diversify like you’re building a charcuterie board. You wouldn’t put just one type of cheese, right? So don’t put all your wealth into one house. Sprinkle in index funds, a high-yield savings account, and maybe a vintage motorcycle. Your future self will thank you.
Fun fact: In Japan, homes often depreciate in value like cars, because they’re built to be replaced every 30 years. Imagine selling your “lightly used” home for half what you paid—yikes! That’s why Japanese investors rarely count their home as a wealth builder. Lesson: location and culture matter when calculating your net worth sweet spot.
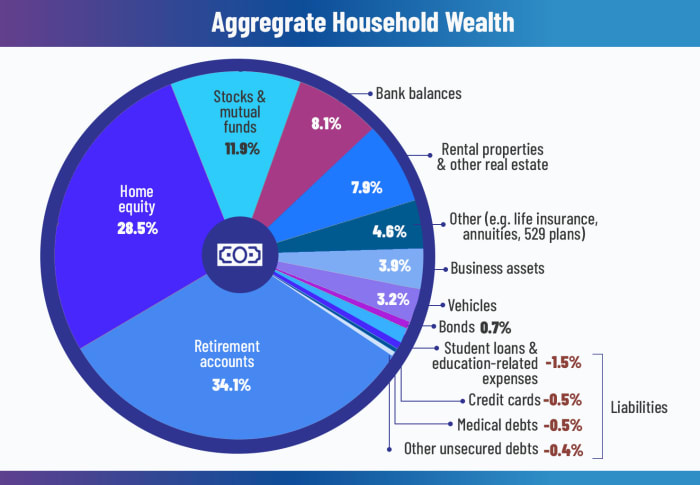 U.S. Net Worth: How Household Wealth Breaks Down - TheStreet
Cultural References to Keep It Real
Remember the opening scene of The Wolf of Wall Street? Jordan Belfort’s mansion is a monument to excess—and his eventual downfall. A house should never be a status symbol so big it becomes a trap. On the flip side, think of Marie Kondo’s approach: does your home spark financial joy? If it keeps you up at night worrying about mortgage payments, it’s time to downsize. Your home should feel like a sanctuary, not a spreadsheet.
And here’s a pop culture gem: In Crazy Rich Asians, the Young family’s mansion is jaw-dropping, but they also own hotels, art, and a gravy boat of diversified assets. That’s the goal—net worth that’s more Spongebob’s Krabby Patty secret formula than a single, fragile recipe.
The Final Reflection: What This Means for Your Morning Coffee
Here’s the truth bomb: your net worth isn’t a scoreboard. It’s a tool for living the life you want. If your house eats up 60% of your wealth but you still sleep soundly, travel once a year, and can handle a broken water heater without panicking—then okay, you do you. But if your mortgage feels like a weight that crushes your Sunday morning croissant, it’s time to recalibrate.
So next time you unlock your front door, ask yourself: Am I owning this home, or is it owning me? The answer is the difference between a mansion you love and a golden cage. Choose wisely, and keep your bank account as flexible as your yoga mat. After all, the best net worth is one that lets you afford both a roof and a life underneath it.
