How To Calculate Asset Net Worth For Fafsa

Let’s face it: the word “FAFSA” sounds about as fun as a root canal. But what if I told you that calculating your asset net worth could actually unlock a treasure chest of fin...
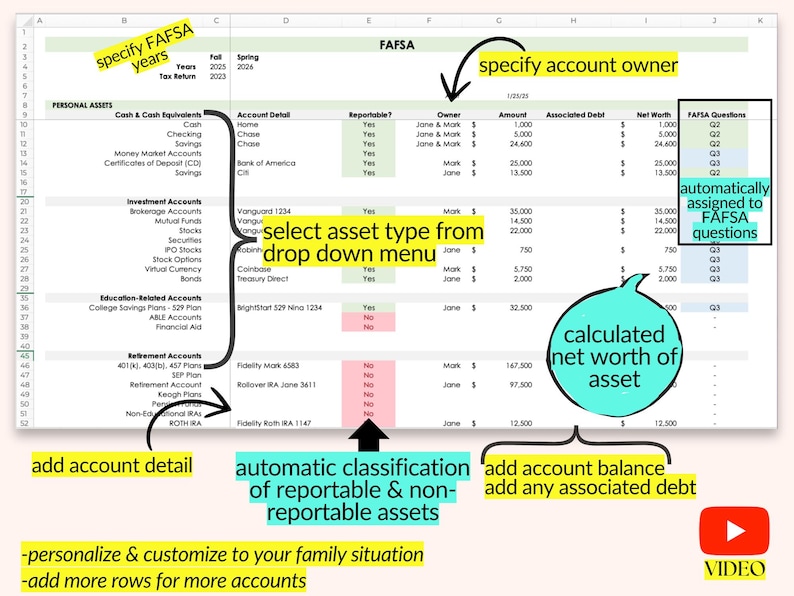
Let’s face it: the word “FAFSA” sounds about as fun as a root canal. But what if I told you that calculating your asset net worth could actually unlock a treasure chest of financial aid? It’s like playing a strategic board game—only the prize is tuition money.
Here’s the secret: FAFSA doesn’t want to know everything you own. It only asks for a specific slice of your financial pie. And once you understand the rules, the whole process feels less like a tax audit and more like a friendly math puzzle.
First, Know What “Counts” (and What Doesn’t)
FAFSA is surprisingly picky. They care about cash, bank accounts, investments, and real estate (excluding your primary home). Yes, your house is off the hook! So is your retirement account, life insurance, and even your family car.
Must Read
This means your real asset net worth is probably way smaller than you think. Isn’t that a relief? It’s like realizing you don’t have to count the chocolate stash in your pantry as “wealth.”
Step 1: Gather the “Big Three” Numbers
Start with your checking and savings account balances. Add up every single dollar sitting there today. Then, look at your investments—stocks, bonds, mutual funds, and any 529 plans (but only if the beneficiary isn’t the student).
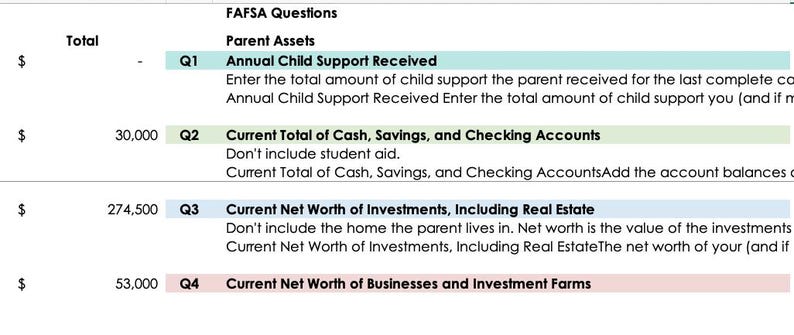 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
Don’t forget real estate investments like rental properties or land. But here’s the fun twist: FAFSA subtracts the debt you owe on that property from its current value. So if you own a rental worth $200K and owe $150K, you only report $50,000.
Step 2: The Simple Subtraction Trick
Write down all those numbers. Now, add them up. That’s your gross assets. Then, ask yourself: “What debts do I have that are tied directly to these assets?” For example, a margin loan on stocks or a mortgage on a rental property.
Subtract the debts from the assets. That’s your net worth for FAFSA. Voilà! It’s literally a subtraction problem, not a nightmare.
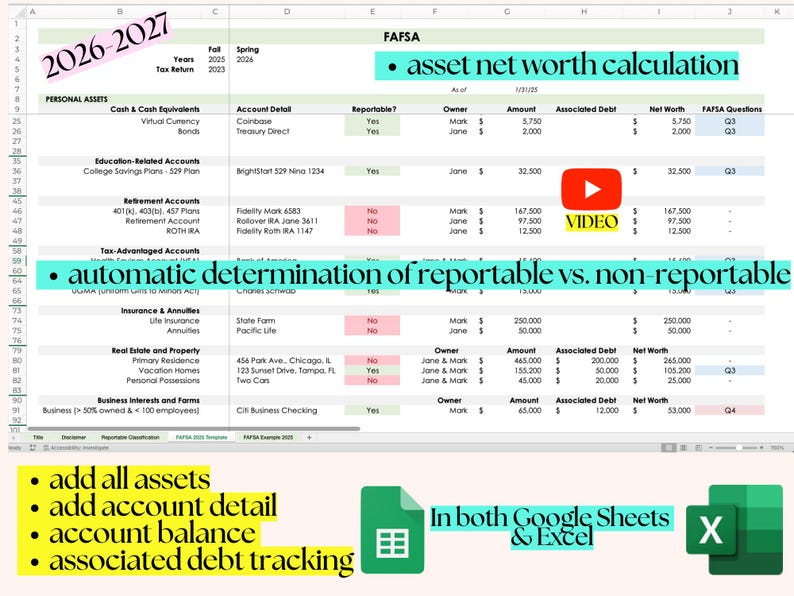 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
Why This Makes Life More Fun
Because once you calculate this number, you own the process. You’re no longer a scared applicant; you’re a financial detective. Plus, the lower your reported net worth, the more need-based aid you might qualify for. Isn’t it ironic that being “poor on paper” can feel like winning the lottery?
And here’s a little pep talk: Most families overestimate their assets. They panic about a fat 401(k) that FAFSA ignores entirely. So be brave. Do the math. You might discover you’re actually the underdog—and the system loves underdogs.
A Super Quick Example
Say you have $3,000 in a checking account, $7,000 in savings, and $10,000 in a stock portfolio. That’s $20,000. You also have a rental property worth $300,000 with a $250,000 mortgage. So you report $50,000 from that property. Total assets: $70,000.
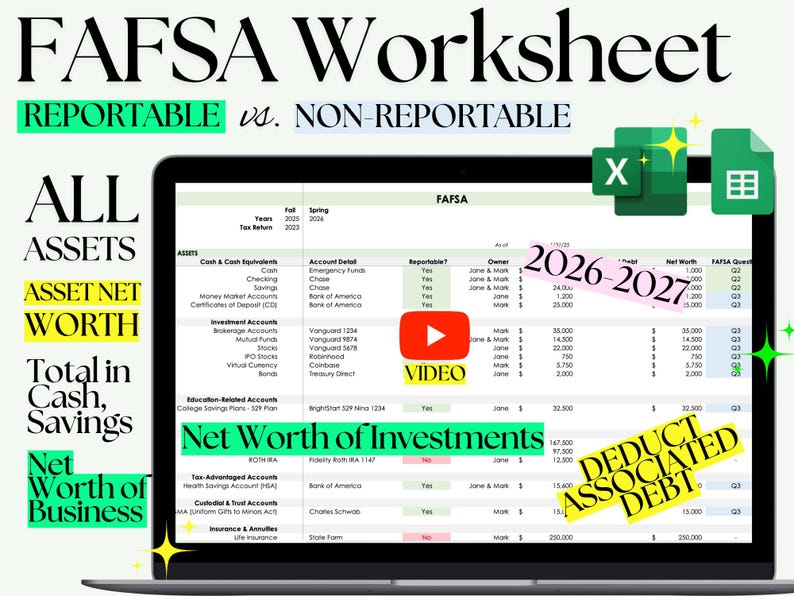 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
Now subtract any debt directly tied to those assets—in this case, just the $250K mortgage on the rental. Wait, that doesn’t work? Actually, you only subtract debt from the specific asset it belongs to. So your net worth here is $20,000 (cash) + $50,000 (net rental equity) = $70,000. See? Simple when you break it down.
Your Uplifting Takeaway
Calculating asset net worth for FAFSA is not a test of your worth as a person. It’s a numbers game, and numbers are just tools. The goal isn’t to hide money; it’s to tell the truth in a way that helps you get the education you deserve.
So grab a calculator, a cup of coffee, and maybe a friend to laugh with. You’ve got this. And when you finish, you’ll feel like a financial wizard—ready to tackle any form the universe throws at you. Go ahead, make the system work for you.
