How To Calculate Pension In Net Worth

So, you’re staring at your net worth spreadsheet, feeling pretty good about your savings, your 401(k), maybe some real estate. But then you hit a wall. Where does that cozy, p...

So, you’re staring at your net worth spreadsheet, feeling pretty good about your savings, your 401(k), maybe some real estate. But then you hit a wall. Where does that cozy, promised pension fit in? It feels like a ghost asset, right? Not cash in hand, but not nothing. Let’s untangle this financial mystery together, and I promise, it’s way cooler than it sounds.
First, a pension isn’t a lump sum you can touch today. It’s a future stream of income. Think of it like a magic money tree that starts dropping cash only when you retire. The trick is figuring out what that tree is worth right now. That’s where a little financial wizardry comes in.
Why Bother? Isn’t Net Worth Just What I Own?
Good question! Net worth is usually your assets minus your debts. But a pension is a promised asset. Ignoring it is like saying your uncle’s promise to buy you a car isn’t real until he hands over the keys. Why would you leave money on the table, especially a guaranteed one? Including your pension gives you a truer picture of your financial health, like seeing the whole iceberg, not just the tip.
Must Read
It also changes how you see your “wealth.” Your 30-something friend with a huge stock portfolio might look rich. But you, with a solid pension, might have a safer, more predictable future. It flips the script on who’s actually “winning” at the money game.
The Simple Formula: The Present Value Trick
You don’t need a finance degree. The simplest method is to estimate your pension’s present value. Here’s the chill way to do it. First, guess your annual pension payment. Let’s say $20,000 a year. Then, estimate how long you’ll collect it. If you retire at 65 and plan for 20 years, that’s $400,000 in raw cash.
But a dollar tomorrow is worth less than a dollar today. So you discount it by a reasonable rate, like 4% or 5%. You can use a free online “present value of annuity” calculator. Plug in $20,000 for 20 years at 5%. Boom—the calculator spits out roughly $250,000. That’s your pension’s current value.
 How Much is Your Pension Worth? Calculate its value to your net worth
Wait, Should I Use My Own Rate?
Yes, this is where you get to play financial detective. That 4% to 6% discount rate is key. A lower rate (like 3%) makes the pension look bigger. A higher rate (like 7%) shrinks it, because you’re assuming you could earn more by investing that money yourself. Think of it like choosing how much you believe in the “magic tree.” I’d suggest 5% as a chill middle ground for a government or stable company pension.
This is also where it gets interesting. If you have a cost-of-living adjustment (COLA) on your pension, it’s worth more. A non-COLA pension is like a stale bagel—same amount every year. But a COLA pension? That’s a rising tide that floats all boats. Use a lower discount rate (like 3%) for those to reflect the growth.
The Fun Comparison: Are You a Pension Millionaire?
Here’s the mind-bending part. Let’s say your present value calculation spits out $400,000. You might not have a million-dollar beach house, but your pension is equivalent to a fat, safe bond portfolio. In the investing world, a bond yielding 5% that pays $20,000 a year is worth $400,000. So you’re basically a bond millionaire in disguise.
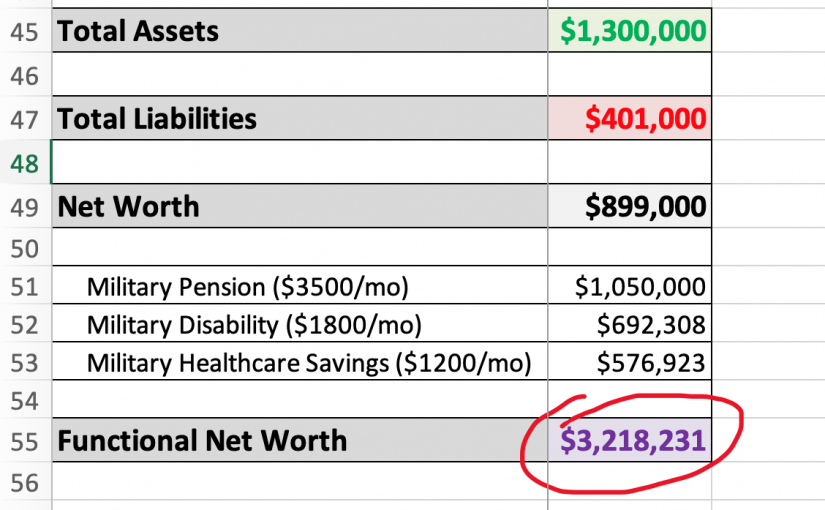 Calculating Functional Net Worth – Living The FIgh Life
Compare that to your neighbor who bought a rental property. He has a mortgage, a leaky roof, and tenants to chase. You have a spreadsheet with a clean number. Who sleeps better at night? Your pension is like a financial weighted blanket—steady, warm, and predictable.
The Big Caveats: Don’t Over-Inflate Your Ego
Not all pensions are created equal. A corporate pension from a dodgy company is like a unicorn—magical if it exists, but unlikely. A state or federal pension is generally rock-solid. Also, if you’re not fully vested, don’t count it yet. Vesting means you actually own the promise. If you leave in two years, you might get zero.
Another thing: life expectancy. If your family lives to 95, that $250,000 pension could actually be worth $350,000. Plan for a longer life unless you have a crystal ball. And if you have a spouse who gets survivor benefits, the value increases further because the money tree drops cash for two people.
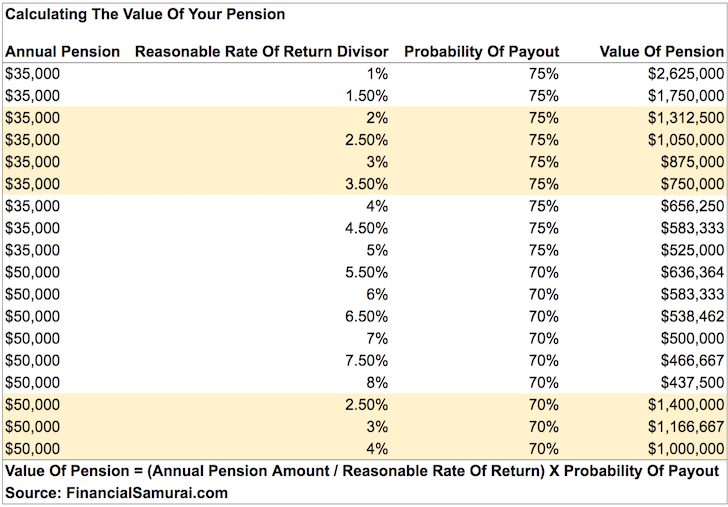 How Do I Calculate The Value Of My Pension? - Financial Samurai
Should You Actually Add It To Your Net Worth?
Here’s the real talk. Some financial nerds say “no,” because it’s not liquid—you can’t spend it tomorrow on a pizza. But they’re missing the point. Your net worth is a scorecard, not a spending list. Including your pension makes that scorecard honest. It shows you’re not just a saver; you’re a future-income generator.
Plus, it’s empowering. When you see your net worth double because you unlocked the pension value, you feel like a financial superhero. “Oh, I only have $50k in cash? No biggie—I’ve got a $200k pension kicker.” It’s like finding a crisp $100 bill in an old winter coat. Totally unexpected, totally yours.
So go ahead. Open that calculator. Plug in your pension amount. Watch the number grow. You’re not just rich right now. You’re rich later, and that’s the coolest kind of rich. Just don’t forget to tip the magic money tree.
