How To Calculate Personal Net Worth

So, you want to know your personal net worth. Don’t panic! This isn’t a test, and there’s no pop quiz at the end. It’s just a fancy way of asking, “If I sold everything and pa...

So, you want to know your personal net worth. Don’t panic! This isn’t a test, and there’s no pop quiz at the end. It’s just a fancy way of asking, “If I sold everything and paid off all my debts, how much cold hard cash would I have in my pocket?” We’re basically playing a grown-up game of Monopoly, but with real feelings and less chance of flipping the board.
First, grab a coffee. Or a stiff drink. No judgment here. You’ll also need a calculator, a piece of paper, and a willingness to face the music. Ready? Let’s dive into the math that makes you feel like a financial wizard—or a circus clown. Either way, we’ll get through it together.
Step 1: Add Up Everything You Own
Think of this as your “gross worth” or your “hoarder’s delight” list. Start with the big stuff: your house, your car, that vintage lamp you swear is worth a fortune. Be honest about the value—use what you’d actually get if you sold it today, not what you hope it’s worth. Zillow is not your fairy godmother.
Must Read
Now, add your bank accounts. Checking, savings, the jar of quarters on your dresser. Throw in your investments: 401(k), IRA, that random stock your uncle recommended—and the penny stocks that tanked. (We don’t judge losers here.) Don’t forget the cash in your mattress, but maybe leave out the $20 from your aunt’s birthday card.
Next, list your “stuff.” Furniture, electronics, jewelry, that collection of Funko Pops that might be worth something. A good rule? If you could sell it for more than a pizza, add it. If it’s a broken toaster, leave it—it’s emotional baggage, not an asset. When you’re done, total it all up. This is your total assets number. Feel free to high-five yourself.
Step 2: Now, the Gross Part—Your Debts
This is where we put on our big-kid pants. List every single thing you owe. Mortgage, car loan, student loans, credit card balances, that $50 you borrowed from your friend last month. Yes, even the IOU for the pizza you split. Everything. No hiding.
 Free Personal Net Worth Calculator Excel Template - Track & Monitor
This step feels a bit like stepping on a Lego in the dark—it hurts, but you have to do it. Your total debts might be a big number. That’s okay! You’re not alone. Most people have more debt than a telehealth commercial. Just write it down. You can cry later.
Add up all those scary figures. This is your total liabilities number. It’s the financial equivalent of a villain’s origin story. But don’t worry—the hero (you) is about to triumph. Kind of.
Step 3: The Magical Subtraction
Alright, here’s the big moment. Take your total assets and subtract your total liabilities. That’s your net worth. If the number is positive, congratulations! You’re in the black. You could buy a small island or a slightly used kayak. If it’s negative, well… welcome to the club. Most people start in the negative zone. It’s like the financial version of being a freshman—awkward but temporary.
Example: You own a house worth $300,000, have $20,000 in savings, and a car worth $15,000. Your debts: a mortgage of $250,000, a car loan of $10,000, and $5,000 on credit cards. Your math: $335,000 (assets) minus $265,000 (liabilities) = $70,000 net worth. You’re doing better than a squirrel with a single acorn.
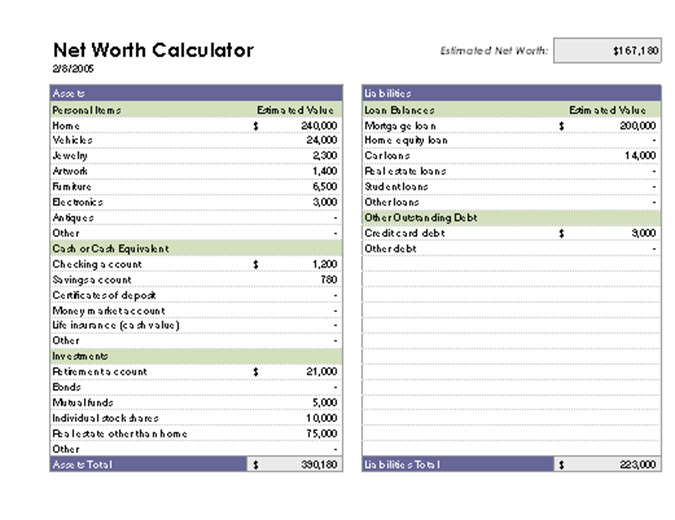 Net worth calculator
But what if you have $50,000 in assets and $80,000 in student loans? That’s -$30,000. Don’t freak out! This is just a snapshot. Your net worth isn’t your self-worth—it’s a number that changes every time you pay off a bill or buy a latte.
Why Bother With This?
Because knowing your net worth is like knowing your weight. It’s not fun, but ignoring it doesn’t make it go away. It gives you a baseline. Next year, you can compare and see if you’re moving toward that island—or at least toward a new couch. It also helps you spot if your debts are eating you alive (hello, credit card interest) or if your savings are growing like a weed.
Plus, it’s a great party trick. “Hey, want to see my net worth spreadsheet?” Everyone will either be impressed or slowly back away. Either way, you win.
Pro Tip: Don’t Overthink the “Stuff”
You might feel tempted to count your clothes, your records, or your collection of souvenir shot glasses. Don’t. Unless you plan to sell them on eBay in the next week, they’re not liquid. They’re clutter with sentimental value. Count only the big, sellable items—and maybe your car if it’s not a total lemon. Your socks? Not an asset.
 Net Worth – Here’s Everything You Need To Know - How to Money
Also, don’t count future earnings. Your salary hasn’t landed in your bank yet. It’s like counting chickens before they hatch—and then the fox eats them. Only count what you have right now, this second. Unless you’re holding a winning lottery ticket. Then count it, and invite me to your yacht party.
What To Do With This Number
Now that you have your net worth, use it. Check it once a month or once a quarter. If it’s negative, make a plan to pay down high-interest debt first. If it’s positive, think about investing more. If it’s zero, you’re perfectly balanced—like a financial zen master. Mostly, just don’t panic. This number is a starting line, not a finish line. You can always move the goalpost.
Remember, Jeff Bezos probably had a negative net worth once. (Okay, he started a garage, but you get the point.) Your net worth is just a tool—a weird, mathy, slightly uncomfortable tool. But it’s yours. Use it to make better choices. Or to brag at parties. I’m not judging.
So go ahead, calculate. You might be surprised. You might be horrified. But at least you’ll know. And knowledge is power—or at least a reason to refill your coffee. Cheers! ☕
