How To Calculate Value Of Pension For Net Worth

You know that moment when you’re trying to figure out your net worth, and your pension sits there like a mysterious uncle at a family reunion? You know he’s got money, but nob...

You know that moment when you’re trying to figure out your net worth, and your pension sits there like a mysterious uncle at a family reunion? You know he’s got money, but nobody knows exactly how much. It’s awkward, and you just want to put a number on it so you can move on with your life.
Here’s the thing: your pension isn’t just a vague promise. It’s a financial asset, just like your house or that vintage guitar you swear you’ll learn to play. The trick is to convert that future income into a cold, hard number you can add to your net worth spreadsheet today.
Why Bother? Because You’d Never Ignore Cash in Your Sock Drawer
Think of your pension as a secret cash machine that activates when you hit sixty-something. If you ignore its value, you’re basically saying, “Sure, I’ll ignore a giant pile of future money.” That’s like having a winning lottery ticket and using it as a bookmark.
Must Read
When you calculate it, you’ll feel like a financial detective who just solved a mystery. Suddenly, your net worth might jump by six figures. And you can stop playing the guessing game whenever someone asks, “What’s your net worth?”
The “Lump Sum vs. Monthly Check” Dilemma
First, decide if you have a defined benefit pension (the old-school kind that pays you every month) or a defined contribution plan (like a 401k). The latter is easy—it’s just the account balance. The former is where the magic math happens.
If your pension promises you $1,500 a month for life, you need to figure out what that income stream is worth today. It’s like asking: “If I had a goose that lays golden eggs, how much would I sell the goose for?”
 Defined Benefit Pension Calculator - National Pension Helpline
The Simple Math: The “20x Rule” (No PhD Required)
Here’s the cheat code most people don’t tell you: multiply your annual pension income by 20 to 25. That’s a quick, dirty estimate of its present value. For example, if you’ll get $30,000 a year, multiply that by 20, and you get a $600,000 asset.
It’s not perfect, but neither is your aunt’s potato salad recipe. It gives you a solid ballpark. Use 20 if you’re conservative, 25 if you feel lucky. Either way, it’s better than the “I’ll just ignore it” approach.
If you want to be fancy, you can adjust for inflation or your life expectancy. But honestly, for a net worth calculation, this is good enough. You’re not pricing a Picasso; you’re just trying to make your financial picture look a little less blurry.
The “Fudge Factor” and Why You Should Use It
Pensions aren’t always guaranteed. So, apply a discount rate based on how reliable your pension is. Government pensions? Use a 3-4% discount. A struggling company? Maybe 6-8%. Think of it as the “stuff-happens” tax.
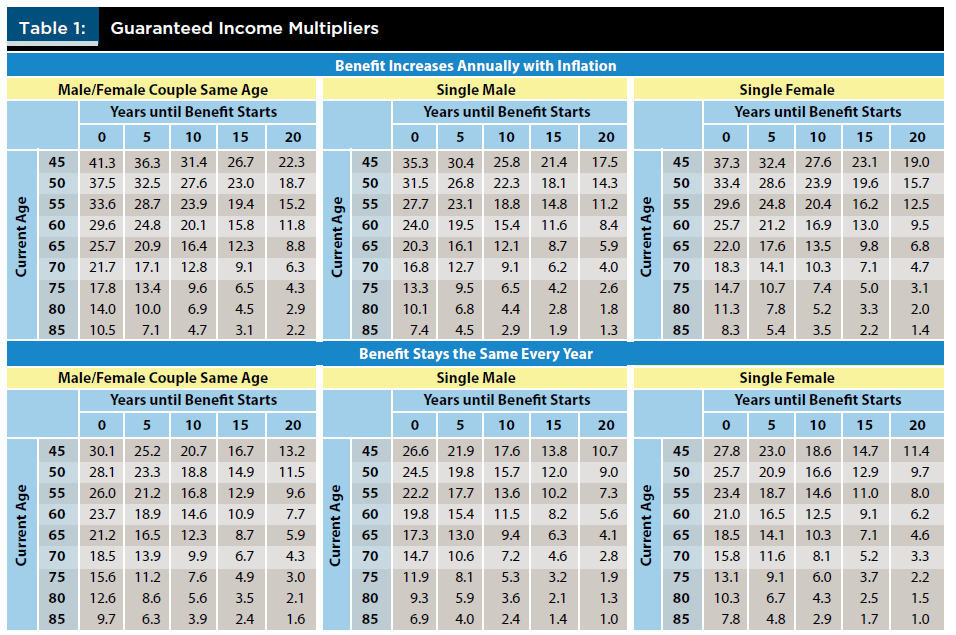 How To Calculate Value Of Pension For Net Worth (Updated 2026). - Cine
For example, if your $30,000 pension feels definitely solid, use a 4% discount rate. The formula is: annual income divided by the discount rate. So $30,000 ÷ 0.04 = $750,000. That’s the present value. If you use 6%, it shrinks to $500,000. See? You’re basically deciding how much risk you want to ignore.
A Real-Life Anecdote That Will Make You Nod
My buddy Gary thought his pension was worthless because he couldn’t cash it out. He’d say, “It’s like a coupon for a free car you can only use in 2040.” I made him do the 20x math. When he saw it was worth $400,000, he nearly spilled his coffee. Suddenly, he wasn’t “just” a teacher—he was a secret hundred-thousandaire.
He then updated his net worth on that app he uses, and his wife asked why he was grinning like a kid who found a $20 bill. He said, “I just discovered I’m rich in delayed gratification.” She rolled her eyes, but she smiled too.
When Not to Count It (The “Don’t Be an Idiot” Rule)
Don’t include your pension if you’re planning to leave the job tomorrow. If you’ll lose it, it’s not an asset—it’s a tease. Only count it if you’re vested (that means you’ve worked long enough to keep it no matter what).
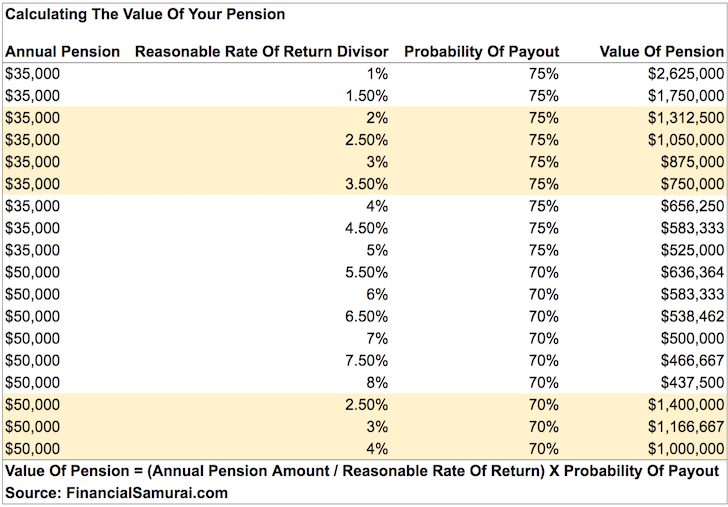 How Do I Calculate The Value Of My Pension? - Financial Samurai
Also, if your pension has a huge taxable chunk, remember that net worth is gross value. You don’t subtract taxes unless it’s an IRA. So let it be big and beautiful. Future you can worry about the IRS.
Final Nudge: Just Do It, You Goof
Grab your latest pension statement. Look for the “estimated monthly benefit at normal retirement.” Multiply by 12. Then multiply by 20. Write that number down. Paste it into your net worth tracker. Watch your total jump like a cat on a hot tin roof.
You’ll feel like you hacked the system. Because honestly, most people skip this step and walk around with an incomplete financial report. Don’t be most people. Be the person who knows their pension is a silent superhero in their net worth story.
And if anyone asks, just say, “Oh, the pension? It’s worth about a small house in Ohio.” That’ll get a laugh—and a nod of respect.
