How To Figure Net Worth Of A Person

So, picture this: I’m at a barbecue last summer, and my buddy Dave—who drives a beat-up Honda and wears the same three t-shirts on rotation—casually mentions he just bought a...

So, picture this: I’m at a barbecue last summer, and my buddy Dave—who drives a beat-up Honda and wears the same three t-shirts on rotation—casually mentions he just bought a cabin. Upstate. With cash. Meanwhile, my other friend Sarah, who posts photos of her avocado toast in a penthouse, is quietly stressing about her credit card minimums. That’s when it hit me: net worth has almost nothing to do with the sneakers you’re wearing or the zip code you brag about. It’s the financial truth serum we all need but rarely talk about over ribs.
Net worth is simply what you own minus what you owe. Yes, it’s that boring. But think of it like a bathroom scale for your money life: it doesn’t care about your intentions, your Instagram aesthetic, or your “potential.” It just shows the raw number. (And like a scale, it can sting if you haven’t looked in a while—but ignoring it never made the number smaller.)
Step One: Tally Up Everything You Own (The Fun Part)
Grab a coffee, a napkin, or a spreadsheet—I won’t judge your method. List out your assets: cash in checking, savings, that emergency fund hidden under a mattress (please don’t actually do that). Add your retirement accounts—401(k), IRA, even that old pension from your college job you forgot about.
Must Read
Now, get real with your stuff. Your car? Only count what you could sell it for today on Craigslist, not what you paid for it three years ago. Your house? Use a rough market estimate, not your nostalgic “first-home” value. Include jewelry if it’s valuable, but leave out that Beanie Baby collection—be honest with yourself. (Yes, that means your signed Funko Pop is not an investment, sorry.)
Don’t Forget the Silent Assets
That $500 security deposit your landlord holds? It’s an asset. The cash value in your life insurance policy? Asset. Even the $50 gift card to Target you got for your birthday counts—because it’s essentially money you can spend. The trick here is simple: if you can turn it into cash today, list it. No fantasy valuations, please. If you’re not sure, underestimate—your future self will thank you.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
Step Two: The Gut Punch—Your Liabilities
Now for the part nobody enjoys. Write down every single penny you owe. Start with the big stuff: mortgage balance, car loan, student loans. Then get petty—credit card balances, that $200 you borrowed from your mom, even the unpaid tab at your local coffee shop if they actually hound you for it.
Include the hidden debts too. Personal loans from friends, any medical bills you’re chipping away at, and that buy-now-pay-later plan for the couch you bought last Black Friday. This isn’t about shame—it’s about accuracy. (Remember, Dave with the cabin probably has zero credit card debt, while Sarah’s penthouse is 90% financed. The numbers don’t lie.)
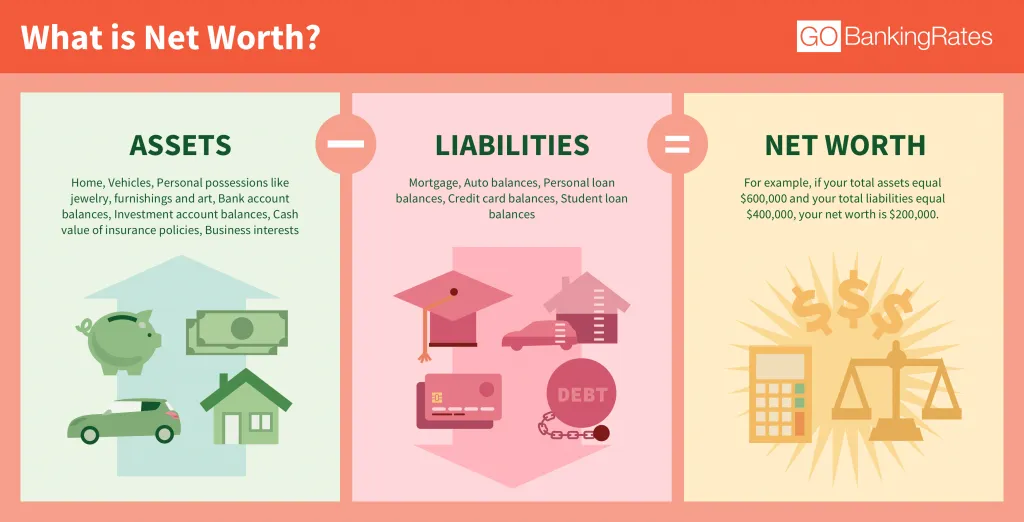 Net Worth: What It Is and How To Calculate It | GOBankingRates
The Tricky Part: Your Car Lease vs. Your Car Loan
If you lease a car, you don’t own it—so that car doesn’t go in your assets. But the monthly payment? That’s still a liability because you’re obligated to pay it. If you financed a car, subtract the loan balance from the car’s current value. Most people overvalue their cars by about 30%. Be ruthless. It hurts, but it’s better than being surprised when you try to sell it.
Step Three: The Simple Math
Take your total assets number. Subtract your total liabilities. That’s your net worth. If it’s positive, congrats—you’re technically in the black. If it’s negative, you’re not alone; most thirty-somethings have a negative net worth because of student loans and first mortgages. The real magic is tracking it year over year. A rising net worth is the only financial flex that matters.
 Statement of Net Worth: A Step-by-Step Guide
Here’s the ironic twist: that friend with the flashy lifestyle often has a lower net worth than the frugal nerd who reads this article. Why? Because net worth rewards accumulation, not spending. A person making $40,000 who saves 20% could have a higher net worth than someone earning $150,000 who spends it all on Peloton subscriptions and delivery sushi. (Yes, I’m looking at you, Sarah.)
Final Side Note: The “Age Benchmark” Trap
Don’t obsess over what a “good” net worth looks like for your age. Some guy on the internet will tell you to have $50,000 saved by 25. Ignore him. Your only benchmark is your own past self. If your net worth grew by 5% this year, that’s a win. If it dropped because you bought a house—guess what?—that’s still net positive for your life, even if the number looks ugly for a year.
So go ahead. Fetch that napkin or open a Google Sheet. Do the math, laugh at the number, and then start the slow, boring, deeply satisfying work of making it grow. And next time you see Dave at the barbecue, maybe ask him if his cabin has a guest room. Just don’t ask him his net worth—he likely doesn’t need to calculate it. He already knows.
