How To Value A Pension For Net Worth

So, picture this: I’m at a backyard BBQ, and my friend Dave is bragging about his net worth. He’s got his stock portfolio, his rental property, and a shiny 401(k) figure he ke...

So, picture this: I’m at a backyard BBQ, and my friend Dave is bragging about his net worth. He’s got his stock portfolio, his rental property, and a shiny 401(k) figure he keeps refreshing on his phone. Meanwhile, I mention my pension from my old teaching gig. Dave squints at me and says, “But how do you even value that? It’s not like you can sell it on eBay.”
He had a point. A pension feels like a ghost asset—it’s there, but you can’t grab it. That’s exactly why you need to pin a number on it for your net worth. Otherwise, you’re the guy with a secret superpower who forgets to use it.
Why Bother Valuing It?
Your net worth isn’t just what you can withdraw from an ATM tomorrow. It’s the total picture of your financial health, including future promises. A pension is a promise to pay you a steady stream of cash for the rest of your life.
Must Read
Ignore it, and you’re essentially walking around with a winning lottery ticket stuffed in your sock drawer. And hey, if you ever need a loan or want to feel smug around Dave, having a clear number helps.
The Simple Math (Without the Headache)
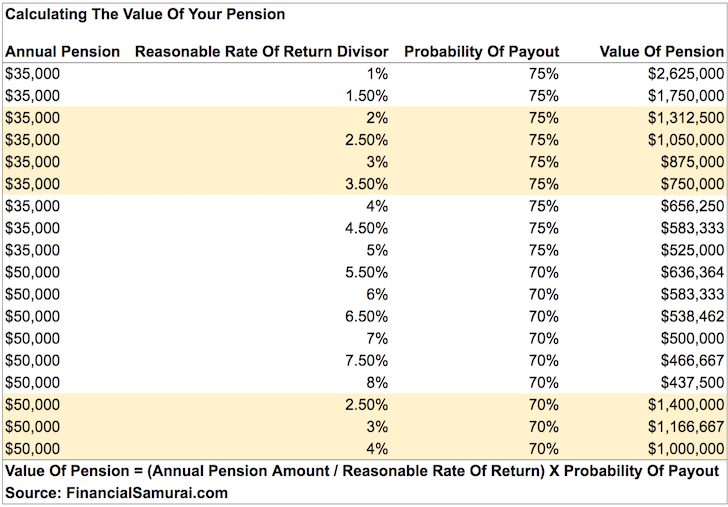
The most common trick is to treat your pension like a bond. You take the annual income you expect to receive and divide it by a discount rate. Sounds fancy, but it’s just a guess about what a safe investment would pay you.
Let’s say your pension will give you $20,000 a year starting at age 65. Use a discount rate of 4% (a reasonable long-term bond return). You do $20,000 ÷ 0.04, and boom—that’s $500,000 in today’s money. Yes, really.
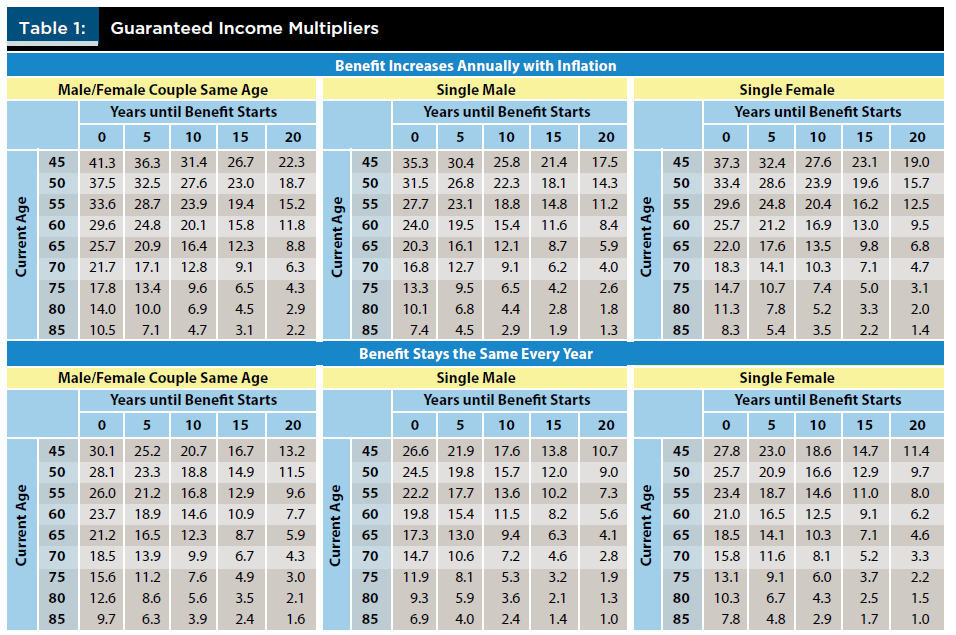 How To Calculate Value Of Pension For Net Worth (Updated 2026). - Cine
Side note: If you use a lower discount rate (like 3%), the number goes up—to about $667,000. That’s the weird magic of math. You can tweak it to be more conservative or aggressive, but don’t get too cute with the numbers.
The "Wait, I’m Still Working" Problem
What if you’re not retired yet? You’ll need to discount that future lump sum back to today’s dollars. For example, if that $500,000 is 20 years away, you’d divide it by (1.04)^20. That gives you roughly $228,000 right now.
Yeah, it’s a lot smaller. But it’s still real money. Think of it as a huge, slow-growing IOU from your past self to your future self.
Pro tip: If your pension has a cost-of-living adjustment (COLA), bump up the annual income number by 2% or so each year. Otherwise, you’re undervaluing it. Inflation is a beast, and your pension might actually fight it.
 How Much is Your Pension Worth? Calculate its value to your net worth
The "Gross vs. Net" Trap
Don’t forget taxes. A pension payment is usually taxable income (unless it’s from a Roth-like account). So if you’re in a 25% tax bracket, that $20,000 pension is really $15,000 in your pocket.
Recalculate with $15,000 and a 4% discount rate, and you get $375,000 instead of $500,000. That’s a big haircut. But being honest about taxes keeps your net worth from being a fantasy island.
Side note: If you live in a state with no income tax, give yourself a tiny mental high-five. It makes your pension worth a bit more.
When to Throw the Formula Out the Window
This math works great for a traditional defined-benefit pension. But if your pension is a cash balance plan (where you see a dollar amount that grows every year), just use that account balance directly. No need for fancy math.
 Pensionsvalet
Also, if your pension is from a shaky company or government, you might want to add a “haircut” of 10-20%. It’s not pessimism; it’s just being a realist. I’d rather be pleasantly surprised than blindsided.
Putting It All Together
So, back to Dave. I told him my pension is worth around $400,000 in today’s after-tax terms. He stopped refreshing his phone and looked impressed. “So you’re secretly rich?” he asked. I shrugged and said, “No, just old and patient.”
Now, go grab your pension statement. Use the formula, adjust for taxes, and add that number to your net worth spreadsheet. It’s not a liquid asset, but it’s real—and it’s yours.
And the next time someone brags about their 401(k) balance, just smile and know you’ve got a hidden ace. Just don’t try to spend it on a car today. Please. That would be ironic and also a terrible idea.
