How To Value A Pension In Net Worth

My friend Dave once told me, with complete seriousness, that his net worth was zero. He had a good job, a 401(k) with some cash, and a paid-off Honda Civic. But he also had a...

My friend Dave once told me, with complete seriousness, that his net worth was zero. He had a good job, a 401(k) with some cash, and a paid-off Honda Civic. But he also had a solid pension from his years at a utility company. “I don’t count it,” he shrugged, “because I can’t touch it right now.” I nearly choked on my coffee. Dave, my dude, you are sitting on a goldmine and calling it a paperweight.
Dave’s mistake is incredibly common. We obsess over our stock portfolios, our home equity, and our checking account balances. But when a pension shows up—that promise of monthly cash for life—we get vague. It feels like Monopoly money, or something that belongs to “future you.” The truth is, a pension is arguably the most valuable asset many people own, and ignoring it is like saying your house has no value because you live in it.
Why Your Pension Is a Beast of an Asset
First, let’s acknowledge the elephant in the room: not all pensions are created equal. A government pension backed by state law is a different animal from a corporate pension that might get frozen. But if you have a defined benefit plan (one that pays a specific amount every month until you die), you are holding a financial unicorn. It is guaranteed income. It does not care if the stock market crashes, and it doesn’t run out.
Must Read
To value it, you need to think like an insurance company. Ask yourself: How much money would I need to invest today to buy a stream of income that matches my pension? That “present value” is the number you should slap onto your net worth statement. It’s not a perfect science, but it’s way better than zero.
The Annuity Equivalent Method (The Simple Way)
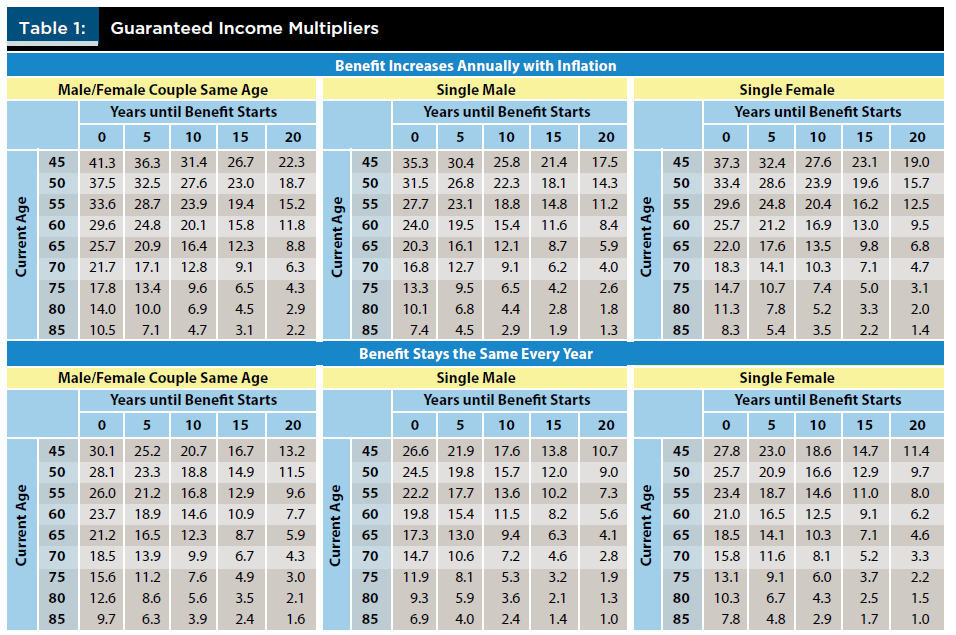
Here’s the back-of-the-napkin calculation. Let’s say your pension will pay you $2,000 per month starting at age 65. You can look up the price of a “single-life immediate annuity” from a reputable insurer (websites like ImmediateAnnuities.com do this for free). For a 65-year-old today, that $2,000 a month might cost roughly $350,000 to $400,000 to buy.
 How Much is Your Pension Worth? Calculate its value to your net worth
Yes, you read that right. $2,000 a month is worth about $350,000 in liquid cash. If you have a $50,000 401(k) and a $350,000 pension value, your real net worth is $400,000, not $50,000. (Side note: tell Dave that his “zero” net worth just jumped to six figures. He might owe you a beer.)
But Wait—The Fine Print (Because There’s Always Fine Print)
The annuity method gives you a ballpark, but life loves curveballs. If your pension has no cost-of-living adjustment (COLA), that $2,000 will be worth less every year thanks to inflation. In that case, discount the value by maybe 20-30%. A non-COLA pension is like a salary that never gets a raise—it’s still valuable, but it’s a shrinking slice of the pie.
Also, consider your health and your spouse. Are you in good health? A pension that pays for life is even more valuable since you might collect it for 30 years. Have a partner? A joint-and-survivor pension (that pays your spouse after you die) is worth more than a single-life option. Don’t forget to factor in survivor benefits—or the lack thereof.
 How To Calculate Value Of Pension For Net Worth (Updated 2026). - Cine
The “Discount Rate” Trap (Don’t Overthink This)
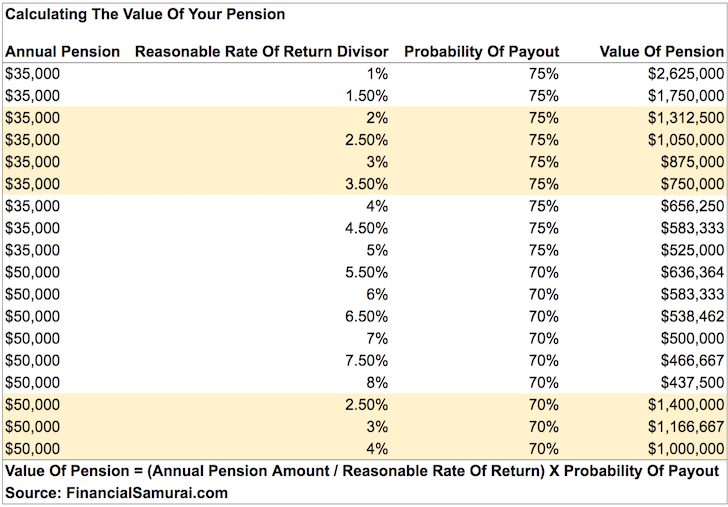
Some finance nerds will tell you to discount the pension using a “risk-free rate” like 10-year Treasury yields. Listen, I love math as much as the next person, but trying to calculate the exact net present value of a pension using a 4% discount rate is like trying to measure the ocean with a teaspoon. Use the annuity quote method. It’s simpler, and it reflects what the market actually charges for guaranteed income. You are not a hedge fund; you are a person trying to feel richer. (And you should.)
One big caveat: Never include the present value of your pension in your “liquid net worth” column. That’s a different number. Your pension is illiquid: you can’t sell it, you can’t borrow against it easily, and you can’t cash it out (usually). So keep two numbers: your easy-access net worth (cash, stocks, home equity) and your total net worth (which includes the pension). The second number tells you how truly wealthy you are.
 Pensionsvalet
Why This Matters Right Now
Ignoring your pension value can make you feel poorer than you are, which leads to weird decisions. You might hoard cash, work too long, or avoid taking calculated risks. Conversely, if you overvalue it, you might retire too early and discover your non-COLA pension buys you a bag of groceries in 2045. The goal is moderate accuracy.
Here’s the ironic punchline: Dave eventually sold his paid-off Honda and bought a used SUV, citing “cash flow concerns.” He forgot that his pension alone was generating more cash flow than his car payment ever would. We all have blind spots. Your pension isn’t a phantom; it’s a $400,000 check that lands in your lap slowly. Treat it as such.
So go ahead, pull up that pension statement. Find the monthly amount you’re owed. Multiply by 12. Then look up the cost of an annuity. Add that number to your net worth spreadsheet. How does that feel? Exactly. Now go tell Dave he’s a secret millionaire.
