How To Value Pension In Net Worth

Let’s be real. You probably ignore your pension when you calculate your net worth. It feels like magic money from the future. But ignoring it is like hiding a winning lottery...

Let’s be real. You probably ignore your pension when you calculate your net worth. It feels like magic money from the future. But ignoring it is like hiding a winning lottery ticket in your sock drawer.
Your net worth is supposed to show what you own minus what you owe. And that pension? You own it. You just have to figure out how much that future paycheck is worth right now.
Don’t worry. This isn’t calculus. It’s more like putting a price tag on a unicorn.
Must Read
Why Bother? The Fun Factor
First, a quirky truth. Most people count their car, their couch, and their crypto. But they leave out the pension that could pay for their groceries for thirty years. That’s like bragging about your three-dollar coffee while ignoring the fifty-dollar bill in your back pocket.
Adding your pension makes you look richer on paper. And it’s hilarious when your retirement calculator suddenly does a backflip. Suddenly, you’re not just scraping by. You’re a financial ninja with a secret weapon.
The fun part? You get to debate with your friends. “My net worth is a million!” you’ll say. They’ll gasp. Then you’ll admit half of it is in pension promises. The look on their face is priceless.
The “Simple” Math (It’s Easier Than You Think)
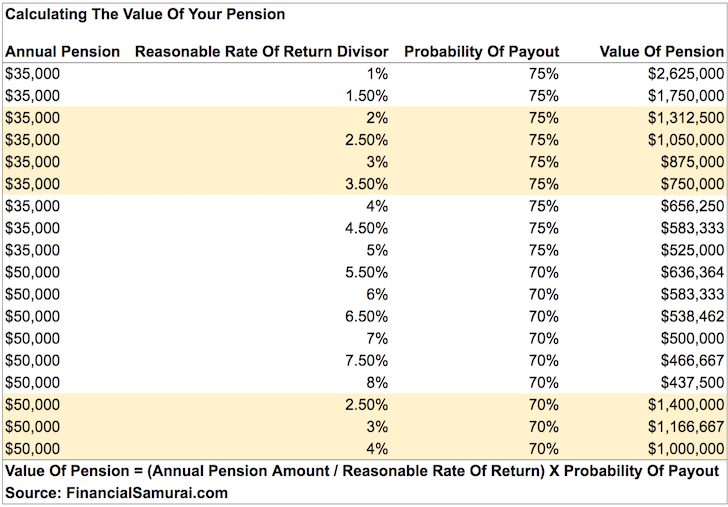
Valuing a pension is weird because it’s not a bank account. It’s a promise. You can’t sell it for cash today. But you can figure out its value using a trick called the “multiplier method.”
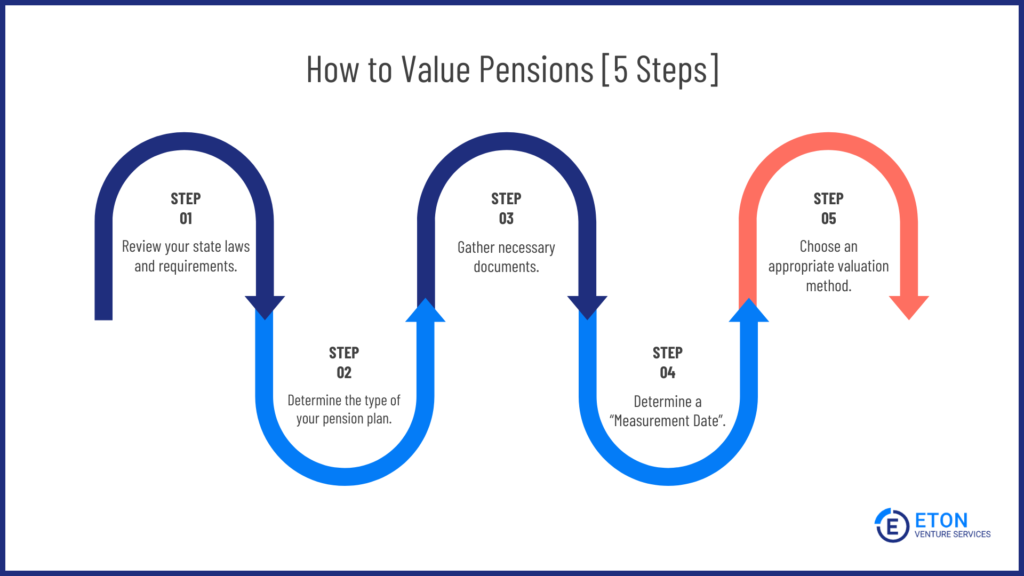 Pensions Valuation in Divorce: 5 Steps to Value Your Pension Plan
Take your annual pension payment. Let’s say you’ll get $20,000 per year. Now multiply that by a number. For a healthy 65-year-old, the multiplier is usually between 15 and 25. Why? Because you might live 20 more years, duh.
So, $20,000 x 20 = $400,000. Boom. That’s a rough value for your net worth. It’s not perfect, but it’s better than pretending it’s worth zero.
Fun fact: The exact multiplier comes from actuarial tables—math used by insurance companies to bet on your death. Cheery, right? But it works.
The “Google It” Method
If math makes you twitch, use the internet. Type “pension valuation calculator” into Google. You’ll find free tools from Vanguard or Fidelity. They ask for your age, your pension amount, and your mortality risk. Spooky? Yes. Effective? Also yes.
These calculators use discount rates. That’s fancy talk for “how much interest you’d earn if you had the cash today.” A lower discount rate makes your pension look bigger. A higher rate makes it smaller. It’s like choosing between a skinny mirror and a funhouse mirror.
 How Much is Your Pension Worth? Calculate its value to your net worth
Pro tip: Use a discount rate of 4% to 6%. That matches long-term investment returns. Anything lower makes you feel like a pension billionaire. Anything higher makes you cry.
The “Lump Sum” Trap
Some pensions let you take a lump sum instead of monthly payments. That lump sum is the easiest value to use. Just plug it into your net worth. Done. But here’s the funny part: the lump sum is usually smaller than the total value of monthly payments. Because companies know you’ll spend it on a boat.
If you take the lump sum, your net worth gets a one-time boost. If you keep the pension, your net worth is like a slow-burning candle. Both are fine. Just don’t double-count. That’s like eating dessert and claiming you’re on a diet.
Quirky detail: Some pensions pay your spouse after you die. That changes the value by about 10-15%. Because love is expensive.
When To Ignore The Number (And Why That’s Okay)
Here’s the secret no one tells you. Your pension value is not liquid. You can’t use it to buy a house or a Ferrari tomorrow. So, don’t brag about it on a first date. “My net worth is huge!” they’ll say. Then you’ll hand them a spreadsheet of your pension assumptions. Romance killer.
 Pensionsvalet
Use the pension value for long-term planning, not daily flexing. It’s your safety net. It’s your “I can take a lower-paying job” card. It’s the reason you can laugh when the stock market crashes.
And remember: if your pension is from a shaky company, discount it like a expired coupon. If it’s from the government, it’s as solid as a rock—but politicians still argue about it. Life is weird.
The Final, Ridiculous Truth
Valuing your pension is more art than science. You’re guessing how long you’ll live, what inflation will do, and if your employer will still exist. It’s like predicting the weather for your retirement picnic.
But the act of doing it is magical. It forces you to acknowledge your future self. You stop treating your pension like a boring footnote. You start seeing it as a golden goose.
So go ahead. Crunch the numbers. Add that pension to your net worth. Stare at the bigger number. Laugh a little. Then go back to saving, because life always throws curveballs. But now you’ve got a pension bat in your hands. Swing.
