Insurance For High Net Worth Individuals

Okay, let me tell you about something that sounds super fancy but is actually pretty logical: insurance for high net worth individuals. You know, the super-rich. The people wi...

Okay, let me tell you about something that sounds super fancy but is actually pretty logical: insurance for high net worth individuals. You know, the super-rich. The people with more stuff than they can fit in a normal house. We’re not talking about just a nice car here. We’re talking private jets, art collections that could fund a small country, and maybe a wine cellar worth more than your annual salary. Yikes.
So why can’t they just buy regular homeowners insurance from the friendly robot on Geico? Because, honestly, regular insurance is like bringing a squirt gun to a wildfire. It simply wasn’t built for this level of luxury.
The “Gold-Plated Pipes” Problem
Imagine your $10 million mansion has a plumbing issue. Not a leaky faucet—we’re talking a burst pipe that ruins a custom-made, hand-painted ceiling. Regular insurance says, “Here’s a check for a new piece of drywall.” High net worth insurance says, “Let’s fly in the original artist from Italy. And by the way, we’ll handle the hotel stay while the repair happens.” See the difference? Massive.
Must Read
It’s all about the replacement cost. Their stuff isn’t from Target. If your diamond necklace goes down the drain, you can’t just buy another at the mall. High net worth policies cover the full, agreed-upon value of that specific, ridiculous item. No depreciation. No sass from an adjuster.
It’s Not Just About Money (It’s Mostly About Money)
Let’s be real: these policies are expensive. But they’re designed to solve problems that normal policies can’t even imagine. Think about liability. If a guest slips on a marble staircase at your lake house, a standard policy might cover a few hundred thousand dollars. A wealthy person’s policy? We’re talking $10 million or more in umbrella coverage. Why? Because that guest might be a CEO who sues for lost earnings. Yep, that’s a thing.
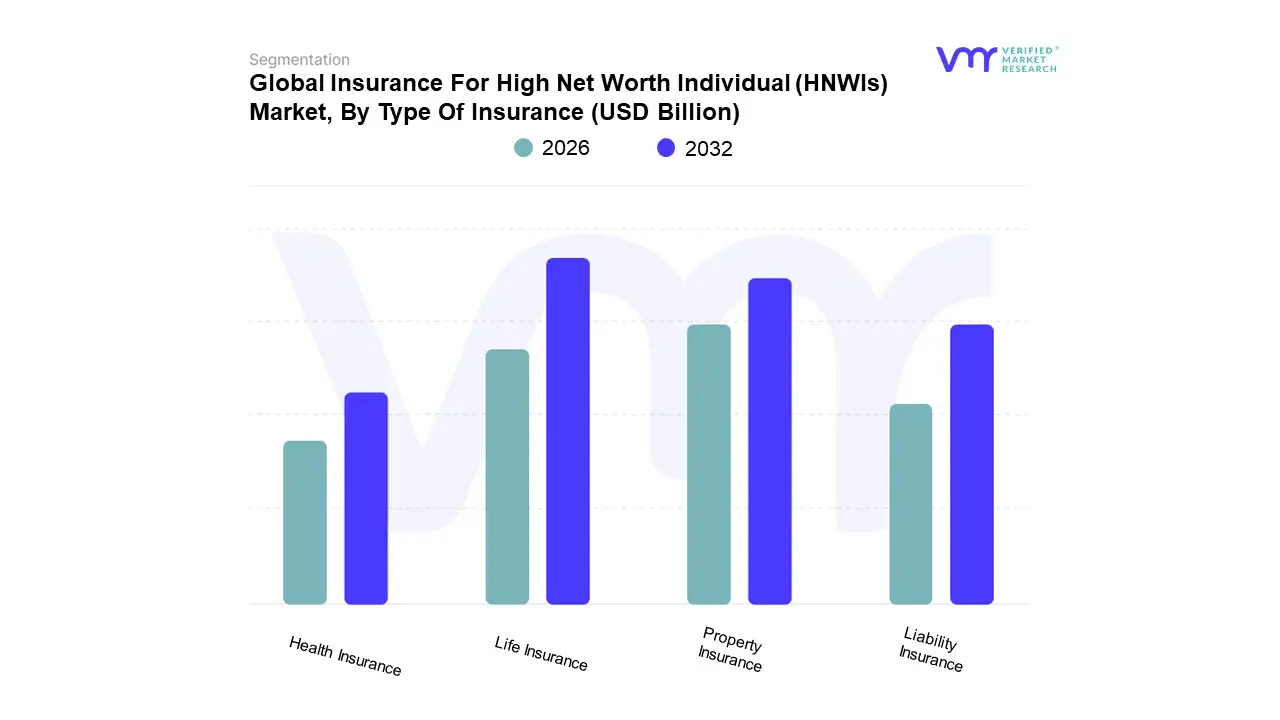 Insurance For High Net Worth Individual (HNWIs) Market Report: Size
And then there’s the security angle. If you own a vacation home in three different countries, who watches it? High net worth insurers often include global security teams. They’ll send a guard to check on your Caribbean villa after a hurricane. They’ll even arrange for a private driver if you’re stranded. It’s like having a very polite, very thorough bodyguard who also knows your insurance policy inside out.
The Weird Stuff They Insure
You wouldn’t believe the things you can add to these policies. A policy for a vintage car collection? Sure. A policy for a racehorse? Absolutely. A policy for a rare, 200-year-old violin that you play once a year? They’ll do that, too. They even insure identity theft for celebrities, because if someone steals your Instagram handle, that’s a financial crisis for a Kardashian.
Here’s my favorite: kidnap and ransom insurance. Yes, that is a real thing. If you’re a high-profile billionaire, a bad guy might try to snatch you in a parking lot. This policy covers the ransom payment, a negotiator, and even psychological care for your family. Wild, right? But hey, if you’ve got the cash, you’ve got the risk.
 Insurance for High Net Worth Individual (HNWIs) Market Size And
How Do You Even Get This?
You don’t just click a button online. Oh no. You need a specialist broker. Someone who wears expensive shoes and talks about “risk appetite” over lunch. They’ll ask you questions like, “How many cars do you own?” and “Do you keep a Picasso in the bedroom or the den?” Then they shop your profile to a handful of insurers who specialize in this niche. Think of it like a concierge for your fears.
The broker also handles the paperwork, which is a nightmare of “inland marine” coverage (that’s for stuff during shipping) and “scheduled property” lists. You’re basically writing a novel about every single valuable thing you own. It’s tedious, but it’s worth it to avoid a nightmare later.
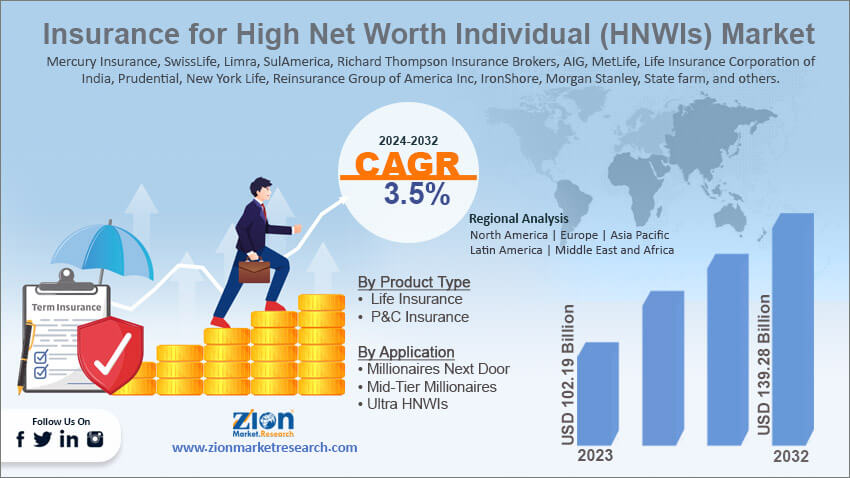 Insurance for High Net Worth Individual (HNWIs) Market Size And
The Real Perk: No Waiting, No Arguing
The best part about high net worth insurance? The claims process. Regular insurance makes you jump through hoops. You send photos, wait two weeks, argue about the deductible. For the rich? They call a number. A person answers immediately. They say, “I understand your Ferrari got flooded. We’ve already called a specialist. A rental car will be at your driveway in an hour. And here’s a $50,000 advance for your inconvenience.” No fuss. No fight. Just velvet-gloved efficiency.
It’s a very different world. They’re paying a premium to buy peace of mind and to avoid ever having a conversation with an angry claims agent. For them, time is money—actual money, not the fake kind.
So, should you feel bad for them? Nah. They have amazing insurance, but they also have a leaky, gold-plated toilet that costs $12,000 to fix. See? Problems are relative. But if you ever inherit a Rembrandt or accidentally become a tech mogul, call a specialist broker. And maybe practice saying, “Yes, I’d like the entire policy, please.” You’ll thank me later.
