Is Life Insurance Included In Net Worth

So, you’re staring at your net worth spreadsheet, sipping your third coffee, and wondering: “Does that life insurance policy I pay for every month actually count as an asset?”...
So, you’re staring at your net worth spreadsheet, sipping your third coffee, and wondering: “Does that life insurance policy I pay for every month actually count as an asset?” It’s a fair question. One that makes you feel like a financial detective, right?
Let’s just rip the Band-Aid off. It depends. Yes, I know—that’s the most annoying answer in personal finance. But hear me out, because the difference is bigger than you think.
The Quick, Dirty Rule
If you’re talking about term life insurance (the kind you rent for 20 years), please don’t include it in your net worth. It’s like including your Netflix subscription as an asset. It’s not an asset. It’s a monthly expense that buys peace of mind. Poof. Gone.
Must Read
Term insurance has no cash value. None. Zero. Nada. It’s pure protection. You pay for the promise that if you die, your family gets a pile of cash. But that promise only pays out when you’re dead. Not exactly something you can put on a balance sheet while you’re alive, is it?
Okay, But What About Permanent Insurance?
Ah, here’s where it gets fun. Whole life, universal life, variable life—these types of policies have a cash value component. That means, over time, a little pot of money grows inside the policy. That pot is an asset.
So, yes: you can include the cash value of permanent life insurance in your net worth. But—and this is a big, dramatic but—don’t get carried away. You wouldn’t count the death benefit. That’s not your money (yet). And honestly, it feels a little morbid to plan for your own payout, doesn’t it?
Think of it this way: if you have a whole life policy with $10,000 in cash value, that’s $10,000 you could theoretically take out as a loan or cash out (with penalties). That’s real. That counts. The death benefit? Ignore it for net worth.
 Understanding Premium Finance for Life Insurance: A Powerful Strategy
Why This Confuses Everyone
Here’s the sneaky part: your net worth is what you own minus what you owe. If you own a house, you count its value. If you own stocks, you count their value. But life insurance? It feels like an asset because you pay for it every month, right? Nope.
It’s like that gym membership you never use. You pay for it, but it’s not making you richer. Term insurance is the same. It’s a cost, not a treasure chest.
So don’t fall into the trap of listing your $500,000 term policy on your net worth statement. Your spouse’s face when they see that mistake would be priceless—and probably hilarious—but not accurate.
The Real World Scenario
Let’s say you’re 35, have a $400,000 term policy, and a $50,000 cash value from a whole life policy your grandpa gifted you. Your net worth should show the $50,000 in cash value. The $400,000? Invisible to your net worth calculation. Sorry, future dead you.
 High Net Worth Life Insurance: A Comprehensive Guide
But wait—there’s a twist. Some financial advisors will argue that if you’re borrowing against the policy, that loan reduces your net worth. Yes, because loans are liabilities. So if you take out a $20,000 loan against that $50,000 cash value, your net worth only shows $30,000 from that policy. It’s a bit of a headache, but it’s honest math.
The “What If” That Keeps You Up
Here’s the question nobody asks: Should you even care? Honestly, most people’s net worth is dominated by their house, retirement accounts, and a savings account. Life insurance cash value is often a tiny slice of the pie. Unless you’re a high-net-worth individual using it as a tax strategy, it’s probably not moving the needle.
But it is part of your overall financial picture. Just not in the way you’d think. Use it as a safety net, not a line item to brag about on Instagram.
And if you’re that obsessed with your net worth number, you’re probably already calculating your coffee consumption as a liability. (I see you, friend. That’s fine.)
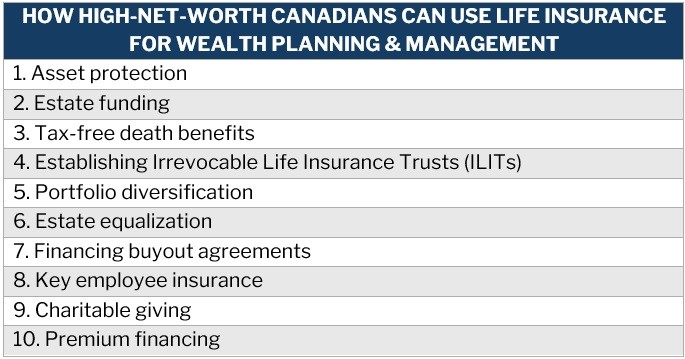 How to maximize life insurance for high-net-worth Canadians | Wealth
So, The Final Verdict
Term life insurance: NO. Don’t include it. It’s not an asset; it’s a subscription to security. Permanent life insurance cash value: YES. But only the cash value, not the death benefit.
If you’re still confused, just remember this: your net worth is about you alive, not dead. Life insurance pays off when you’re gone. You can’t take it with you—literally.
And if anyone tells you to include the full death benefit? Smile, nod, and ask them if they’d like to buy a bridge. You’re welcome.
Now, go update that spreadsheet. I’ll be over here counting my coffee expenses as assets. (It’s liquid, right?)
